As of September 2026, the U.S. Department of State has reduced the U.S. citizenship renunciation fee from $2,350 to $450. Adjusted for inflation since the 2014 increase, $450 today is equivalent to approximately $320 in 2014 dollars — the lowest real-terms cost for renunciation in more than a decade.
This is what the updated government website provides regarding renunciation:
Overview
Relinquishment of U.S. citizenship by performing certain statutory expatriating acts, including taking the oath of renunciation, voluntarily and with the intent of relinquishing U.S. citizenship, is a personal right that cannot be exercised on a person’s behalf. For example, a person’s parent(s) or legal guardian may not take the oath of renunciation for that person. A Certificate of Loss of Nationality (CLN) approved by the Department of State is the final agency determination of loss of U.S. nationality.
NOTE: STEPS 1-4 below outline the process for requesting a CLN based on taking an oath of renunciation before a U.S. diplomatic or consular officer abroad under Immigration and Nationality Act (INA) Section 349(a)(5), 8 USC 1481(a)(5). For information on the parallel process to request a Certificate of Loss of Nationality (CLN) on the basis of the commission of another potentially expatriating act under INA 349(a)(1)-(4), 8 USC 1481(a)(1)-(4), please contact your location by selecting it below.
Oath of Renunciation of U.S. Nationality
Embassy, consulate, or office providing consular services process requests to take the oath of renunciation of U.S. citizenship. Minors, individuals who do not read or write English, individuals with mental health or cognitive disability or impairment and/or guardianship, and those for whom loss of U.S. nationality would result in statelessness are invited to contact your location to discuss taking the oath of renunciation.
Taking an oath to renounce U.S. nationality before a U.S. diplomatic or consular officer overseas is a serious and irrevocable act. Therefore, you should carefully consider and fully understand the consequences and ramifications of this act prior to your decision to begin the process.
Steps to Take
STEP 1: Review the legal requirements and consequences/ramifications of taking the oath of renunciation of U.S. citizenship.
Please read the information provided by the embassy, consulate, or office providing consular services and available online at the Department of State and Internal Revenue Service links below regarding the legal requirements for taking the oath of renunciation before beginning this process. Loss of U.S. nationality is irrevocable, and you should fully understand the consequences and ramifications before beginning this process.
The Court agrees. In Mann Construction, Inc. v. United States, 27 F.4th 1138 (6th Cir. 2022), the court found that Notice 2007-83 failed to comply with the APA’s notice-and-comment procedure. Similarly here, because Notice 2009-85 has not been subject to a notice-and-comment procedure, it does not comply with the APA and thus is not binding. As such, Aroeste was not required to file Form 8854 with his amended returns.]
[See, Aroeste v. United States – where IRS Form 8854 is not binding as IRS Notice 2009-85 is invalid.]
STEP 2: Email your locationto initiate the process and receive instructions. Gather and submit scanned copies of the required documents and schedule your first interview.
To schedule an initial interview, which will be conducted by telephone or in-person at the embassy, consulate, or office providing consular services, please send an email to your location. Canada, Bern, Berlin, Amsterdam, Australia (Sydney and Melbourne), Singapore, Brussels, and Paris provide electronic first interviews
Applicants should personally review all documents and prepare all forms provided by the embassy, consulate, or office providing consular services in accordance with the instructions. DO NOT SIGN ANY FORMS BEFORE YOUR FINAL INTERVIEW.
STEP 3: Schedule and attend the final interview at the embassy, consulate, or office providing consular services with all required original documents and pay the fee.
Schedule your final interview appointment according to embassy, consulate, or office providing consular services instructions. On the day of your final interview appointment, you must bring all of the original documents you previously submitted by email. You will be asked to reschedule if you do not have the required documents at the time of your final interview appointment.
Your Consular Report of Birth Abroad, and Certificate of Naturalization or Citizenship, if applicable, generally will be retained by the embassy, consulate, or office providing consular services during the remainder of the process and then returned to you. Your U.S. passport also will be retained and, if your Certificate of Loss of Nationality is approved by the Department of State, it will be canceled before it is returned to you upon your request. If you need to travel to the United States on your U.S. passport after the second interview but before the Certificate of Loss of Nationality has been approved, please so advise the embassy, consulate, or office providing consular services at the second interview.
You will meet with a consular officer for your second interview and you will be given another opportunity to review the documents that you have already filled out (but not signed) Form DS-4079, Questionnaire; Loss of United States Nationality; Attestations prior to signing them and taking the oath of renunciation.
Fee: Immediately after taking the oath of renunciation, you must pay the non-refundable current fee of US $450 for administrative processing of a request for a Certificate of Loss of Nationality. The fee is not waivable, nor is it refundable if your request for a Certificate of Loss of Nationality is denied.
Step 4: Receive the Certificate of Loss of Nationality if approved by the Department of State
The Department of State will review each request for a Certificate of Loss of Nationality to determine whether there is a legal basis to approve it. This step may take several months or more. The embassy, consulate, or office providing consular services may contact you for further information before the Department of State decides your case. The embassy, consulate, or office providing consular services will email you if and when your request has been approved. If your request is denied, the embassy, consulate, or office providing consular services will send you an email attaching a denial letter.
NOTE: STEPS 1-4 above outline the process for requesting a CLN based on taking an oath of renunciation before a U.S. diplomatic or consular officer abroad under Immigration and Nationality Act (INA) Section 349(a)(5), 8 USC 1481(a)(5). For information on the parallel process to request a Certificate of Loss of Nationality (CLN) on the basis of the commission of another potentially expatriating act under INA 349(a)(1)-(4), 8 USC 1481(a)(1)-(4), please contact your location for inquiries.
Fees (Prices in U.S. Dollars)
Non-refundable fee of $450 USD at the time of the appointment.
What the Fee Reduction Does Not Change
The $450 consular fee covers only the State Department’s administrative processing of the renunciation appointment. It has no effect on the U.S. tax consequences of renunciation, which are governed entirely by separate federal tax law.
A U.S. citizen who renounces citizenship in 2026 still faces the same IRS obligations as before the fee change. Form 8854, the Initial and Annual Expatriation Information Statement, must still be filed. The five-year tax compliance certification is still required. If the renouncing individual qualifies as a covered expatriate under the three IRS tests — net worth, average annual tax liability, and compliance certification — the Section 877A mark-to-market exit tax still applies in full.
The fee reduction makes the administrative step of renouncing less expensive. It does not reduce the tax cost.
Is the $450 Fee the Only Cost of Renouncing?
No. The consular fee is the smallest cost most people encounter. The substantive costs of renunciation depend entirely on the individual’s financial situation and filing history. For individuals who are covered expatriates, the Section 877A exit tax can represent a significant liability. For individuals with unfiled FBARs or unreported foreign accounts, FBAR penalties may apply separately.
Attorney fees for proper pre-renunciation planning, tax preparation for Form 8854, and any exit tax liability are the costs that vary significantly from person to person. The $450 appointment fee is the one cost that is the same for everyone.
When Did the Fee Change Take Effect?
The State Department updated its fee schedule in September 2026, reducing the U.S. citizenship renunciation fee from $2,350 to $450 effective immediately. The $2,350 fee had been in place since September 2014, when it was increased by more than 500 percent from the prior $450 level. In real terms, adjusted for inflation since 2014, the current $450 fee is equivalent to approximately $320 in 2014 dollars.
FBAR Penalties Explained: What Happens If You Don’t File?
Few basic U.S. tax compliance questions matter more to a U.S. citizen or green-card holder living abroad than what an unfiled FBAR can actually cost in penalties. Also, a green-card holder might not have any reporting requirements at all – given the law explained in the federal district court decisions originally appealed by the government in my 9th Circuit decision: Aroeste v. United States, Case No. 22-cv-00682-AJB-KSC.
What Are the Penalties for Not Filing an FBAR?
Failure to file an FBAR mayresult in a civil penalty if assessed by the government. The willful civil penalty is frankly more onerous than the criminal penalty that is maxed out by statute. The maximum civil penalty depends on whether the violation is determined to be non-willful or willful.
The statutory framework was initially set out by a federal district court in 2015, that also reviewed the FATCA laws, and it is worth reading the summary here:
A person who fails to file a required FBAR may be assessed a civil monetary penalty. 31 U.S.C. § 5321(a)(5)(A). The amount of the penalty is capped at $10,000 unless the failure was willful. See 5321(a)(5)(B)(i), (C). A willful failure to file increases the maximum penalty to $100,000 or half the value in the account at the time of the violation, whichever is greater. § 5321(a)(5)(C). In either case, whether to impose the penalty and the amount of the penalty are committed to the Secretary’s discretion. See § 5321(a)(5)(A) (“The Secretary of the Treasury may impose a civil money penalty[.]”)
Crawford v. U.S. Department of the Treasury (S.D. Ohio 2015 – Case No. 3:15-cv-00250)
The IRS internal revenue manual (4.26.16.4.1) summarizes how and why the IRS has purported authority to assess penalties for FBAR Title 31 violations as set forth below:
As of April 8th 2003, IRS was delegated the authority to assess and collect FBAR civil penalties. 31 C.F.R. § 103.56(g). The delegation includes the authority to investigate possible FBAR civil violations, provided in Treasury Directive No. 15-41 (Dec. 1, 1992), and the authority to assess and collect the penalties for violations of the reporting and recordkeeping requirements.
Was this delegation of authority from FinCEN to the IRS even valid as a matter of law? That questions has not been challenged yet in the courts.
When performing these FBAR functions, the IRS is not acting under Title 26 (the federal tax law) but, instead, is acting under the authority of Title 31 (the Bank Secrecy Act). Provisions of the Internal Revenue Code generally do not apply to FBARs and visa-versa. Does the IRS even have lawful authority to manage and assess these penalties – which previously were in the hands of the more obscure FinCEN.
What Is the Penalty for a Non-Willful FBAR Violation?
A non-willful FBAR violation may result in a civil penalty of up to $10,000 per violation. The Supreme Court has now held (after years of litigation) that, for non-willful violations, the penalty generally applies singularly – per report – rather than per account as the IRS argued for years. Bittner v. United States, 598 U.S. 85, 143 S. Ct. 713 (2023)
For years the government (IRS) read that $10,000 could be assessed for each account, and the Supreme Court finally resolved the question in 2023 against the government. The Ninth Circuit had ruled against the government inUnited States v. Boyd, 991 F.3d 1077 (9th Cir. 2021) and the Fifth Circuit (United States v. Bittner, 19 F.4th 734 (5th Cir. 2021)) overturned the federal district court in the eastern district of Texas in United States v. Bittner, No. 4:19-CV-415, 2020 WL 4200057 that had originally ruled in line with Boyd.
See an article I wrote on this issue along with two of my international tax colleagues at Chamberlain Hrdlicka: published as a Special Report in Tax Notes:
On February 28th, 2023, the Supreme Court of the United States (“SCOTUS”) resolved in Bittner that the applicable non-willful FBAR penalty is not measured by every foreign account of the individual as the Service had argued for years and as they put into their IRM. The author had the opportunity to draft as one of the co-authors of the ACTEC amicus brief that was filed in Bittner. After Bittner, the total maximum penalty per year is $10,000 for non-willful violations. A maximum penalty of $50,000 (x5 years) applied per the SCOTUS versus the IRS determined amount of US$2.7M+ multiplying each account by $10K.
“Best read, the BSA treats the failure to file a legally compliant report as one violation carrying a maximum penalty of $10,000, not a cascade of such penalties calculated on a per-account basis.” The ACTEC brief was cited by the majority opinion- “ We see evidence, too, that the point of these reports is to supply the government with information potentially relevant to various kinds of investigations, criminal and civil alike. But what we do not see is any indication that Congress sought to maximize penalties for every nonwillful mistake (whether a late filing, a transposed account number, or an out-of-date bank address). See Brief for American College of Trust and Estate Counsel as Amicus Curiae 5–7.”
What Is the Penalty (Civil) for a Willful FBAR Violation?
A willful FBAR violation may result in substantially higher penalties. The maximum penalty is generally based on the greater of a statutory amount or a percentage of the account balance.
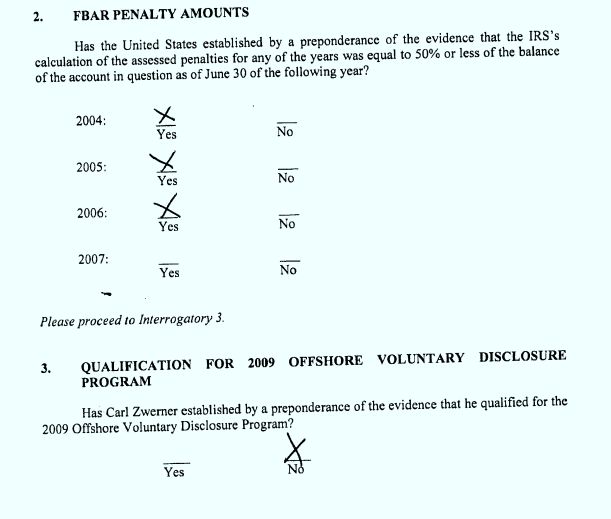
The government was on its face, very “successful” in the Zwerner case in convincing a jury they should render a verdict for 3 years of FBAR 50% willfulness penalties (150% of the account balance in total). The government tried to assert 4 years of willfulness penalties, which would have been 200% of the account balance; all under a civil penalty provision in the statute, that looks like a criminal penalty on its face and via its outcome.
In Zwerner, the taxpayer did come forward and disclose the unreported foreign accounts, and received a letter from the IRS CI on February 17, 2009, stating that ” . . . based upon the information provided a criminal investigation will not be initiated at this time. . . ” Nevertheless, the government pursued 50% civil willfulness penalty assessments for multiple years (4 years). The Tax Division of the Justice Department pursued this case through trial, incurring the time and costs of government resources, arguing Mr. Zwerner owed a total of $3,630,119.29 (on an account with a maximum value during the years at issue of apparently no more than US$1.69M) in their Motion for Summary Judgement.
In Count Six, Plaintiffs contend that the FBAR “Willfulness Penalty” is unconstitutional under the Excessive Fines Clause. Plaintiffs allege the Willfulness Penalty is designed to punish and is therefore subject to the Excessive Fines Clause. Plaintiffs further allege the Willfulness Penalty is grossly disproportionate to the gravity of the offense.
Can the IRS Penalize Each Foreign Account Separately?
Not for non-willful violations as explained above. The “jury is still out” regarding to what extent multiple years of 50% willfulness penalties may be assessed. The IRS has tempered their approach a bit over the last decade – particularly as of late, after losing a number of key FBAR cases going to trial.
Is the FBAR Penalty Mandatory?
No. The statute provides that the government may assess an FBAR penalty, giving the government discretion over whether, and in what amount, a penalty is imposed.
The distinction between what the statute permits and what it requires is easily missed, and it matters a great deal for individuals who have not filed FBARs. Especially for those residing outside the United States – including those individuals with green cards.
The relevant statutory provision is that “The Secretary of the Treasury may impose a civil money penalty on any person who violates, or causes any violation of, any provision of section 5314.” 31 U.S.C. Section 5321(a)(5)(B).
How Long Does the IRS Have to Assess an FBAR Penalty? – Six Years –
The IRS generally has six years to assess a civil FBAR penalty. This limitations period differs from the rules that apply to federal income tax returns.
The two bodies of law run on different time clocks.
The FBAR (the Foreign Bank Account Report) comes from a different law than the federal income tax. The income tax is from Title 26 of the U.S. Code. The FBAR comes from the Bank Secrecy Act, which is Title 31. These two laws are very different, with very different obligations and rights. One of the important differences is the time frame in which the government can assess penalties for not complying.
A statute of limitations is the time frame in which the government has to assess penalties for not complying with the law. For foreign accounts, these time periods are not the same under Title 31 (the Bank Secrecy Act) as they are under Title 26 (the income tax law). The gap between the two is what makes this area confusing.
No. When a U.S. citizen or LPRs residing overseas fails to file an income tax return, the time period for the IRS to make tax assessments never lapses. There is effectively no statute of limitations against the IRS in that situation. The clock to assess does not start until a return is filed.
Title 31, the Bank Secrecy Act, is different. It does have a time period that runs against the U.S. federal government, even if the FBAR was never filed. For civil assessments of penalties, that time period is 6 years. This important distinction helps drive strategic decisions of foreign account holders if they have failed to file FBARs.
An FBAR penalty is generally not collected through the IRS’s ordinary tax lien and levy procedures. Instead, the government is typically required to bring a civil action to collect an unpaid penalty. They also have “off-set” rights that can be invoked against other payment amounts owed to the taxpayer. See, Bureau of the Fiscal Service and their powers through the Treasury Offset Program (TOP).
Assessing a penalty and actually collecting it are separate problems for the government, particularly where the taxpayer and the assets are outside the United States.
The collection of the FBAR penalty is not as easily collected under the law, as is a tax claim. A Title 26 tax lien and levy claim against the taxpayer’s property cannot be used to collect an FBAR penalty. Instead, the government has rights of set-off and will typically be required to bring a judicial action in Court to enforce the penalty assessment. See, an early case, United States v. Williams, 489 F. App’x 655 (4th Cir. 2012), where the government sued to collect the 50% FBAR willfulness penalty.
The laws of many countries outside the U.S. often conclude that enforcing these FBAR penalties against a U.S. citizen or LPR, inside that person’s home country, violates the laws of that country. Canada is one example. Calgary based tax attorney Roy Berg has written on the question of whether the IRS can collect FBAR penalties under the Canada-US Treaty.
The “Revenue Rule” was a common law concept that generally prohibited the U.S. government from assisting in the collection of taxes of another country. Hence, the U.S. Treasury renegotiated the treaties with five countries (including Canada) that now have a specific treaty provision such as XXVI A above:
As a result of these cases and the Revenue Rule, the U.S. and Canada modified their income tax treaty to (at least in theory) to allow for the international enforcement of taxes. The U.S. now has five income treaties with “mutual assistance” provisions: Canada, Sweden, France, Denmark, and the Netherlands (with a clause in the newly negotiated, but yet to go into force, Swiss treaty).
In the Dewees case, we learned that the assistance in collection provision is not merely a theoretical tool that can be used in collecting taxes. The IRS was successful in a long running case with FBAR penalties and Title 26 penalties for failure to file IRS forms 5471 regarding the U.S. citizens Canadian companies. He lived in Canada. See, Dewees v. United States, 272 F. Supp. 3d 96 (D.D.C. 2017), which was subsequently affirmed by the D.C. Circuit Court of Appeals (Dewees v. United States, 767 F. App’x 4 (D.C. Cir. 2019)). The actions of both the Canadian (CRA) and U.S. governments (IRS and District Court Judge), made the provision effective. The US$120,000 penalty, that has nothing to do with any U.S. income taxes owed (nor FBAR penalty), was collected by the IRS; a penalty under 26 U.S.C. § 6038(b) for failure to file informational returns – .
Can an FBAR Violation Lead to Criminal Charges?
Yes, but not every FBAR violation is a criminal matter. Criminal liability generally requires proof of willful conduct and carries a burden of proof on the government – (beyond a reasonable doubt) – and always depends on the facts of the case.
Yes. A U.S. citizen or LPR living overseas could in theory become criminally liable for willfully not filing the FBAR form. Criminal liability carries different legal consequences than a civil penalty. These are not easy cases for the government – and hence they rarely have brought criminal FBAR cases for taxpayers residing overseas. It all depends upon the facts.
IRS Criminal Investigation (division) has been delegated the authority to investigate possible criminal violations of the Bank Secrecy Act. 31 C.F.R. §103.56(c)(2). This should not be taken lightly.
Yes, there are also statutes of limitations for criminal charges the government brings for FBAR violations. The law gets much more complex here, especially when the taxpayer is residing outside the U.S. In that situation, the time period can be tolled or suspended in favor of the government, which extends the window to bring charges. Jack Townsend (an amazing, now retired criminal tax defense lawyer who has contributed extensively to the tax law practice) has written on the statutes of limitations for FBAR noncompliance related to tax reporting. Jack is co-author of Tax Crimes – John (“Jack”) Townsend with my law partner the esteemed criminal tax defense lawyer Larry Campagna along with Steve Johnson, and Scott Schumacher.
U.S. citizens residing overseas clearly have FBAR filing requirements – if they meet the thresholds. The law is quite different for those with “green cards” residing predominantly overseas in a country with an income tax treaty with the U.S. Here, it gets a lot more complicated, but see my case of Aroeste v. United States, Case No. 22-cv-00682-AJB-KSC (2023) that was appealed to the Ninth Circuit by the government after they lost.
What Can We Learn from Real FBAR Penalty Cases?
Reported cases show that the outcome of an FBAR penalty dispute depends heavily on the facts. They also demonstrate that proposed penalties may be successfully challenged in appropriate cases.
One case makes the point better than any summary of the rules could.
This case was covered extensively by various tax journalists and followed by tax professionals around the world from the time it started until it concluded. I know, because I was the lead attorney representing the then 91 year old widow from Canada, dear Mrs. Margaret Jones. The pleadings in the case can be viewed here –Margaret J. Jones v. United States (2:19-cv-04950)
In my view, this case should have never ended up before the U.S. District Court. The IRS erred in making a determination of “willful blindness” against Mrs. Jones who was legally blind at her advanced age. They conceded Mrs. Jones had no actual knowledge of the reporting requirement. She was advised for more than two decades by a CPA, both she and her late husband (an immigrant from New Zealand). They both had accounts that were decades old from their respective countries – Canada and New Zealand. Held openly and directly for the majority of their lives.
Mrs. Jones did the right thing by going to the Streamlined Filing Procedure (the streamlined filing procedure) and correcting her errors on her tax returns. She was then selected by the IRS for audit (because of that filing) where she got a tax refund of over $20,000. For that effort, time and expense, the IRS turned around and slapped her with US$3.4M of “willful blindness” penalties regarding her accounts in Canada and New Zealand, most of which were her husband’s accounts. Her late husband served in World War II while living in New Zealand before moving to the U.K. then Canada (where he met Mrs. Jones) and then on to the U.S. They both had high school diplomas.
The case was set for a jury trial (on two occasions) but Judge Selna postponed it on both occasions due to the Corona-virus. Unfortunately, Mrs. Jones never had her day in Court where I believe a jury would have found that the government did not carry its burden against Mrs. Jones and her late husband. Not even a close call. Her facts were not nefarious, unlike most of the cases where sophisticated taxpayers have been hiding their assets from the IRS, such as in Swiss bank accounts.
After the government conceded the bulk of the case and it was dismissed just before Christmas of 2020, Mrs. Jones passed away shortly afterwards. May her Soul Rest in Peace.
The DOJ drives the bus (NOT the IRS) once the case falls into their hands.
A jury trial should always be considered in the right case, a good faith taxpayer case, as jurors will generally see and understand the big picture.
By contrast, in Zwerner the penalty amount apparently sustained by the jury has been reported as “. . . $2,241,809 on an offshore account that had an apparent high balance of $1,691,054. . . “
The author has spoken on defending Title 31 FBAR penalties at the University of San Diego School of Law – International Tax Institute, alongside Caroline D. Ciraolo, former Acting Assistant Attorney General of the Justice Department’s Tax Division, and Robert S. Horwitz; and many other panels and forums advising clients on these FBAR issues. Seek advice on FBAR issues if you have a filing requirement.
Aroeste v. United States: Frequently Asked Questions for Green Card Holders
In November 2023, the United States District Court for the Southern District of California ruled in favor of the taxpayer in Aroeste v. United States, Case No. 22-cv-00682-AJB-KSC. The government appealed to the Ninth Circuit and then conceded, making the ruling final. The case was litigated by Patrick W. Martin of Chamberlain Hrdlicka. The decision established that a long-term lawful permanent resident who filed Form W-8BEN and elected non-resident treatment under a U.S. income tax treaty is not automatically a covered expatriate subject to the Section 877A exit tax. The questions and answers below address the most common issues that arise for green card holders and their advisors in light of that ruling.
The U.S. tax law is complicated generally. It gets really complex when you renounce your United States citizenship or you cease to be a “lawful permanent resident” as that term is technically defined in the U.S. federal tax law. The comments in Tax-Expatriation.com are designed to help demystify some of this complexity.
Hence, posts addressing various FAQs – for those who have or “had” a “green card” – please see the following:
“Delinquent FBAR Filing Procedures”: The IRS Webpage Is Gone, but the Real Questions Remain
“Delinquent FBAR Filing Procedures”
There has been considerable commentary—and some concern—about the IRS’s removal, around the end of June 2026, of its longstanding webpage titled “Delinquent FBAR Filing Procedures.” The IRS originally created those procedures in 2014.
The disappearance of the webpage is noteworthy. But it may not be nearly as important as some commentators suggest.
TIGTA report: $157 Billion of Potentially Unreported Foreign Accounts?
As the TIGTA reports: “Foreign financial institutions (FFI) are required to File IRS Form 8966, FATCA Report, to report information about financial accounts in which U.S. taxpayers hold certain ‘ownership interests.'”
TIGTA noted that foreign financial institutions report U.S.-owned financial accounts to the IRS on Form 8966, FATCA Report, while U.S. taxpayers separately report specified foreign financial assets on Form 8938. The disparity identified by TIGTA was enormous.
For 2017 and 2018, taxpayers reported (on their IRS Form 8938) approximately $6.6 billion and $15.9 billion, respectively, while foreign financial institutions reported (on IRS Form 8966) approximately $106.8 billion and $173.0 billion.
From these figures, TIGTA concluded that the data indicated potential unreported or underreported foreign bank-account values of approximately $157 billion.
That conclusion deserves considerable skepticism. Among other questions: how many of those reported foreign assets belong to lawful permanent residents—“green card” holders—who actually reside overseas and may qualify as residents of a treaty country under an applicable U.S. income tax treaty?
That was precisely the type of residency issue presented in my case of Aroeste v. United States, Case No. 22-cv-00682-AJB-KSC (S.D. Cal. 2023).
Account holders and their advisors nevertheless have good reason to take FBAR exposure seriously. Federal courts have increasingly accepted a relatively low threshold for establishing a “willful” FBAR violation. The government generally needs to prove its civil FBAR case only by a preponderance of the evidence, and courts have repeatedly held that willfulness can include recklessness or willful blindness, rather than requiring proof that the taxpayer deliberately intended to violate the FBAR statute.
See, among others, United States v. Reyes (2d Cir. 2026); Bedrosian (3d Cir.); Horowitz (4th Cir.); Kelly (6th Cir.); Rum and Schwarzbaum (11th Cir.); and Norman and Kimble (Federal Circuit).
That is where the real concern lies, not simply in the disappearance of an IRS webpage.
The IRS Removed the Webpage—Not Its Internal Guidance in the IRM (the IRS’ “Bible”)
The IRS removed the public-facing “Delinquent FBAR Filing Procedures” webpage, but the same guidance remains in the Internal Revenue Manual (IRM) to still encourage late filed FBAR filings. The same language is found in the IRM, which is the most important since revenue agents and managers “are responsible for adhering to the content of this IRM”. See, IRM 4.26.16.1(i).
The IRM continues to provide that an FBAR penalty should not be imposed when:
the violation was due to reasonable cause; and
accurate delinquent or amended FBARs are filed to correct the prior violations.
The critical point is that filing a delinquent FBAR does not itself establish reasonable cause or eliminate a potential penalty, but notification of the government is required if you go down this path.
IRM 4.26.16.3.11 continues to describe the delinquent FBAR filing procedures. Among other things, it instructs taxpayers to file delinquent FBARs electronically, using the instructions applicable to the year being reported, and to provide the reason why the FBAR was filed late.
Most importantly, the IRM states that a penalty will not be asserted for an account “if it is determined” that:
the failure was not willful;
the failure was due to reasonable cause; and
the account was properly reported on the delinquent FBAR.
The words “if it is determined” are crucial. Who makes that determination? See my case of Jones v. United States, No. 19-CV-4950 (C.D. Cal. 2020), as a cautionary tale.
Ultimately, the IRS makes this determination which starts the government machinery running. Its not the account holder, the person with signature authority, or the taxpayer’s advisor; no matter how convinced they are of their reasonable cause and their facts.
The More Important Question (Implied Above): Should You File a Late FBAR at All?
This is the question that deserves considerably more attention.
Whether someone should file a delinquent FBAR depends entirely upon the person’s particular facts and circumstances. Filing late is not automatically the safest course.
One of the most important considerations is the six-year FBAR statute of limitations under 31 U.S.C. § 5321(b)(1). That limitation period is fundamentally different from certain Title 26 international information-reporting rules, where the assessment period can remain open under IRC § 6501(c)(8).
Accordingly, before filing a delinquent FBAR, an account holder should understand at least two competing questions:
What are the consequences of filing late?
What are the consequences of not filing at all?
Those questions cannot responsibly be answered without examining the particular years involved, when the six-year limitations period expires, the underlying income-tax filings, what the taxpayer knew, all of the surrounding facts, what advice was received, and whether the government might characterize the conduct as willful or reckless.
Bittner Changed the Economics of FBAR Enforcement
The Supreme Court’s decision in Bittner v. United States, 598 U.S. 85 (2023), significantly changed the strategic landscape.
The Court held that the non-willful FBAR penalty applies on a per-report, rather than per-account, basis. That substantially reduced the government’s potential penalties in all non-willful cases involving numerous foreign accounts.
As a practical matter, Bittner also changed the economics of FBAR enforcement. I had the privilege of working on the ACTEC amicus brief filed in Bittner – which was cited in both the majority opinion by Justice Gorsuch and the dissent by Justice Barrett – See Brief for American College of Trust and Estate Counsel as Amicus Curiae 5–7.
In my view, the IRS now has a greater incentive to focus its enforcement resources on cases in which it believes it can establish willfulness through reckless disregard or willful blindness, thereby potentially supporting the much larger willful FBAR penalty.
These Are the IRS’s Own Rules
It is also important to distinguish the statute from the IRS’s administrative procedures.
I sometimes refer to these as the IRS’s “Monopoly rules.” They are the government’s administrative rules for handling delinquent FBARs; they are not themselves statutory safe harbors enacted by Congress.
That distinction matters.
The IRM says a penalty will not be asserted “if it is determined” that reasonable cause exists and the other requirements are satisfied. But “reasonable cause” is not defined in the FBAR statute itself, Title 31.
Instead, courts and the government have borrowed concepts developed under Title 26, including the Supreme Court’s familiar “ordinary business care and prudence” standard. See United States v. Boyle, 469 U.S. 241 (1985); see also Moore v. United States, No. C13-2063RAJ (W.D. Wash. 2015), and United States v. Ott, No. 2:18-cv-12174 (E.D. Mich. 2019).
Filing Late Does Not Erase the Original Violation
This point is sometimes overlooked.
Once an FBAR filing deadline has passed without the required report being filed, subsequently filing the FBAR does not somehow erase the historical failure.
The water has already passed under the bridge.
A delinquent filing may become highly relevant to reasonable cause, mitigation, cooperation, and the government’s ultimate enforcement decision. But it does not make the original failure disappear.
Moore provides an important cautionary example. An even more dramatic example arose in Jones v. United States, No. 19-CV-4950 (C.D. Cal. 2020), a case I represented as we prepared for a jury trial during the COVID period.
Mrs. Jones, an elderly widow, and her late husband’s estate challenged approximately $3.4 million in willful FBAR penalties. She had affirmatively disclosed her late filings to the IRS through the streamlined process after filing the delinquent FBARs. The government nevertheless pursued a willfulness theory based substantially on willful blindness.
The government argued willful blindness and Mrs. Jones (90+ years of age), ironically, was legally blind by the time the case was set to go to trial.
That is one reason the facts surrounding preparation and signing of the income-tax return can become just as important as the FBAR itself.
The lesson is important: coming forward and filing late does not itself immunize an account holder from an FBAR penalty examination. It does not mean a revenue agent will come to the right result based upon the facts of your case. It can be a bit like the lottery.
“Reasonable Cause” May Not Mean What You Think
What does it take for the IRS to conclude that reasonable cause does not exist?
Sometimes, not much.
A simple “mistake” or “oversight” does not necessarily constitute reasonable cause. The government generally looks for evidence that the person exercised ordinary business care and prudence but nevertheless could not comply.
Death, serious illness, destruction of records, fire, or natural disaster can support reasonable cause under appropriate circumstances. But even those facts do not automatically establish it.
Likewise, ignorance of the FBAR requirement ordinarily does not automatically establish reasonable cause. Even reliance on professional tax advice may be insufficient—particularly where the government contends that the advisor lacked appropriate international-tax expertise or that the taxpayer failed to provide the advisor with the relevant information.
The disappearance of the IRS webpage titled “Delinquent FBAR Filing Procedures” should not itself drive a taxpayer’s decision.
The underlying IRS guidance remains in the Internal Revenue Manual.
The much more important question is whether filing a delinquent FBAR is actually the appropriate strategy for the particular individual and the particular years involved.
That requires understanding the six-year FBAR statute of limitations, the taxpayer’s underlying filing history, the reason the FBAR was not timely filed, what the taxpayer knew, what professional advice was received, the information appearing on Schedule B and other returns, and the possibility that the government could characterize the conduct as reckless or willful.
Once a delinquent FBAR is filed, the filing—and the taxpayer’s explanation for filing late—cannot simply be taken back.
So be thoughtful when someone recommends entering the “Delinquent FBAR Filing Procedures” for a low low fee of just US$**99.99.
Understand why you are filing, what you are saying to the government, what years remain open, and what consequences may follow.
Dive in with your eyes wide open – and make sure you can see the bottom before you jump.
IRS Removes Practice Unit from their Website – titled “Determining Tax Residency Status of Lawful Permanent Residents” – Post-Aroeste
The decision in Aroeste v. United States, continues to affect how U.S. tax treaty rules apply to green card holders. In Aroeste, the federal district court rejected important IRS-DOJ arguments concerning when a lawful permanent resident is not treated as a resident of the United States under an income tax treaty. I refer to the broader consequences of the case as the Aroeste Effect, which rears its head in proposed Treasury Regulations to be discussed for another day.
For years, the IRS Large Business and International Division (LB&I) published a Practice Unit titled Determining Tax Residency Status of Lawful Permanent Residents. Issued in 2013 and updated in 2014, it was used to help IRS personnel determine the U.S. tax residency of green card holders—the very subject litigated in Aroeste. That Practice Unit has now been removed from the IRS website.
The removal is notable because the IRS continues to publish other related international tax Practice Units. For example, its 2018 Practice Unit, remains available: Determining an Individual’s Residency for Treaty Purposes PDF This 2018 Practice Unit has not been updated to address Aroeste. Importantly, however, it does not repeat the government’s argument in Aroeste that a taxpayer can lose or waive treaty benefits by failing to timely “take” a treaty position. The district court rejected the government’s position on that issue.
The IRS has not publicly explained why it removed the Practice Unit specifically addressing lawful permanent residents. Nevertheless, its disappearance after Aroeste is significant. For green card holders living outside the United States, the practical issue is straightforward: holding a green card does not necessarily mean the individual must always be a “United States person” – i.e., a U.S. tax resident. An applicable tax treaty can change that result.
The intricacies of the law can be complex, depending upon the facts of each person. The IRS’s removal of its own Practice Unit on this subject is another noteworthy example of the Aroeste Effect.
Missed FBAR Filing? Penalties, Options, and What to Do Next (2026)
A missed FBAR filing can become a serious tax problem if the IRS views the violation as willful. After Reyes, reckless conduct may be enough for the government to argue willfulness. This guide explains how to evaluate your options, respond to the IRS, and protect your position from the start.
What is an FBAR?
The Foreign Bank Account Report (FBAR), officially known as FinCEN Form 114, is an annual reporting form used to report certain foreign financial accounts to the U.S. government. If you are a U.S. citizen or a green card holder and the combined value of your accounts at banks outside the United States exceeded $10,000 at any point during the year, the law generally requires you to tell the U.S. government about those accounts every year on this form. The FBAR goes to FinCEN, a bureau of the U. The FBAR is due April 15, with an automatic extension to October 15 that you do not have to request.S. Treasury Department, and the IRS is the agency that enforces it.
Who needs to file FBAR?
The filing requirement generally applies even if:
You are a United States citizen and live outside of the United States.
The accounts are in the country where you live.
The accounts earn no income.
You are a green card holder, even those who have not lived in the United States for years — unless your green card status has been formally terminated or a tax treaty position properly applies (this guide includes a legal analysis on this topic discussed below).
What are the penalties for not reporting FBAR?
It depends on whether your failure was “non-willful” or “willful.” Before diving into the details, this chart summarizes the civil and criminal FBAR penalties:
Type of violation
Civil penalty
Criminal penalty
Non-willful An honest mistake or genuine ignorance
Up to roughly $16,500 per unfiled form. Under Bittner v. United States, this is per form, not per account.
None
Willful
The greater of roughly $165,000 or half of the account balance, per account, per year.
Fines up to $250,000 and five years in prison per violation. Prosecution is extremely rare.
Willful, combined with other crimes
As above.
More than the amounts above.
Unpaid assessments
Interest, plus a mandatory 6% late-payment charge.
—
Civil and criminal FBAR penalties. Dollar figures are inflation-adjusted and change annually.
A warning: if any part of your situation could be called “willful,” be careful who you talk to first.
If there is any chance the government could paint your situation as deliberate or careless, the order of your conversations matters before anything else does. This is because only what you tell a lawyer is protected. Anything you tell an accountant can become the government’s evidence. See more in the section “Is there an accountant-client privilege in federal court?” below.
What is a non-willful FBAR violation?
A non-willful violation – an “honest mistake or genuine ignorance”— carries a civil penalty (31 U.S.C. § 5321) of up to roughly $16,500 (inflation-adjusted) per unfiled form. The law is complex about what the courts have said is non-willful. Please see the FBAR detailed technical report. The Supreme Court held in Bittner v. United States1 that it is per form, not per account — a taxpayer victory over the government’s per-account computation, urged in the friend-of-the-court brief filed by the American College of Trust and Estate Counsel (ACTEC) and co-authored by attorney Patrick W. Martin in his role as a Fellow of ACTEC.
What is a willful FBAR violation?
A willful violation is different in kind: the civil penalty is the greater of roughly $165,000 or half of the account balance, per account, per year, and truly willful cases can be prosecuted criminally (although extremely rare), with fines up to $250,000 and five years in prison per violation (more if combined with other crimes). Interest and a mandatory 6% late-payment charge apply to unpaid assessments. Because “willful” penalties can consume an entire account — and more — the fight in most cases is over that one word as was the case of Mrs. Jones.
Is my accountant protected by privilege?
No. Conversations with an accountant, bookkeeper, enrolled agent, tax-return preparer, or financial advisor are not protected in a case like this. Accountants have only a limited privilege under IRC § 7525, which does not apply in criminal matters. For decades, courts have allowed the government to demand those advisors’ files and put them on the witness stand.
On the other hand, conversations with a lawyer are protected by the attorney-client privilege: the government generally cannot force your lawyer to reveal them. If your case could become serious, talking to the wrong professional first may unintentionally create evidence the government can later use against you.
Can I still use the “I didn’t know” defense?
This depends on your specific facts. In January 2026, in United States v. Reyes2, a federal appeals court in New York joined nearly every other appeals court in holding that “willful” includes reckless conduct. Applying the Supreme Court’s standard in Safeco Insurance Co. v. Burr, the question is no longer just what you actually knew; it is what a reasonable person in your shoes should have known.
What counts as reckless disregard?
The government may argue you were reckless even if you sincerely believed you had no obligation, in situations such as these:
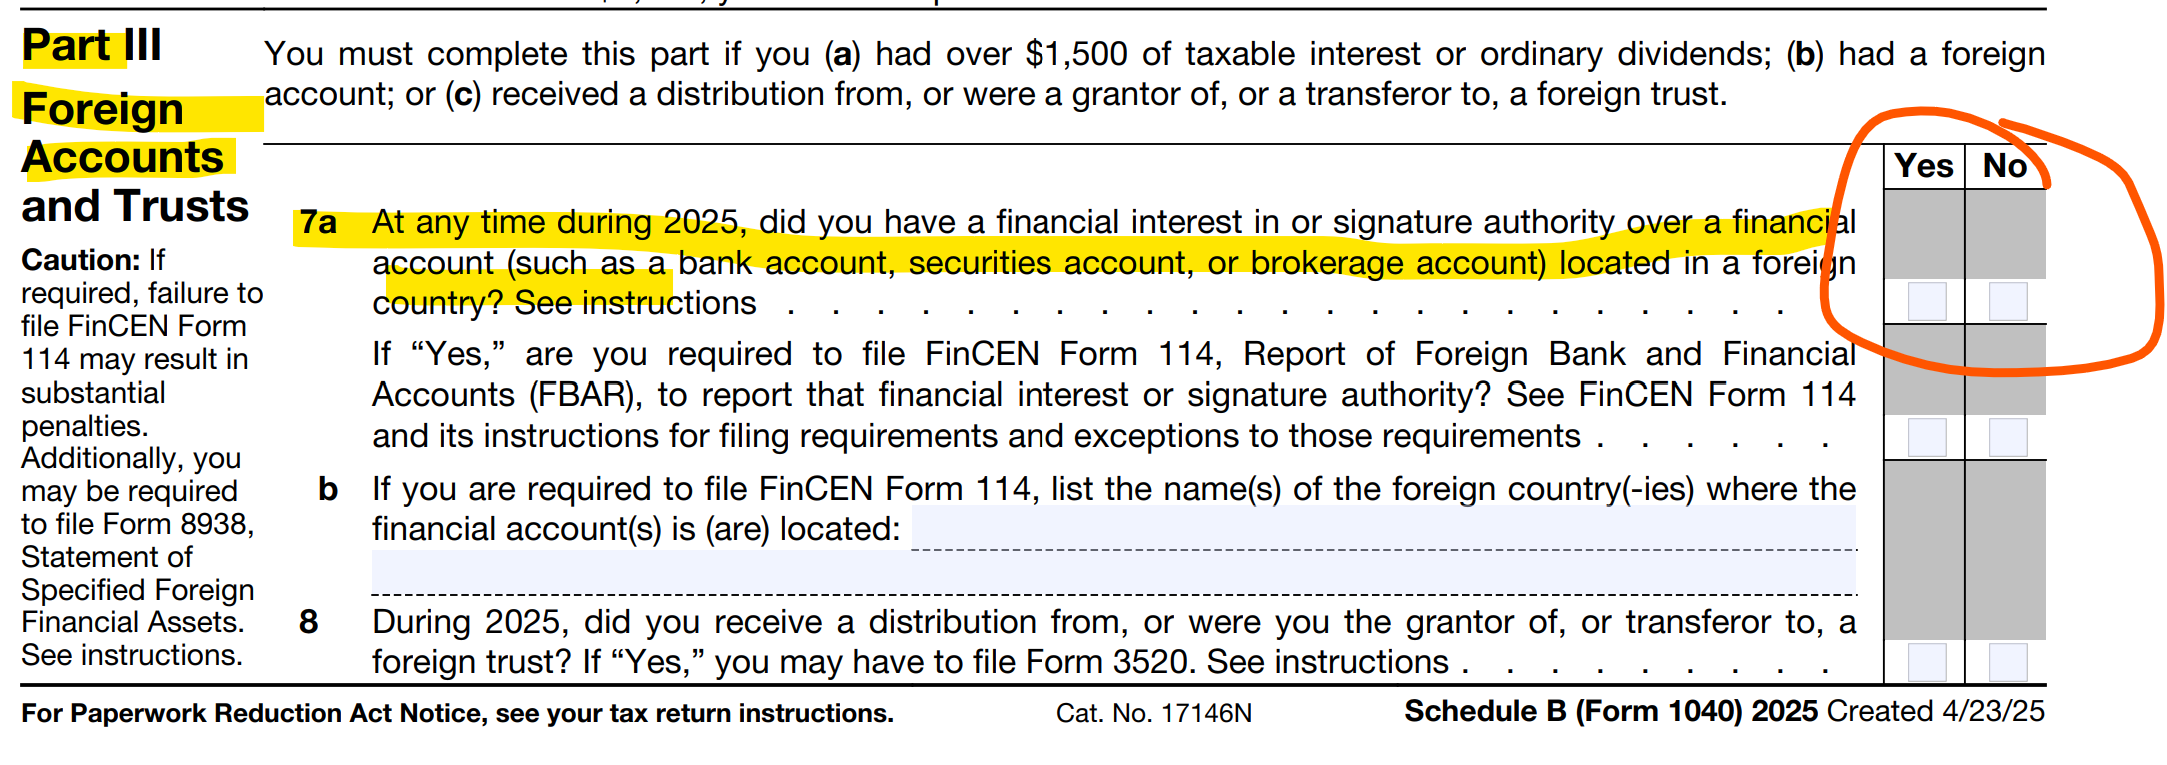
Your tax return asked about foreign accounts and you checked “No.”
Your preparer asked and you didn’t mention the accounts.
Your foreign bank held your mail, so nothing arrived in the U.S.
Margaret J. Jones v. United States: willful penalties after a voluntary disclosure
This is not a new government tactic that arrived with Reyes. Years earlier, in Margaret J. Jones v. United States3 — a case litigated by attorney Patrick W. Martin as principal lawyer — the IRS examiner pursued more than $1.5 million in willful penalties against Mrs. Jones (plus nearly $1.9 million against a related estate) on a “willfully blind” theory. The penalty was more than $3.4 million in total, even though the account holder had come forward voluntarily and IRS colleagues had recommended allowing an amended submission.
Whether your facts look “honestly ignorant” or “reckless” is a judgment call — one you should reach with a lawyer, in private, under privilege, not by narrating everything to an accountant, financial advisor, enrolled agent or tax return preparer, whose notes the government can later legally access and read.
Does the IRS have to give me a jury trial before assessing FBAR penalties?
In September 2025, United States v. Sagoo4 threw out more than $1 million in willful FBAR penalties because the IRS investigated the taxpayer, determined she was liable, and assessed the penalties itself— acting, in the court’s words, as “prosecutor, jury, and judge”—without a jury trial. The court relied on the Supreme Court’s 2024 decision in SEC v. Jarkesy, which held that the SEC could not impose civil penalties in-house without a jury.
If that ruling holds up on appeal, the government may have to persuade a jury before finalizing large willful penalties. That is potentially good news for taxpayers, but tax payers should still be cautious. Other courts have reached the opposite conclusion, so do not count on Sagoo protecting you. It is still important to understand what a jury trial actually means in practice.
What does a jury trial actually mean in practice?
One of the first willful FBAR penalty cases fully prepared to be tried to a federal jury was Margaret J. Jones v. United States, in which attorney Patrick W. Martin, the author, served as principal lawyer. The case was litigated to the eve of the scheduled jury trial, at which point the government conceded millions of dollars in FBAR penalties it had originally assessed.
But a jury trial is not necessarily the advantage many taxpayers imagine. If your case goes to a jury, everything you told your accountant, bookkeeper, and financial advisor can be admitted as evidence at trial. Only what you told your lawyer stays out — which is why trial-ready cases are built under privilege from the first conversation. Tax litigation through a trial can become very expensive.
Does FBAR apply to green card holders?
Almost certainly yes, and it complicates the situation. Holding a green card generally makes you a “U.S. person” for FBAR purposes, even if you live abroad full-time and you no longer travel to the United States.
However, that is not always the case. If you have formally abandoned your green card by filing Form I-407 (which carries its own exit-tax considerations), or if a tax treaty’s residency tie-breaker treats you as a resident of another country, different rules may apply. Whether a treaty position applies to you is a genuine legal question, as illustrated by Patrick W. Martin’s case, Aroeste v. United States.
I’m a green card holder. Can a tax treaty protect me from FBAR filing requirements?
Yes, in some circumstances. However, this issue is highly fact-specific, and the answer is not as simple as treating all green card holders the same as U.S. citizens. Many “expat tax” services use that shortcut, which can result in unnecessary filings, missed reporting obligations, or unexpected penalties.
This is an area where careful legal analysis matters. Patrick W. Martin litigated Aroeste v. United States5 , the leading case on this issue, and provides an in-depth analysis of its implications for green card holders here. For the broader set of issues facing green card holders abroad, see his series on the most important questions for lawful permanent residents.
Should I use a tax attorney or a CPA for an FBAR problem?
It depends on how your facts look:
If your facts are clean: you reported all your income, you simply never heard of the form, nothing looks like concealment, and you acted in good faith— an accountant can often handle a straightforward catch-up filing.
If there is any realistic possibility your facts could be portrayed as willful: a “No” on Schedule B, unreported income, accounts you never mentioned to your preparer, hold-mail service, large balances — see a licensed tax attorney before discussing details with any non-lawyer.
There are two reasons. First, only the attorney conversation is privileged.
Second, if accounting work is needed, your attorney can hire the accountant under what is called a Kovel arrangement (sometimes called a Kovel letter), which brings the accountant’s work inside the attorney’s privilege. Be wary if a lawyer tells you that you do not need a Kovel arrangement and he or she will prepare the tax returns and forms themselves to submit to the IRS. That protection only works going forward, as no lawyer can retroactively protect what you already told your CPA or bookkeeper, or financial advisor or enrolled agent, which is exactly why the order of conversations matters.
Which FBAR compliance procedure applies to me?
Three main paths exist today:
Path
When it applies
Delinquent FBAR Submission Procedures
If you reported all your income and only missed the forms, the Delinquent FBAR Submission Procedures let you file late FBARs with an explanation, typically with no penalty.
Streamlined Filing Compliance Procedures
If you also missed income but your conduct was non-willful, the Streamlined Filing Compliance Procedures let you file three years of returns and six years of FBARs with reduced or no penalties. You must certify on Form 14653, under penalty of perjury, that you were non-willful (see section “Why does my non-willfulness certification matter?” below).
IRS Voluntary Disclosure Practice
If your conduct may have been willful, the IRS Voluntary Disclosure Practice is designed for taxpayers who need to disclose that conduct and seek protection from criminal prosecution.
Why does my non-willfulness certification matter?
The Streamlined Filing Compliance Procedures are available only to taxpayers whose failure to report foreign financial assets or income was non-willful. The IRS describes these procedures as applying to taxpayers who “mistakenly failed to report foreign financial assets or pay taxes on those assets.”6 To use the program, you must certify under penalty of perjury that your conduct was non-willful. That certification is not just a filing requirement—it is a legal judgment about your knowledge, intent, and the facts surrounding your reporting failures. If the IRS later disagrees, the consequences can be significant.
What if the IRS disagrees with my non-willfulness certification?
If the IRS determines that your conduct was actually willful, it can challenge your eligibility for streamlined treatment and pursue willful FBAR penalties. This happened in Margaret J. Jones v. United States — litigated by attorney Patrick W. Martin as her principal lawyer.
After Mrs. Jones made a Streamlined disclosure, the IRS argued that she had been “willfully blind” and assessed more than $3.4 million in willful penalties against her and a related estate. The IRS took that position despite internal recommendations supporting an amended submission and a dispute over whether the estate could use Streamlined procedures in the first place.
The case was litigated to the eve of a federal jury trial before the government conceded millions of dollars of the assessed penalties—showing why these cases often require experienced legal advocacy, not just tax preparation. The IRS has also discussed modifying or ending the Streamlined program, so the options available today may not last forever.
Is doing nothing ever the right option?
This depends upon all of your facts and the applicable law, but sometimes your best option may be to do nothing! For example, a good faith failure to report gifts or inheritances from nonresidents must generally be reported on IRS Form 3520. However, the failure to do so (with good facts) might simply be an administrative problem that ultimately resolves itself with the running of the statute of limitations period against the IRS.
A late filing can create new problems
Compare that to what happened to Mr. Krzysztof Wrzesinski7 . Mr. Wrzesinski relied on an advisor who told him he did not need to report a gift from his Polish mother, who had won a Polish lottery. After a second advisor later recommended filing a late Form 3520, the IRS pursued penalties and the case continued until the eve of trial over the penalty amount.
What if the IRS has already contacted me?
That changes the stakes significantly. You may no longer qualify for the Streamlined program, and statements you make to the IRS or to non-attorney advisors (CPA, tax return preparer, enrolled agent, financial advisor, family member, etc.) may later be used against you. If you have potentially problematic facts, do not “explain things” to the IRS revenue agent or debrief your tax return preparer before speaking with a tax attorney.
What happens if I file a false or incomplete form?
Never file a false or incomplete form in the hope that it will make the problem go away. The opposite can happen. A return that omits foreign income, a perjured non-willfulness certification, or an FBAR that deliberately omits accounts can turn a civil penalty issue into potential criminal liability.
Why FBAR problems often require a tax attorney early
The law is moving in both directions at once:
Reyes made it easier for the government to call you willful.
Sagoo may eventually make it harder for the government to collect (although hiring a lawyer to defend you in a judicial proceeding can get expensive quickly).
The compliance programs that reduce or eliminate penalties that are currently available should be seriously considered depending upon your facts.
“I didn’t know” as a legal position can typically be harder to sustain.
You should consider coming forward before the government finds you, if it is in your best interest.
You should make that decision about how to come forward (or not) with a licensed attorney.
Treat the attorney-client privilege as what it is in these cases: not a formality, but the difference between analyzing your worst facts in private versus handing these facts and documents over to the other side (the government) in the event of an audit or further dispute.
Sources
Bittner v. United States, 598 U.S. 85 (2023). Amicus brief filed by the American College of Trust and Estate Counsel (ACTEC), co-authored by Patrick W. Martin as a Fellow of ACTEC. ↩︎
Jones v. United States (C.D. Cal. May 11, 2020). Willful penalties of $751,685 (2011) and $770,255 (2012) were assessed against Mrs. Jones, and $1,890,074 against a related estate. Patrick W. Martin served as principal lawyer. ↩︎
United States v. Sagoo (N.D. Tex. Sept. 19, 2025). The IRS had assessed $1,020,922.50 in willful FBAR penalties. The court relied on SEC v. Jarkesy, 603 U.S. 109 (2024). ↩︎
A U.S. Immigration Officer Stops You at at the Airport – @ the Point of Entry (Demands your Green Card be Turned Over))
Being stopped, searched, interrogated or simply questioned by U.S. federal government agents can be intimidating. Especially, if you do not know your legal rights.
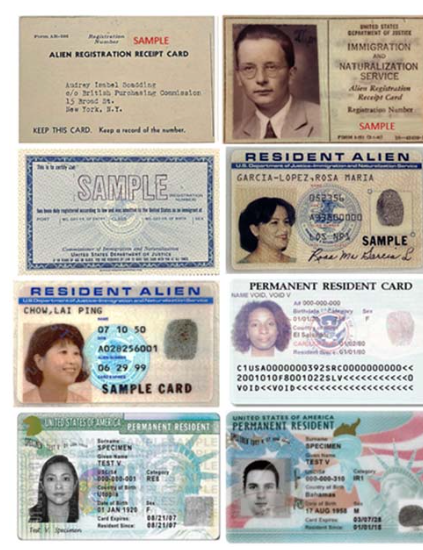
It can be more intimidating on your arrival to the U.S. airport, if the CBP officer (U.S. Customs and Border Protection) demands that you physically “return voluntarily” your green card. The consequences they tell you will be immediate deportation from the U.S.
Removal from the U.S. – is it voluntary or not, under these circumstances?
What are the U.S. federal tax consequences if you “return voluntarily” your green card?
What if the CBP officer pulls out Forms W-8s you previously signed with your foreign financial institution and presents them to you in the airport and asks the following questions:
Why did you certify “under penalty of perjury” you were not a United States person on your foreign bank produced documents (you received in France, Germany, the U.K., Canada, Mexico, Japan, Indonesia, Australia — or any other foreign country)?
The officer then asks for all of the envelopes and papers in your luggage and opens the letters and files in your possession – See, the U.S. Supreme Court decision United States v. Ramsey, 431 U.S. 606 (1977).
Tax Problems that Turn Serious – can Cause a Green Card Holder to become a “Covered Expatriate”
In Kawashima v. Holder (565 U.S. 478 (2012), the United States Supreme Court held that certain tax offenses committed by lawful permanent residents constitute crimes involving “fraud or deceit” for purposes of the Immigration and Nationality Act (“INA”). Specifically, the Court concluded that lawful permanent residents (a husband and wife from Japan) who were convicted of filing false tax returns resulting in a tax loss exceeding $10,000 had been convicted of an “aggravated felony” within the meaning of the INA.
As a consequence, a conviction for such an aggravated felony renders a lawful permanent resident removable (deportable) from the United States under the immigration laws. Importantly, however, the criminal conviction itself does not automatically terminate lawful permanent resident status. Rather, it provides the legal basis for the Department of Homeland Security to initiate removal proceedings, after which an Immigration Judge may enter a final order of removal.
Once a final order of removal becomes effective, the individual’s lawful permanent resident status is considered to have been revoked. For U.S. federal income tax purposes, this generally results in the termination of lawful permanent resident status under 26 U.S.C. § 7701(b)(6)(B), which provides that an individual ceases to be a lawful permanent resident when “such status has been revoked or has been administratively or judicially determined to have been abandoned.” Accordingly, following a final order of removal, the individual is no longer treated as a lawful permanent resident for purposes of the tax law as summarized below:
Stage
Legal Effect
1. Criminal conviction (including guilty plea)
If the offense qualifies as an “aggravated felony” under INA §101(a)(43), the individual becomes deportable under 8 U.S.C. §1227(a)(2)(A)(iii). A guilty plea counts as a conviction for immigration purposes if the statutory definition of “conviction” is satisfied.
2. DHS initiates removal proceedings
DHS serves a Notice to Appear (NTA) charging removability before an Immigration Judge under 8 U.S.C. §1229a.
3. Immigration Judge determines removability
DHS bears the burden of proving deportability by clear and convincing evidence, typically through the certified judgment of conviction.
4. Final order of removal
If removability is sustained and no relief is available, the Immigration Judge orders removal. After appeals are exhausted (or waived), the removal order becomes final, and the person’s LPR status ends.
The 2012 case involved Akio and Fusako Kawashima, Japanese citizens who had been lawful permanent residents since 1984. Mr. Kawashima pleaded guilty to willfully filing a false tax return under 26 U.S.C. § 7206(1), while Mrs. Kawashima pleaded guilty to aiding and assisting in the preparation of a false tax return under 26 U.S.C. § 7206(2). The immigration judge issued the order of removal. The Board of Immigration Appeals affirmed. Holding that convictions under 26 U. S. C. §§7206(1) and (2) in which the Government’s revenue loss exceeds $10,000 constituted aggravated felonies, the Ninth Circuit affirmed and ultimately so too did the SCOTUS in this decision.
The Supreme Court concluded that these tax offenses necessarily involve fraud or deceit and, because the tax loss exceeded the statutory $10,000 threshold, they constituted aggravated felonies under immigration law. The Supreme Court of the U.S. therefore upheld the government’s order (which had been upheld through the Ninth Circuit Court of Appeals) removing the Kawashimas to Japan.
This of course is important for U.S. “expatriation tax” purposes, since the “lawful permanent resident” status for tax purposes will necessarily terminate upon the final order of removal. Not before. Once LPR status terminates, the individuals will become covered expatriates, if they meet the time period under the statute to become “long term residents” as was the case for Mr. and Mrs. Kawashima and meet either of the three tests: the tax liability, net asset and certifications of compliance with the federal tax laws. See, Why a “long-term” LPR can NEVER avoid “Covered Expatriate” status under IRC Section 877A(g)(1)(B) if Asset or Tax Liability Test is Satisfied!
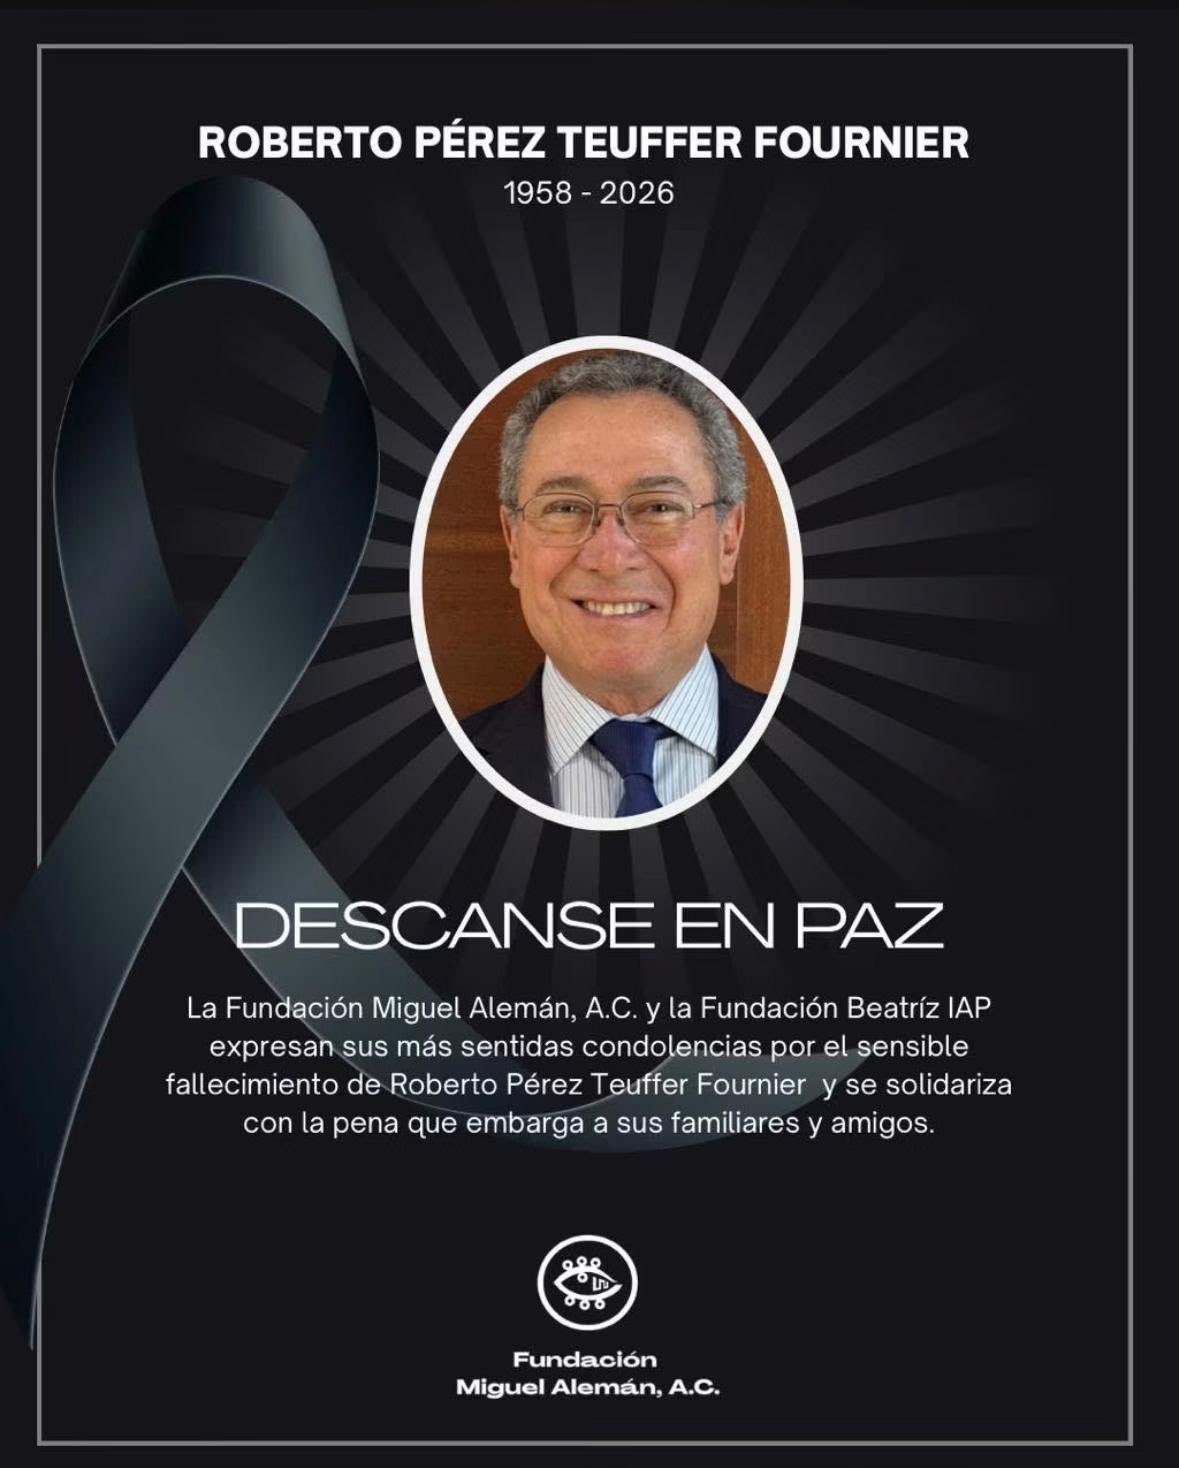
Rest in Peace – Don Roberto Perez Teuffer Fournier – a dear friend and colleague
Its with a heavy heart that I share the news that Don Roberto Perez Teuffer Fournier passed away unexpectedly this 28th of July 2026. He had a fascinating tax career and a wonderful dear family.
Roberto also was the Mexico law director of the ITAM-University of San Diego School of Law, executive international tax program that I have been involved with as an adjunct law professor and the U.S. law director. He also run the ITAM executive program on M&A.
US Exit Tax (Expatriation Tax): The Basic 2026 Guide
What is the U.S. “exit tax”?
The U.S. has a special federal tax you may owe if you renounce U.S. citizenship or end your status as a “long-term resident”. The rules for “green card” holders are particularly complex and nuanced, especially considering the federal district court case of Aroeste vs. the United States. This expatriation tax generally applies if you are considered a covered expatriate under the law, which is a technical category for specific taxpayers. Meeting any one of three tests typically puts you in that category. The next section further explains the three tests.
The law uses a deemed sale (a worldwide fictional sale for tax law purposes) rule to calculate the tax. This rule treats your global property as if you sold it for its market value the day before you cease to be a ‘United States person”. As a covered expatriate, you are typically required to pay income tax on the gain from the deemed sale. This is what the law calls the mark-to-market tax. For 2026, $910,000 of the gain is excluded from tax.
You are typically required to pay the U.S. exit tax as a covered expatriate when you renounce U.S. citizenship or end your status as a long-term resident if you hold a green card. Here is where it gets complicated under the law for green card holders. Meeting any one of three specific financial and compliance tests classifies you as a covered expatriate.
The three tests are:
Net worth test — your total net assets are worth $2 million or more on the day before you become a covered expatriate.
Tax liability test — your average annual net income tax liability for the five tax years ending before your exit date was more than $211,000. This amount is adjusted annually for inflation, and its calculation can be complicated.
Certification test — you fail to certify under penalty of perjury that you have complied with all federal tax laws for the preceding five years. This is typically the most important requirement, and often individuals fail this test when complying with the first two.
Green card holders face many legal questions tied to their immigration status, which can affect their tax residency status. Understand more by referencing the following articles:
The amount you may owe depends on the total taxable gain of your worldwide assets deemed sold, the day before you become a covered expatriate. This expatriation tax uses a deemed sale rule to figure out how much the exit tax is for your specific situation. You treat your property as if you sold it for its current market value, even though you keep the assets.
If you are a covered expatriate (see who has to pay, above), then you are required to pay the tax on these calculated gains. For 2026, you can reduce your total taxable gains by a $910,000 exclusion amount.
Suppose you own stocks worth $2,000,000 that originally cost you $500,000:
Your total unrealized gain on the deemed sale is $1,500,000.
The worst part of the tax regime for most people is not the exit tax; it’s the “forever taint” 40% tax on the asset values.
By merely being a covered expatriate, your family and friends who are U.S. citizens or residents will have to pay a 40% tax on property they receive from the covered expatriate in the form of a gift or inheritance. Using the example above of the exit tax on 590,000 dollars, if the covered expatriate now gifts $1,000,000 after the stock sale to his U.S. dual national daughter, she will be required to pay $400,000 of the forever taint tax.
How can you avoid the exit tax?
Certain dual citizens and minors may be exempt when they renounce U.S. citizenship. The law gets complicated here as well.
Yes, you are subject to the expatriation tax as a green card holder if you are a covered expatriate. You generally fall into this category by not formally abandoning your status (e.g., filing USCIS Form I-407) within the required time period permitted in the tax law. The law becomes extremely complicated for green card holders, especially for those residing within countries with an income tax treaty with the United States. See Aroeste vs. the United States.
What happens to your pension plans (e.g. IRA and 401(k))?
There are special rules that apply to your pension plans. You should review the details of your specific retirement plan with a legal professional.
💡 Tip: There are special tax treaty rules regarding pension plans that can be to your benefit. Some treaties have special tax expatriation rules incorporated; others do not, which can benefit the taxpayer.
One basic example is if you have a $400,000 IRA and are a covered expatriate. You may be required to report the full $400,000 as income on your tax return for the year you become a covered expatriate. You generally cannot use the $910,000 exclusion to lower the tax on this retirement account; however, special tax treaty rules may produce a particular beneficial outcome.
Here is a diagram to help determine whether you are a covered expatriate:
The two-step covered expatriate test, with 2026 dollar amounts. General information, not legal advice.
The “forever taint” 40% tax on gifts or bequests to your U.S. beneficiaries (Section 2801)
As already explained above, your covered expatriate status also triggers a lasting 40% tax forever into the future on any gifts or inheritances you leave to U.S. citizens or U.S. residents under Section 2801. This tax generally applies to the person receiving the gift, not the person giving it. For example, if you give a $1,019,000 gift to a U.S. person, you first subtract the $19,000 annual exclusion. Your heir will then owe a 40% tax on the remaining $1,000,000, which equals a $400,000 tax bill.
The U.S. beneficiary who receives the gift or inheritance from a covered expatriate is required to file new IRS Form 708 and pay the tax.
A green card holder may be able to end their U.S. residency by application of a tax treaty with another country. The law gets particularly complex depending on the facts of each circumstance, and Patrick W. Martin, the author, represented the green card holder in the landmark case Aroeste vs. the United States. This may trigger the same tax consequences as giving up your citizenship if you have held your green card for certain periods
What is Form 8854?
Form 8854 is the official form created by the IRS, which was found to be legally invalid in the case of Aroeste vs. the United States. See below the excerpt from the case:
C. Whether Aroeste Was Required to File Form 8854. The Government next argues that even if the IRS had accepted Aroeste’s amended returns, neither amended return would have properly notified the IRS of a commencement of treaty benefits because both failed to attach Form 8854, as required by IRS Notice 2009- 85. (Doc. No. 76-1 at 4–5.) The Government concedes Aroeste attached Form 8833 to both amended forms. (Id.) Aroeste responds that Notice 2009-85 is not binding authority as it fails to comply with the Administrative Procedures Act (“APA”). (Doc. No. 78-1 at 8 (citing Green Valley Investors, LLC v. Comm’r of Internal Revenue, 159 T.C. No. 5, at *4 (Nov. 9, 2022)) (under the APA, agencies must follow a three-step procedure for “notice-and-comment” rulemaking, but this requirement does not apply to “interpretive rules, general statements of policy, or rules of agency organization, procedure, or practice.”).) The Court agrees. In Mann Construction, Inc. v. United States, 27 F.4th 1138 (6th Cir. 2022), the court found that Notice 2007-83 failed to comply with the APA’s notice-and-comment procedure. Similarly here, because Notice 2009-85 has not been subject to a notice-and-comment procedure, it does not comply with the APA and thus is not binding. As such, Aroeste was not required to file Form 8854 with his amended returns. [emphasis added]

consulate, or office providing consular services will email you if and when your request has been approved. If your request is denied, the embassy, consulate, or office providing consular services will send you an email attaching a denial letter.