
Few basic U.S. tax compliance questions matter more to a U.S. citizen or green-card holder living abroad than what an unfiled FBAR can actually cost in penalties. Also, a green-card holder might not have any reporting requirements at all – given the law explained in the federal district court decisions originally appealed by the government in my 9th Circuit decision: Aroeste v. United States, Case No. 22-cv-00682-AJB-KSC.
What Are the Penalties for Not Filing an FBAR?

Failure to file an FBAR may result in a civil penalty if assessed by the government. The willful civil penalty is frankly more onerous than the criminal penalty that is maxed out by statute. The maximum civil penalty depends on whether the violation is determined to be non-willful or willful.
The statutory framework was initially set out by a federal district court in 2015, that also reviewed the FATCA laws, and it is worth reading the summary here:
A person who fails to file a required FBAR may be assessed a civil monetary penalty. 31 U.S.C. § 5321(a)(5)(A). The amount of the penalty is capped at $10,000 unless the failure was willful. See 5321(a)(5)(B)(i), (C). A willful failure to file increases the maximum penalty to $100,000 or half the value in the account at the time of the violation, whichever is greater. § 5321(a)(5)(C). In either case, whether to impose the penalty and the amount of the penalty are committed to the Secretary’s discretion. See § 5321(a)(5)(A) (“The Secretary of the Treasury may impose a civil money penalty[.]”)
Crawford v. U.S. Department of the Treasury (S.D. Ohio 2015 – Case No. 3:15-cv-00250)
The IRS internal revenue manual (4.26.16.4.1) summarizes how and why the IRS has purported authority to assess penalties for FBAR Title 31 violations as set forth below:
As of April 8th 2003, IRS was delegated the authority to assess and collect FBAR civil penalties. 31 C.F.R. § 103.56(g). The delegation includes the authority to investigate possible FBAR civil violations, provided in Treasury Directive No. 15-41 (Dec. 1, 1992), and the authority to assess and collect the penalties for violations of the reporting and recordkeeping requirements.
Was this delegation of authority from FinCEN to the IRS even valid as a matter of law? That questions has not been challenged yet in the courts.
When performing these FBAR functions, the IRS is not acting under Title 26 (the federal tax law) but, instead, is acting under the authority of Title 31 (the Bank Secrecy Act). Provisions of the Internal Revenue Code generally do not apply to FBARs and visa-versa. Does the IRS even have lawful authority to manage and assess these penalties – which previously were in the hands of the more obscure FinCEN.
What Is the Penalty for a Non-Willful FBAR Violation?

A non-willful FBAR violation may result in a civil penalty of up to $10,000 per violation. The Supreme Court has now held (after years of litigation) that, for non-willful violations, the penalty generally applies singularly – per report – rather than per account as the IRS argued for years. Bittner v. United States, 598 U.S. 85, 143 S. Ct. 713 (2023)
For years the government (IRS) read that $10,000 could be assessed for each account, and the Supreme Court finally resolved the question in 2023 against the government. The Ninth Circuit had ruled against the government in United States v. Boyd, 991 F.3d 1077 (9th Cir. 2021) and the Fifth Circuit (United States v. Bittner, 19 F.4th 734 (5th Cir. 2021)) overturned the federal district court in the eastern district of Texas in United States v. Bittner, No. 4:19-CV-415, 2020 WL 4200057 that had originally ruled in line with Boyd.
See an article I wrote on this issue along with two of my international tax colleagues at Chamberlain Hrdlicka: published as a Special Report in Tax Notes:
Six Weeks, Three International Information Reporting Decisions – 

On February 28th, 2023, the Supreme Court of the United States (“SCOTUS”) resolved in Bittner that the applicable non-willful FBAR penalty is not measured by every foreign account of the individual as the Service had argued for years and as they put into their IRM. The author had the opportunity to draft as one of the co-authors of the ACTEC amicus brief that was filed in Bittner. After Bittner, the total maximum penalty per year is $10,000 for non-willful violations. A maximum penalty of $50,000 (x5 years) applied per the SCOTUS versus the IRS determined amount of US$2.7M+ multiplying each account by $10K.
“Best read, the BSA treats the failure to file a legally compliant report as one violation carrying a maximum penalty of $10,000, not a cascade of such penalties calculated on a per-account basis.” The ACTEC brief was cited by the majority opinion- “ We see evidence, too, that the point of these reports is to supply the government with information potentially relevant to various kinds of investigations, criminal and civil alike. But what we do not see is any indication that Congress sought to maximize penalties for every nonwillful mistake (whether a late filing, a transposed account number, or an out-of-date bank address). See Brief for American College of Trust and Estate Counsel as Amicus Curiae 5–7.”
Importantly, the U.S. Supreme Court rejected the IRS interpretation of multiple per year non-willful FBAR penalties in Bittner v. United States, 598 U.S. 85, 143 S. Ct. 713 (2023).
What Is the Penalty (Civil) for a Willful FBAR Violation?
A willful FBAR violation may result in substantially higher penalties. The maximum penalty is generally based on the greater of a statutory amount or a percentage of the account balance.
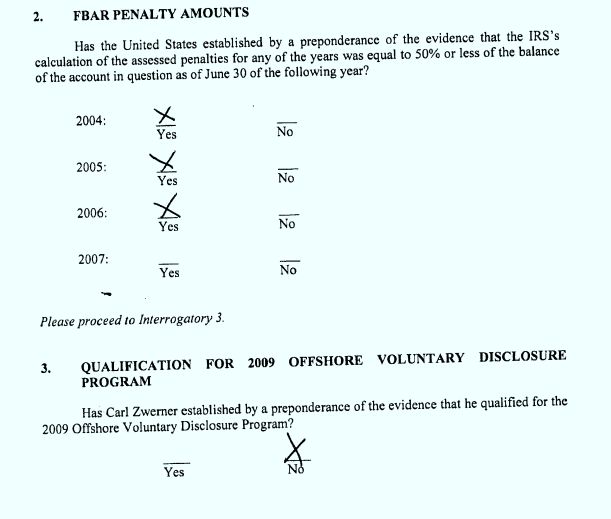
Because the willful penalty is measured against the account itself, it can exceed the balance entirely once assessed over several years. See, United States v. Carl R. Zwerner, Case No. 1:13-cv-22082-CMA (2014)
The government was on its face, very “successful” in the Zwerner case in convincing a jury they should render a verdict for 3 years of FBAR 50% willfulness penalties (150% of the account balance in total). The government tried to assert 4 years of willfulness penalties, which would have been 200% of the account balance; all under a civil penalty provision in the statute, that looks like a criminal penalty on its face and via its outcome.
In Zwerner, the taxpayer did come forward and disclose the unreported foreign accounts, and received a letter from the IRS CI on February 17, 2009, stating that ” . . . based upon the information provided a criminal investigation will not be initiated at this time. . . ” Nevertheless, the government pursued 50% civil willfulness penalty assessments for multiple years (4 years). The Tax Division of the Justice Department pursued this case through trial, incurring the time and costs of government resources, arguing Mr. Zwerner owed a total of $3,630,119.29 (on an account with a maximum value during the years at issue of apparently no more than US$1.69M) in their Motion for Summary Judgement.
In Count Six, Plaintiffs contend that the FBAR “Willfulness Penalty” is unconstitutional under the Excessive Fines Clause. Plaintiffs allege the Willfulness Penalty is designed to punish and is therefore subject to the Excessive Fines Clause. Plaintiffs further allege the Willfulness Penalty is grossly disproportionate to the gravity of the offense.
Can the IRS Penalize Each Foreign Account Separately?
Not for non-willful violations as explained above. The “jury is still out” regarding to what extent multiple years of 50% willfulness penalties may be assessed. The IRS has tempered their approach a bit over the last decade – particularly as of late, after losing a number of key FBAR cases going to trial.
Is the FBAR Penalty Mandatory?
No. The statute provides that the government may assess an FBAR penalty, giving the government discretion over whether, and in what amount, a penalty is imposed.
The distinction between what the statute permits and what it requires is easily missed, and it matters a great deal for individuals who have not filed FBARs. Especially for those residing outside the United States – including those individuals with green cards.
The relevant statutory provision is that “The Secretary of the Treasury may impose a civil money penalty on any person who violates, or causes any violation of, any provision of section 5314.” 31 U.S.C. Section 5321(a)(5)(B).
How Long Does the IRS Have to Assess an FBAR Penalty? – Six Years –
The IRS generally has six years to assess a civil FBAR penalty. This limitations period differs from the rules that apply to federal income tax returns.
The two bodies of law run on different time clocks.
The FBAR (the Foreign Bank Account Report) comes from a different law than the federal income tax. The income tax is from Title 26 of the U.S. Code. The FBAR comes from the Bank Secrecy Act, which is Title 31. These two laws are very different, with very different obligations and rights. One of the important differences is the time frame in which the government can assess penalties for not complying.
A statute of limitations is the time frame in which the government has to assess penalties for not complying with the law. For foreign accounts, these time periods are not the same under Title 31 (the Bank Secrecy Act) as they are under Title 26 (the income tax law). The gap between the two is what makes this area confusing.
No. When a U.S. citizen or LPRs residing overseas fails to file an income tax return, the time period for the IRS to make tax assessments never lapses. There is effectively no statute of limitations against the IRS in that situation. The clock to assess does not start until a return is filed.
Title 31, the Bank Secrecy Act, is different. It does have a time period that runs against the U.S. federal government, even if the FBAR was never filed. For civil assessments of penalties, that time period is 6 years. This important distinction helps drive strategic decisions of foreign account holders if they have failed to file FBARs.
There is a statute of limitations whether or not an FBAR was filed. Hence if a USC or LPR neglected to file an FBAR for the year 2006, for instance, the time period for the government to assess penalties has lapsed long ago. See, When does the Statute of Limitations Run Against the U.S. Government Regarding FBAR Filings?
How Does the IRS Collect an FBAR Penalty?
An FBAR penalty is generally not collected through the IRS’s ordinary tax lien and levy procedures. Instead, the government is typically required to bring a civil action to collect an unpaid penalty. They also have “off-set” rights that can be invoked against other payment amounts owed to the taxpayer. See, Bureau of the Fiscal Service and their powers through the  Treasury Offset Program (TOP).
Assessing a penalty and actually collecting it are separate problems for the government, particularly where the taxpayer and the assets are outside the United States.
The collection of the FBAR penalty is not as easily collected under the law, as is a tax claim. A Title 26 tax lien and levy claim against the taxpayer’s property cannot be used to collect an FBAR penalty. Instead, the government has rights of set-off and will typically be required to bring a judicial action in Court to enforce the penalty assessment. See, an early case, United States v. Williams, 489 F. App’x 655 (4th Cir. 2012), where the government sued to collect the 50% FBAR willfulness penalty.
The laws of many countries outside the U.S. often conclude that enforcing these FBAR penalties against a U.S. citizen or LPR, inside that person’s home country, violates the laws of that country. Canada is one example. Calgary based tax attorney Roy Berg has written on the question of whether the IRS can collect FBAR penalties under the Canada-US Treaty.
The “Revenue Rule” was a common law concept that generally prohibited the U.S. government from assisting in the collection of taxes of another country. Hence, the U.S. Treasury renegotiated the treaties with five countries (including Canada) that now have a specific treaty provision such as XXVI A above:
As a result of these cases and the Revenue Rule, the U.S. and Canada modified their income tax treaty to (at least in theory) to allow for the international enforcement of taxes. The U.S. now has five income treaties with “mutual assistance” provisions: Canada, Sweden, France, Denmark, and the Netherlands (with a clause in the newly negotiated, but yet to go into force, Swiss treaty).
In the Dewees case, we learned that the assistance in collection provision is not merely a theoretical tool that can be used in collecting taxes. The IRS was successful in a long running case with FBAR penalties and Title 26 penalties for failure to file IRS forms 5471 regarding the U.S. citizens Canadian companies. He lived in Canada. See, Dewees v. United States, 272 F. Supp. 3d 96 (D.D.C. 2017), which was subsequently affirmed by the D.C. Circuit Court of Appeals (Dewees v. United States, 767 F. App’x 4 (D.C. Cir. 2019)). The actions of both the Canadian (CRA) and U.S. governments (IRS and District Court Judge), made the provision effective. The US$120,000 penalty, that has nothing to do with any U.S. income taxes owed (nor FBAR penalty), was collected by the IRS; a penalty under 26 U.S.C. § 6038(b) for failure to file informational returns – .
Can an FBAR Violation Lead to Criminal Charges?
Yes, but not every FBAR violation is a criminal matter. Criminal liability generally requires proof of willful conduct and carries a burden of proof on the government – (beyond a reasonable doubt) – and always depends on the facts of the case.
Yes. A U.S. citizen or LPR living overseas could in theory become criminally liable for willfully not filing the FBAR form. Criminal liability carries different legal consequences than a civil penalty. These are not easy cases for the government – and hence they rarely have brought criminal FBAR cases for taxpayers residing overseas. It all depends upon the facts.
IRS Criminal Investigation (division) has been delegated the authority to investigate possible criminal violations of the Bank Secrecy Act. 31 C.F.R. §103.56(c)(2). This should not be taken lightly.
Yes, there are also statutes of limitations for criminal charges the government brings for FBAR violations. The law gets much more complex here, especially when the taxpayer is residing outside the U.S. In that situation, the time period can be tolled or suspended in favor of the government, which extends the window to bring charges. Jack Townsend (an amazing, now retired criminal tax defense lawyer who has contributed extensively to the tax law practice) has written on the statutes of limitations for FBAR noncompliance related to tax reporting. Jack is co-author of Tax Crimes – John (“Jack”) Townsend with my law partner the esteemed criminal tax defense lawyer Larry Campagna along with Steve Johnson, and Scott Schumacher.
U.S. citizens residing overseas clearly have FBAR filing requirements – if they meet the thresholds. The law is quite different for those with “green cards” residing predominantly overseas in a country with an income tax treaty with the U.S. Here, it gets a lot more complicated, but see my case of Aroeste v. United States, Case No. 22-cv-00682-AJB-KSC (2023) that was appealed to the Ninth Circuit by the government after they lost.
What Can We Learn from Real FBAR Penalty Cases?
Reported cases show that the outcome of an FBAR penalty dispute depends heavily on the facts. They also demonstrate that proposed penalties may be successfully challenged in appropriate cases.
One case makes the point better than any summary of the rules could.
This case was covered extensively by various tax journalists and followed by tax professionals around the world from the time it started until it concluded. I know, because I was the lead attorney representing the then 91 year old widow from Canada, dear Mrs. Margaret Jones. The pleadings in the case can be viewed here – Margaret J. Jones v. United States (2:19-cv-04950)
In my view, this case should have never ended up before the U.S. District Court. The IRS erred in making a determination of “willful blindness” against Mrs. Jones who was legally blind at her advanced age. They conceded Mrs. Jones had no actual knowledge of the reporting requirement. She was advised for more than two decades by a CPA, both she and her late husband (an immigrant from New Zealand). They both had accounts that were decades old from their respective countries – Canada and New Zealand. Held openly and directly for the majority of their lives.
Mrs. Jones did the right thing by going to the Streamlined Filing Procedure (the streamlined filing procedure) and correcting her errors on her tax returns. She was then selected by the IRS for audit (because of that filing) where she got a tax refund of over $20,000. For that effort, time and expense, the IRS turned around and slapped her with US$3.4M of “willful blindness” penalties regarding her accounts in Canada and New Zealand, most of which were her husband’s accounts. Her late husband served in World War II while living in New Zealand before moving to the U.K. then Canada (where he met Mrs. Jones) and then on to the U.S. They both had high school diplomas.
The case was set for a jury trial (on two occasions) but Judge Selna postponed it on both occasions due to the Corona-virus. Unfortunately, Mrs. Jones never had her day in Court where I believe a jury would have found that the government did not carry its burden against Mrs. Jones and her late husband. Not even a close call. Her facts were not nefarious, unlike most of the cases where sophisticated taxpayers have been hiding their assets from the IRS, such as in Swiss bank accounts.
After the government conceded the bulk of the case and it was dismissed just before Christmas of 2020, Mrs. Jones passed away shortly afterwards. May her Soul Rest in Peace.
The DOJ drives the bus (NOT the IRS) once the case falls into their hands.
A jury trial should always be considered in the right case, a good faith taxpayer case, as jurors will generally see and understand the big picture.
By contrast, in Zwerner the penalty amount apparently sustained by the jury has been reported as “. . . $2,241,809 on an offshore account that had an apparent high balance of $1,691,054. . . “
The author has spoken on defending Title 31 FBAR penalties at the University of San Diego School of Law – International Tax Institute, alongside Caroline D. Ciraolo, former Acting Assistant Attorney General of the Justice Department’s Tax Division, and Robert S. Horwitz; and many other panels and forums advising clients on these FBAR issues. Seek advice on FBAR issues if you have a filing requirement.


 ar case. A legal adviser should be able to assist an individual in taking important decisions and steps, related to the specific goals of the individual, while understanding the legal and tax consequences of each step. There are a range of consequences that the “U.S. tax expatriation” laws impose upon different types of transactions, transfers, reorganization of assets, etc. None of these items are discussed in this