International Tax · Citizenship Renunciation · LPR Abandonment
International Tax Shareholder
FAQs re: Tax Expatriation: Aroeste v. United States Impact – Frequently Asked Questions
The U.S. tax law is complicated generally. It gets really complex when you renounce your United States citizenship or you cease to be a “lawful permanent resident” as that term is technically defined in the U.S. federal tax law. The comments in Tax-Expatriation.com are designed to help demystify some of this complexity.
Hence, posts addressing various FAQs – for those who have or “had” a “green card” – please see the following:
IRS Removes Practice Unit from their Website – titled “Determining Tax Residency Status of Lawful Permanent Residents” – Post-Aroeste
The decision in Aroeste v. United States, continues to affect how U.S. tax treaty rules apply to green card holders. In Aroeste, the federal district court rejected important IRS-DOJ arguments concerning when a lawful permanent resident is not treated as a resident of the United States under an income tax treaty. I refer to the broader consequences of the case as the Aroeste Effect, which rears its head in proposed Treasury Regulations to be discussed for another day.
For years, the IRS Large Business and International Division (LB&I) published a Practice Unit titled Determining Tax Residency Status of Lawful Permanent Residents. Issued in 2013 and updated in 2014, it was used to help IRS personnel determine the U.S. tax residency of green card holders—the very subject litigated in Aroeste. That Practice Unit has now been removed from the IRS website.
The removal is notable because the IRS continues to publish other related international tax Practice Units. For example, its 2018 Practice Unit, remains available: Determining an Individual’s Residency for Treaty Purposes PDF This 2018 Practice Unit has not been updated to address Aroeste. Importantly, however, it does not repeat the government’s argument in Aroeste that a taxpayer can lose or waive treaty benefits by failing to timely “take” a treaty position. The district court rejected the government’s position on that issue.
The IRS has not publicly explained why it removed the Practice Unit specifically addressing lawful permanent residents. Nevertheless, its disappearance after Aroeste is significant. For green card holders living outside the United States, the practical issue is straightforward: holding a green card does not necessarily mean the individual must always be a “United States person” – i.e., a U.S. tax resident. An applicable tax treaty can change that result.
The intricacies of the law can be complex, depending upon the facts of each person. The IRS’s removal of its own Practice Unit on this subject is another noteworthy example of the Aroeste Effect.
A U.S. Immigration Officer Stops You at at the Airport – @ the Point of Entry (Demands your Green Card be Turned Over))
Being stopped, searched, interrogated or simply questioned by U.S. federal government agents can be intimidating. Especially, if you do not know your legal rights.
It can be more intimidating on your arrival to the U.S. airport, if the CBP officer (U.S. Customs and Border Protection) demands that you physically “return voluntarily” your green card. The consequences they tell you will be immediate deportation from the U.S.
Removal from the U.S. – is it voluntary or not, under these circumstances?
What are the U.S. federal tax consequences if you “return voluntarily” your green card?
What if the CBP officer pulls out Forms W-8s you previously signed with your foreign financial institution and presents them to you in the airport and asks the following questions:
Why did you certify “under penalty of perjury” you were not a United States person on your foreign bank produced documents (you received in France, Germany, the U.K., Canada, Mexico, Japan, Indonesia, Australia — or any other foreign country)?
The officer then asks for all of the envelopes and papers in your luggage and opens the letters and files in your possession – See, the U.S. Supreme Court decision United States v. Ramsey, 431 U.S. 606 (1977).
Tax Problems that Turn Serious – can Cause a Green Card Holder to become a “Covered Expatriate”
In Kawashima v. Holder (565 U.S. 478 (2012), the United States Supreme Court held that certain tax offenses committed by lawful permanent residents constitute crimes involving “fraud or deceit” for purposes of the Immigration and Nationality Act (“INA”). Specifically, the Court concluded that lawful permanent residents (a husband and wife from Japan) who were convicted of filing false tax returns resulting in a tax loss exceeding $10,000 had been convicted of an “aggravated felony” within the meaning of the INA.
As a consequence, a conviction for such an aggravated felony renders a lawful permanent resident removable (deportable) from the United States under the immigration laws. Importantly, however, the criminal conviction itself does not automatically terminate lawful permanent resident status. Rather, it provides the legal basis for the Department of Homeland Security to initiate removal proceedings, after which an Immigration Judge may enter a final order of removal.
Once a final order of removal becomes effective, the individual’s lawful permanent resident status is considered to have been revoked. For U.S. federal income tax purposes, this generally results in the termination of lawful permanent resident status under 26 U.S.C. § 7701(b)(6)(B), which provides that an individual ceases to be a lawful permanent resident when “such status has been revoked or has been administratively or judicially determined to have been abandoned.” Accordingly, following a final order of removal, the individual is no longer treated as a lawful permanent resident for purposes of the tax law as summarized below:
Stage
Legal Effect
1. Criminal conviction (including guilty plea)
If the offense qualifies as an “aggravated felony” under INA §101(a)(43), the individual becomes deportable under 8 U.S.C. §1227(a)(2)(A)(iii). A guilty plea counts as a conviction for immigration purposes if the statutory definition of “conviction” is satisfied.
2. DHS initiates removal proceedings
DHS serves a Notice to Appear (NTA) charging removability before an Immigration Judge under 8 U.S.C. §1229a.
3. Immigration Judge determines removability
DHS bears the burden of proving deportability by clear and convincing evidence, typically through the certified judgment of conviction.
4. Final order of removal
If removability is sustained and no relief is available, the Immigration Judge orders removal. After appeals are exhausted (or waived), the removal order becomes final, and the person’s LPR status ends.
The 2012 case involved Akio and Fusako Kawashima, Japanese citizens who had been lawful permanent residents since 1984. Mr. Kawashima pleaded guilty to willfully filing a false tax return under 26 U.S.C. § 7206(1), while Mrs. Kawashima pleaded guilty to aiding and assisting in the preparation of a false tax return under 26 U.S.C. § 7206(2). The immigration judge issued the order of removal. The Board of Immigration Appeals affirmed. Holding that convictions under 26 U. S. C. §§7206(1) and (2) in which the Government’s revenue loss exceeds $10,000 constituted aggravated felonies, the Ninth Circuit affirmed and ultimately so too did the SCOTUS in this decision.
The Supreme Court concluded that these tax offenses necessarily involve fraud or deceit and, because the tax loss exceeded the statutory $10,000 threshold, they constituted aggravated felonies under immigration law. The Supreme Court of the U.S. therefore upheld the government’s order (which had been upheld through the Ninth Circuit Court of Appeals) removing the Kawashimas to Japan.
This of course is important for U.S. “expatriation tax” purposes, since the “lawful permanent resident” status for tax purposes will necessarily terminate upon the final order of removal. Not before. Once LPR status terminates, the individuals will become covered expatriates, if they meet the time period under the statute to become “long term residents” as was the case for Mr. and Mrs. Kawashima and meet either of the three tests: the tax liability, net asset and certifications of compliance with the federal tax laws. See, Why a “long-term” LPR can NEVER avoid “Covered Expatriate” status under IRC Section 877A(g)(1)(B) if Asset or Tax Liability Test is Satisfied!
EB-5 Visa – a common Path to a “Green Card” and then USC
Pathways to United States Citizenship – (USC): Focus on the EB-5
Every individual who ultimately becomes a naturalized U.S. citizen must first qualify for lawful permanent resident (“LPR”) status unless a narrow statutory exception applies. Although public attention frequently focuses on the EB-5 immigrant investor program, with the idea they are those with greater assets and income (contemplating taxes) EB-5 investors represent only a very small percentage of all individuals who become lawful permanent residents. Understanding the relative size of each immigration pathway is essential because every pathway ultimately raises many of the same U.S. tax issues—including worldwide income taxation, estate and gift taxation, and the tax consequences of later abandoning lawful permanent resident status or renouncing U.S. citizenship.
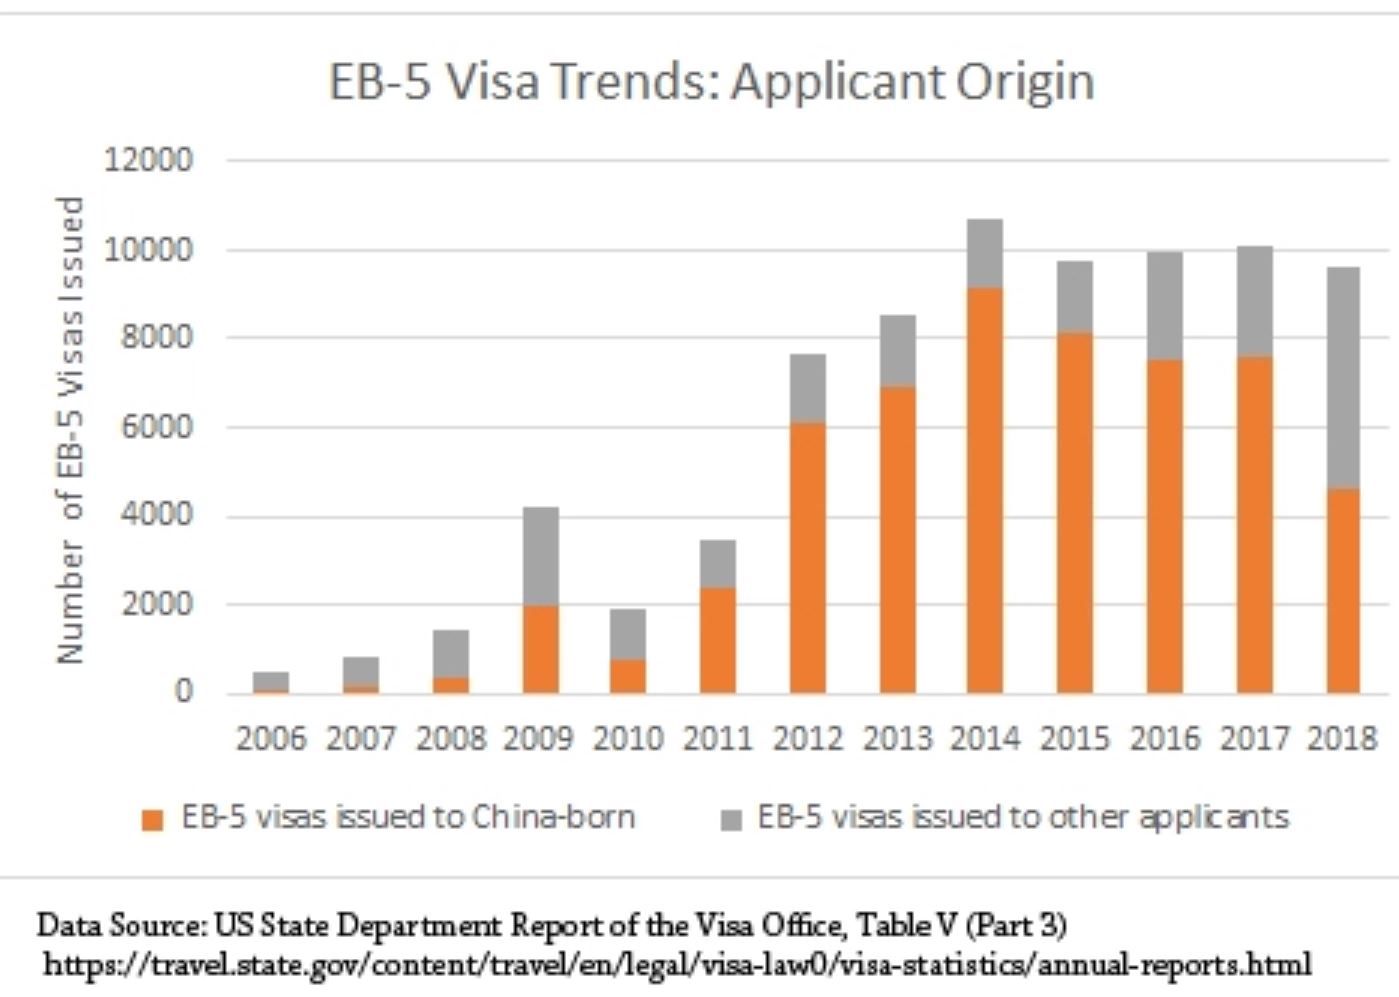
The EB-5 visa has been a fixture of U.S. law since the early 1990s. It was not until 2009 that a substantial number of EB-5 visas were issued in a given year, 4,218 to be exact. Statistically, the total EB-5 visa leading to LPR status is a fraction of the other categories as explained here. For an excellent overview of the law and categories, see the CRS report- Permanent Legal Immigration to the United States: Policy Overview (Updated November 4, 2024)
EB-5 Visa – to a “Green Card” then to United States Citizenship – (USC)
From the laws inception in 1992 through FY2004, there were only 6,024 EB-5 visas issued during that 12 year period. That is an annual average of only approximately 500 persons. See, the GAO Report on Immigrant Investors. As the program grew in popularity so too did the location of investors from around the world. It was not until 2009 when the total number of investors started growing substantially. Most significantly in 2009 when 4218 EB5 visas were issued, still less than 1/2 of the 10,000 allocated annually by the statute.
These numbers kept going at an annual pace especially starting in 2012, when 6,764 EB-5 visas were issued and then around 10K+/- annually for the last dozen years or so, up until the years that were impacted by a change in the law and a bit by COVID (2020 and 2021). There are important tax consequences that can have unintended outcomes for individuals who get a green card: See, Oops…Did I “Expatriate” and Never Know It: Lawful Permanent Residents Beware!International Tax Journal, CCH Wolters Kluwer, Jan.-Feb. 2014, Vol. 40 Issue 1, p9):
Chinese Investors Have Dominated the total Group of EB-5 Investors
The country-of-origin analysis is important because practitioners frequently advise clients from these jurisdictions regarding immigration planning, cross-border tax planning, and eventual expatriation planning with consequences in those countries.
I have compiled the total list of countries from which EB-5 visa investors came from as summarized in the Country of Origin global graphic for FYE 2024. There are over 100 countries from which these investors came from, but again, China is the dominant country, followed by Vietnam, India, Taiwan and then South Korea as the countries with the greatest number of investors. South Africa comes next, followed by Brazil and then Mexico, but each with less than 200 total investors, each country as follows:
China
9547
Vietnam
1533
India
1428
Taiwan
513
Korea, South
325
South Africa
158
Brazil
157
Mexico
128
Hong Kong S.A.R.
116
Venezuela
97
Canada
81
Great Britain & N. Ireland
63
Russia
58
Nigeria
52
Turkey
44
Colombia
44
France
38
United Arab Emirates
30
Germany
29
Japan
25
Singapore
23
Kazakhstan
21
Peru
20
Ukraine
17
Sweden
15
Argentina
15
Egypt
14
The importance of this analysis is to help individuals (and their advisors) who fit into these categories, e.g., who have a pathway to a green card and then on to become a naturalized U.S. citizen, understand the potential “tax expatriation” consequences of their decisions over the long-run.
What are the U.S. “tax expatriation” consequences to individuals who go down these pathways, including to their dependent children, or spouses or any future beneficiaries who are “United States person”?
What are the tax expatriation consequences if the individual later decides they do not want to be a green card holder or a U.S. citizen and later wishes to abandon their lawful permanent residency status or formally renounce their U.S. citizenship?
These and many other questions should be considered, especially for long-term family planning. Not just for the investor, but for their children and spouse, who may be eligible for the visa that can lead to LPR status and eventually to USC. Facilitating younger children (under 21 years of age) is a common driver for EB-5 investors for families who want the United States to be a pathway for their children’s’ future.
Why These Immigration Pathways Matter from a Tax Perspective
Every pathway leading to lawful permanent resident status almost always subjects the individual to the comprehensive U.S. federal income tax system. Depending upon the individual’s assets, family structure, treaty residence, and future living plans, obtaining a green card will also have significant implications for:
worldwide income taxation;
estate and gift taxation;
foreign trust reporting;
information reporting obligations under various laws;
controlled foreign corporation rules;
PFIC reporting;
exit tax planning; and
long-term succession planning.
Equally important, many lawful permanent residents eventually decide to return permanently to their country of origin or another foreign jurisdiction. Those individuals—and frequently their spouses and dependent children—must carefully consider the tax consequences of formally abandoning lawful permanent resident status or, after naturalization, renouncing U.S. citizenship. The sooner individuals and their advisors realize these consequences, the better they can plan for important life decisions.
Those tax consequences are collectively referred to as the U.S. tax expatriation rules, and they form the principal subject of this website.
The legal pathways towards lawful permanent residency status can be broken down into the following categories and the EB-5 category is a fraction (only about 1%) of the total pool leading to LPR status:
This category includes EB-1 through EB-5 categories that include individuals with extraordinary ability, certain professionals, other skilled workers. The chart I prepared here reflects the total number of EB-5 visas issued cumulative. This chart reflects the total number of cumulative EB-5 visas that have been issued through the FYE 2024 of approximately 131K. This does not take into consideration how many of these were issued to the principle investor versus spouses and children under twenty-one years of age. See, 8 U.S. Code § 1153(b).
EB-1, EB-2 and EB-3 represent the greatest group of individuals who obtained LPR status (e.g., approximately 5X, each category compared to the EB-5 category). See Yearbook of Immigration Statistics, Table 6.
For instance, annually the EB-1 through EB-3 categories are processing about 50K per year of each, and the EB-5 category is only 131K over most of its 25 year life (or about 10K per year – for more recent years). Approximately 16% of all green card holders come through these employment based preferences.
Table – Approximate Decade-Average Share by Category, FY2014–FY2023
Category
Approx. Share
Notes
Family-sponsored (total)
~64%
Immediate relatives + family preferences combined
— Immediate relatives
~46%
Spouses ~26%, parents ~14%, children ~6%
— Family preferences (F1–F4)
~18%
Numerically capped at 226,000
Employment-based (EB-1–EB-5)
~16%
Capped at 140,000; breached in COVID years
Refugees & asylees
~12%
Numerically unlimited; ceiling-driven volatility
Diversity
~4%
Statutory ceiling 55,000
All other / special
~4%
SIV, U/T victims, cancellation, registry, etc.
C. Diversity Immigrant Program
The annual diversity lottery, allocated by random selection, to natives of countries with historically low rates of immigration to the United States. See, 8 U.S. Code § 1153(c). The Attorney General plays a key role by statute in this determination. There is a statutory maximum of 55,000 and only represents about 4% of all LPRs compared to the larger pool. This program is on hold as of December 19, 2025 when the USCIS policy memorandum (PM-602-0193) directs officers to place an immediate hold on pending adjustment of status, ancillary benefits and associated waiver applications for individuals applying through the Diversity Immigrant Visa program. [1, 2]
D. Humanitarian and Special Pathways: Refugees/Asylees
Several routes proceed outside the preference system (the three categories above). Refugees and asylees adjust under a specific statutory regime; self-petitioning abused spouses and children proceed under other provisions; victims of qualifying crimes and of trafficking can adjust from U and T nonimmigrant status; and certain children subject to qualifying juvenile-court findings can qualify, among others. There are statutory limits placed on this group.
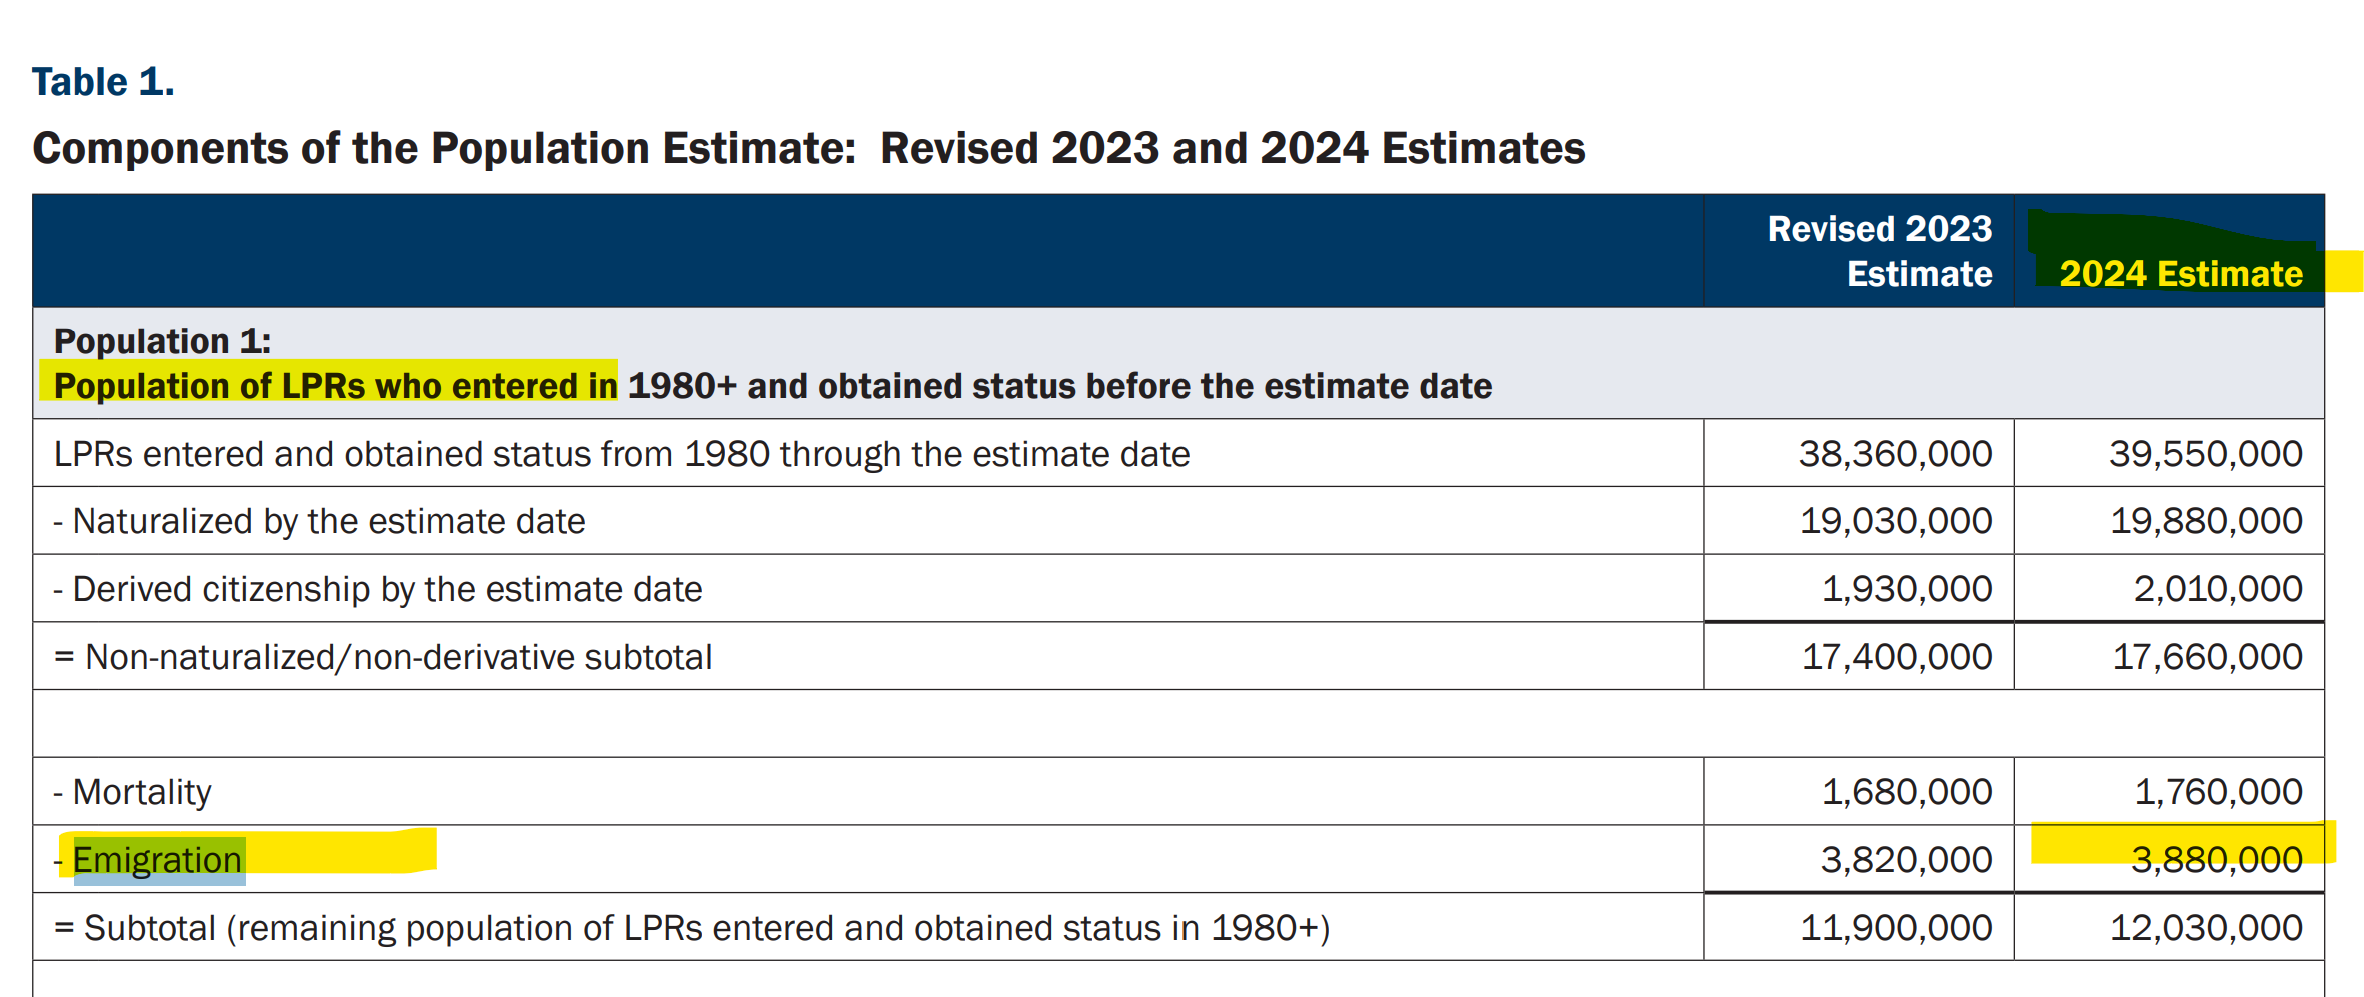
Whatever category one uses for LPR status, there will be important U.S. federal tax consequences to them and typically their family members. That’s the large part of the focus on this forum where the author has written about the subject of how it all ties to “tax expatriation”. As previously reported, there are 3.88 million “LPR” individuals who are living outside the U.S. – per the 2024 report by the U.S. federal government. Many of them live in a treaty country. See, Table 1 of the Homeland Security, Office of Immigration Statistics – Estimates of the Lawful Permanent Resident Population in the United States and the Subpopulation Eligible to Naturalize: 2024, and Revised 2023.
Part II of Part II: The Gold Card – The U.S. Tax Costs – “It’s like the green card, but better and more sophisticated.”
See Part I for the background discussion, which was published more than a year ago.
This article focuses on the tax consequences of the “Trump Gold Card” program and, in particular, the implications if participation ultimately leads to U.S. citizenship (“USC”).
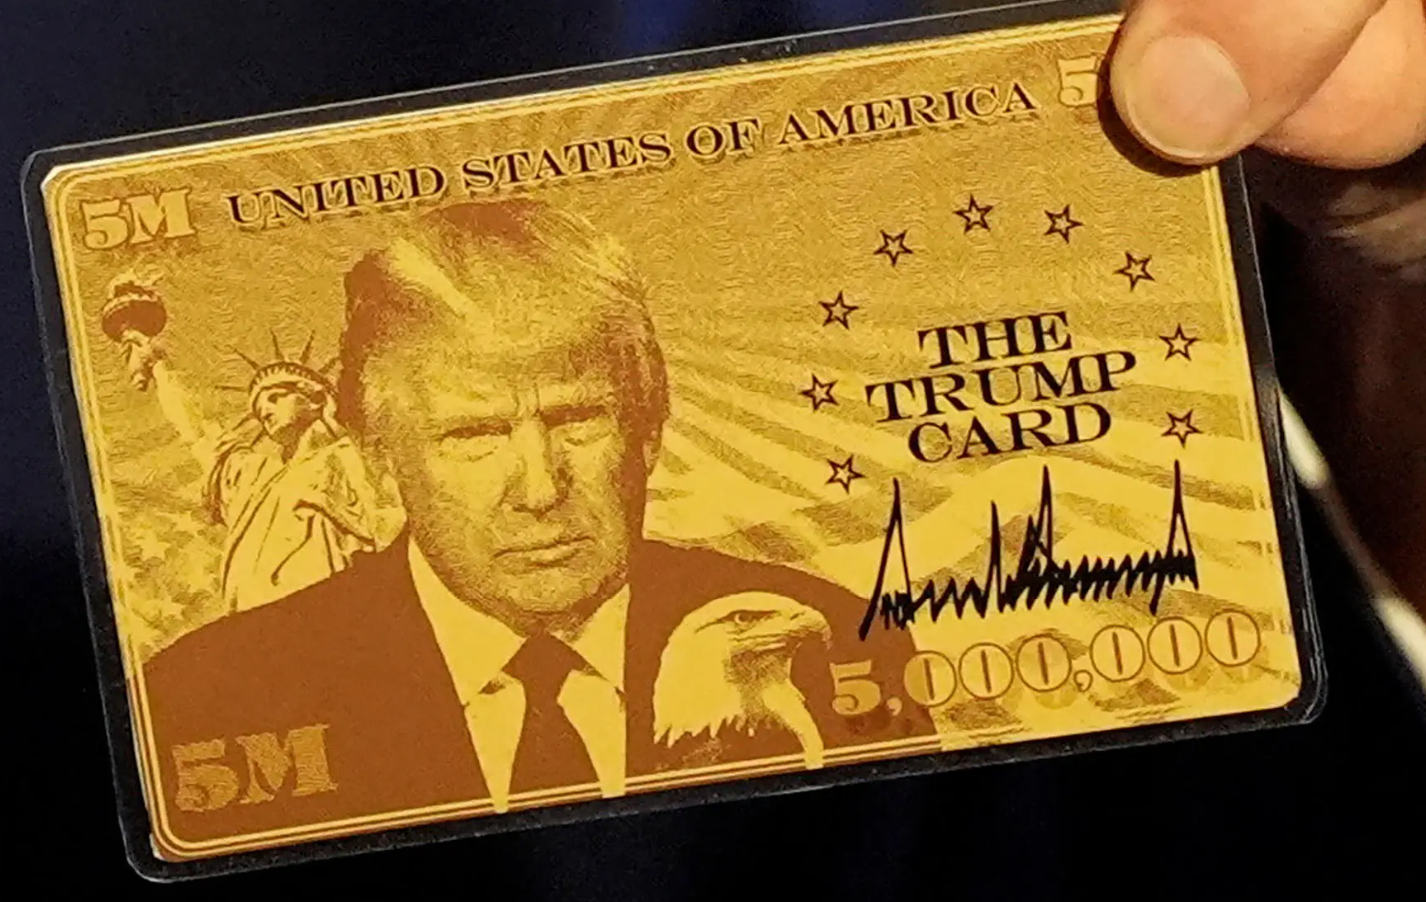
The final version of the Gold Card program requires a $1 million contribution to the federal government, rather than the $5 million amount initially discussed in April 2025. See the government website, The Trump Gold Card is Here.
It is also important to note that President Trump established the Gold Card program through Executive Order 14351 in September 2025. Congress did not enact the program through legislation.
The Cost of a Trump Gold Card
For a $15,000 Department of Homeland Security processing fee and, following successful background review, a $1 million contribution to the federal government, an applicant may obtain U.S. permanent residence through the Gold Card program.
Why Would an Ultra-High-Net-Worth Individual Voluntarily Enter the U.S. Tax Net?
A fundamental question arises: Why would an ultra-high-net-worth (“UHNW”) individual contribute $1 million to obtain U.S. residence and potentially U.S. citizenship, thereby becoming subject to one of the world’s most expansive tax systems?
For many individuals, acquiring U.S. citizenship or lawful permanent resident (“LPR”) status can result in exposure to:
U.S. income taxation on worldwide income;
U.S. gift taxation on worldwide transfers of property; and
U.S. estate taxation on worldwide assets at rates that currently reach 40%.
U.S. Estate and Gift Taxation of Worldwide Assets
The United States generally imposes estate and gift taxes on the worldwide assets of U.S. citizens. In addition, lawful permanent residents who are domiciled in the United States may become subject to the same worldwide transfer tax regime.
Unlike many countries, the United States generally does not permit its citizens to escape worldwide taxation simply by relocating abroad. Most U.S. income tax treaties and estate and gift tax treaties contain a “savings clause” that preserves the right of the United States to tax its citizens notwithstanding treaty provisions.[1]
U.S. Estate and Gift Taxation of Worldwide Assets
As a result, the worldwide assets of a U.S. citizen may be included in the U.S. transfer tax system under IRC §§ 2001 and 2031 (estate tax) and IRC §§ 2501 and 2511 (gift tax).
Consider a U.S. citizen who owns:
a residence in Norway;
shares of a Mexican corporation;
a bank account in Singapore;
an interest in a Liechtenstein foundation (Stiftung);
a portfolio of securities held through a London financial institution; and
an apartment in Dubai.
Subject to applicable valuation and ownership rules, each of these assets generally forms part of the individual’s worldwide taxable estate for U.S. estate tax purposes.
By contrast, a non-U.S. citizen who is not domiciled in the United States generally would not be subject to U.S. estate tax on any of these assets, unless they include U.S.-situs property such as stock issued by U.S. corporations.
The difference can be dramatic: no U.S. estate tax exposure versus potential exposure to a 40% U.S. estate tax on worldwide assets.
U.S. Income Taxation of Worldwide Income
The contrast is equally significant in the income tax context.
A nonresident generally is subject to U.S. income taxation only on limited categories of U.S.-source income and income effectively connected with a U.S. trade or business.
A U.S. citizen, however, remains subject to U.S. federal income taxation on worldwide income regardless of where the individual resides.
Consequently, a foreign entrepreneur, investor, or family office principal who acquires U.S. citizenship will find that income earned from businesses, investments, trusts, partnerships, and financial accounts throughout the world generally becomes reportable to the Internal Revenue Service and subject o U.S. income taxation.
That result raises an obvious question: if the program is available, why have so few ultra-high-net-worth individuals pursued it successfully?
The most obvious explanation is that the long-term U.S. tax consequences may outweigh the perceived immigration benefits for many globally mobile individuals.
Comparison to the EB-5 Program
Different applicants may have different motivations.
The traditional EB-5 immigrant investor program generally requires a qualifying investment that, if successful, may ultimately be recovered. The program also requires satisfaction of statutory requirements, including job creation. Approximately 200,000+/- individuals have obtained a green card through the EB-5 program. There are important unintended tax consequences that can befall individuals here: see, Oops…Did I “Expatriate” and Never Know It: Lawful Permanent Residents Beware!International Tax Journal, CCH Wolters Kluwer, Jan.-Feb. 2014, Vol. 40 Issue 1, p9).
EB-5 Visa Applicants by Country
By contrast, the Gold Card program requires a direct contribution to the federal government.
In either case, the successful applicant receives lawful permanent resident status. However, if the Gold Card ultimately serves as a pathway to naturalized U.S. citizenship, the applicant may become subject to the unique worldwide taxation regime applicable to U.S. citizens.
The Expatriation Problem
If Gold Card holders ultimately naturalize as U.S. citizens, future departure from the U.S. tax system will necessarily become significantly more complicated.
Individuals who later seek to relinquish U.S. citizenship will necessarily face the expatriation rules of IRC § 877A and be tainted with “covered expatriate” status.
As discussed in earlier posts, covered expatriate status can have substantial long-term tax consequences for both the expatriating individual and future recipients of gifts and inheritances.
Legal Questions Surrounding the Program
The Gold Card program also raises constitutional and statutory questions.
Unlike the EB-5 program, which was enacted by Congress, the Gold Card program was created through executive action. Congress did not amend Title 8 of the United States Code to establish a new immigrant category.
Whether the Executive Branch possesses sufficient statutory authority to create such a program remains an open legal question (I am doubtful it will be sustained – if challenged) and will likely be the subject of continued litigation and judicial review.
The outcome of pending litigation involving other immigration-related executive actions may provide useful guidance regarding the scope of presidential authority in this area. We await the outcome of the latest case litigated through the courts. See, Supreme Court appears likely to side against Trump on birthright citizenship which was also issued by an executive order.
Who Truly Benefits?
Who is the ideal candidate for a Trump Gold Card? Only one person thus far has one.
For almost all HNW individuals, the immigration benefits, travel flexibility, business opportunities, and potential pathway to U.S. citizenship would rarely justify the cost. Someone with assets below US$20M might find it attractive.
For almost all others—particularly those with substantial foreign businesses, investment portfolios, trusts, and family wealth located outside the United States—the long-term consequences of worldwide U.S. income, estate, and gift taxation will almost always substantially outweigh the advantages.
As a result, any prospective applicant for a Trump Gold Card should carefully evaluate not only the immigration benefits of the program (+ the uncertainty in the law), but particularly the tax consequences that will follow for decades thereafter.
Why Long-Term Green Card Holders Cannot Escape the Exit Tax Rules
When long-term green card holders give up their green card, they face the same exit tax rules as US citizens who renounce citizenship. There is one exception in the law that allows certain dual citizens by birth to avoid covered expatriate status even if they meet the income or asset tests. Long-term green card holders cannot use it. Here is why.
When you give up your green card (or renounce US citizenship), the law determines whether you are a covered expatriate. You are a covered expatriate if you meet any one of three tests: an average annual income tax liability above an inflation-adjusted threshold, a net worth of $2 million or more on the date of expatriation, or a failure to certify 5 years of US tax compliance – where it is commonly certified on IRS Form 8854.
Meeting even one of these three tests makes you a covered expatriate. All three tests apply equally to US citizens who renounce and to long-term lawful permanent residents (LPRs) who give up their green card.
Is there an exception to the income and asset tests?
Yes, for some people. Under IRC Section 877A(g)(1)(B), certain individuals are exempt from the income and asset tests. If this exception applies to you, you can avoid covered expatriate status even if your net worth exceeds $2 million or your income exceeds the threshold. The certification requirement under Section 877(a)(2)(C) still applies to everyone, including those who qualify for this exception.
Who can use this exception?
The exception is narrow. Under the statute, it applies only to an individual who: became a citizen of the United States and a citizen of another country at birth; as of the date of expatriation, continues to be a citizen of and is taxed as a resident of that other country; and has been a US resident for no more than 10 taxable years during the 15-year period ending with the taxable year of expatriation. Only someone who acquired US citizenship automatically at birth, while also holding citizenship of another country from birth, can potentially qualify.
Why green card holders cannot use it
Lawful permanent residents are not US citizens. They hold a green card, which is a grant of permanent resident status, not citizenship. Because the exception in Section 877A(g)(1)(B) applies only to individuals who became US citizens at birth, long-term LPRs cannot satisfy this requirement by definition. The exception is simply not available to them.
What this means if you are a long-term green card holder
A long-term LPR who meets either the $2 million asset test or the income tax liability test will become a covered expatriate, even if they fully satisfy the 5-year certification requirement. Satisfying the certification requirement is necessary for everyone, but for long-term LPRs it is not sufficient on its own. If you also meet the income or asset test, you are a covered expatriate regardless.
The consequences include the mark-to-market exit tax on unrealized gains and the Section 2801 tax on covered gifts and bequests to US persons. These consequences can affect your US family members for decades. Understanding them well before you give up your green card, not after, is the only way to plan for them.
There are important unintended tax consequences that can befall individuals who have a green card depending upon their factual circumstances: see, Oops…Did I “Expatriate” and Never Know It: Lawful Permanent Residents Beware!International Tax Journal, CCH Wolters Kluwer, Jan.-Feb. 2014, Vol. 40 Issue 1, p9):
This post provides general information only and is not legal advice. Consult an experienced attorney for guidance specific to your situation.
Green Card Holders (Abandonment) – so Many More than U.S. Citizens who Renounce: The Topsnik Problem(s)!
I have previously written (pre-Aroeste v. United States) about the thorny issues that LPRs face when spending substantial time outside the United States. See an earlier post titled:
I highlighted some key concepts about why it matters if you become a “long-term” resident as that term is defined in the tax law and now the case law in Aroeste makes these risks clear as confirmed in the landmark case.
A LPR can reside for substantially shorter periods in the U.S. (shorter than the apparent 7 or 8 years identified in the statute), and still be a “long-term resident” per IRC Section 877 (e)(2) depending upon the facts of any particular case.
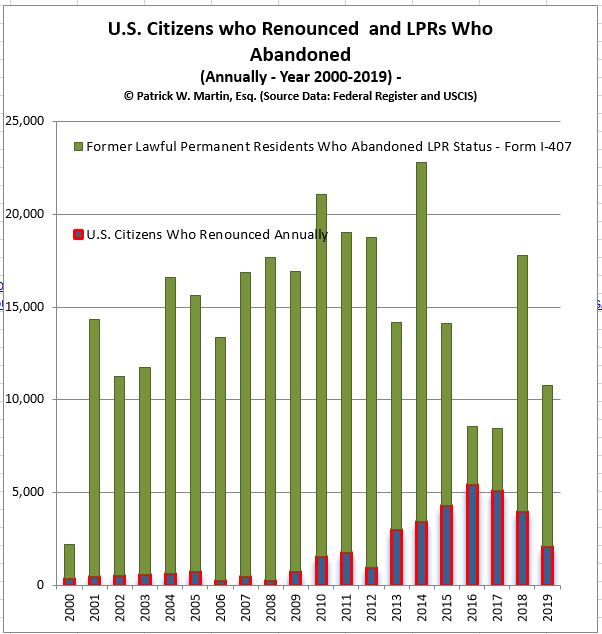
There are far more LPRs who abandon their status (formally) than U.S. citizens who formally take the oath of renunciation. See the table above reflecting those who have formally renounced U.S. citizenship versus those who have formally abandoned their LPR status.
Plenty of LPRs informally abandon their LPR status for immigration purposes by moving and living permanently outside the U.S.
There are plenty of timing issues for LPRs surrounding how and when they have “abandoned” their LPR status for purposes of IRC Section 877 (e)(2). See –
* More Green Card Holders Abandon Status Than Citizens Renounce Citizenship
A frequently overlooked fact is that:
Formal Abandonment of LPR Status Is More Common Than Citizenship Renunciation
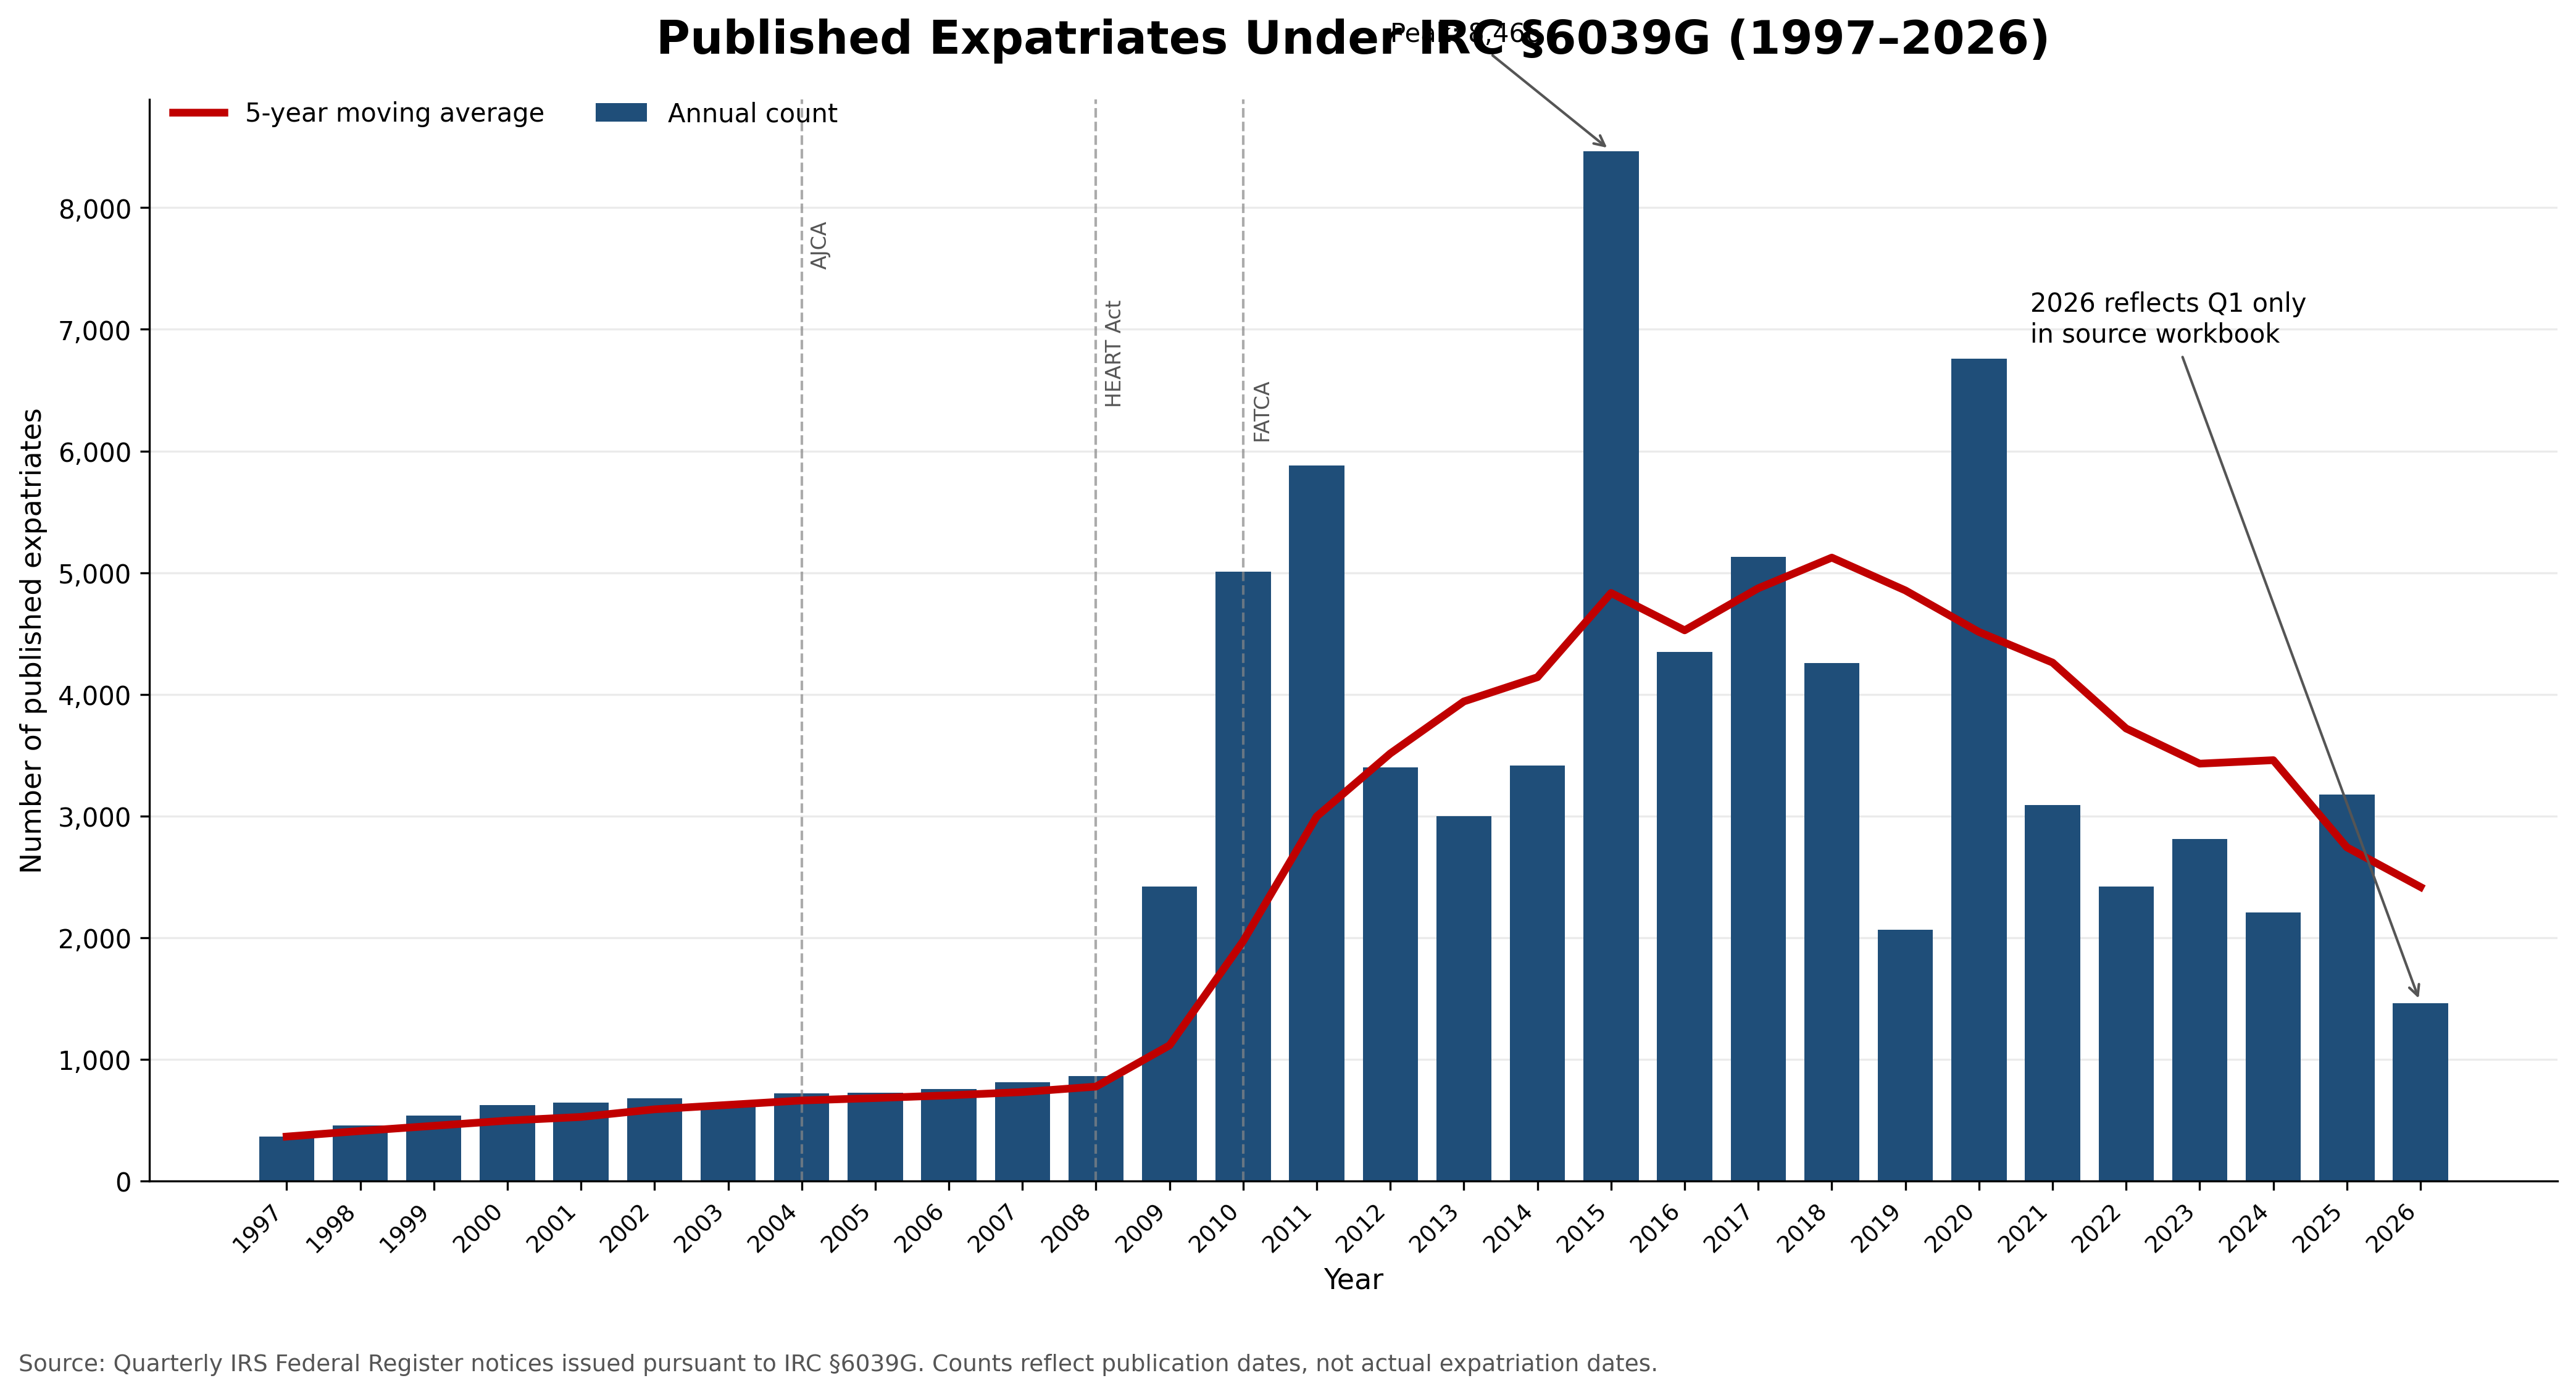
Each year, substantially more lawful permanent residents formally abandon their green cards than U.S. citizens formally renounce citizenship. The focus in the press and media is typically U.S. citizens who formally renounce. Here is my most recently compiled graph, the total number of U.S. citizens renouncing is typically in the thousands (few) each year. It has trended downward post-COVID.
However, with LPRs, formal recognition of abandonment by filing Form I-407 (not including informal abandonments which are multiple times greater) is multiple times greater.
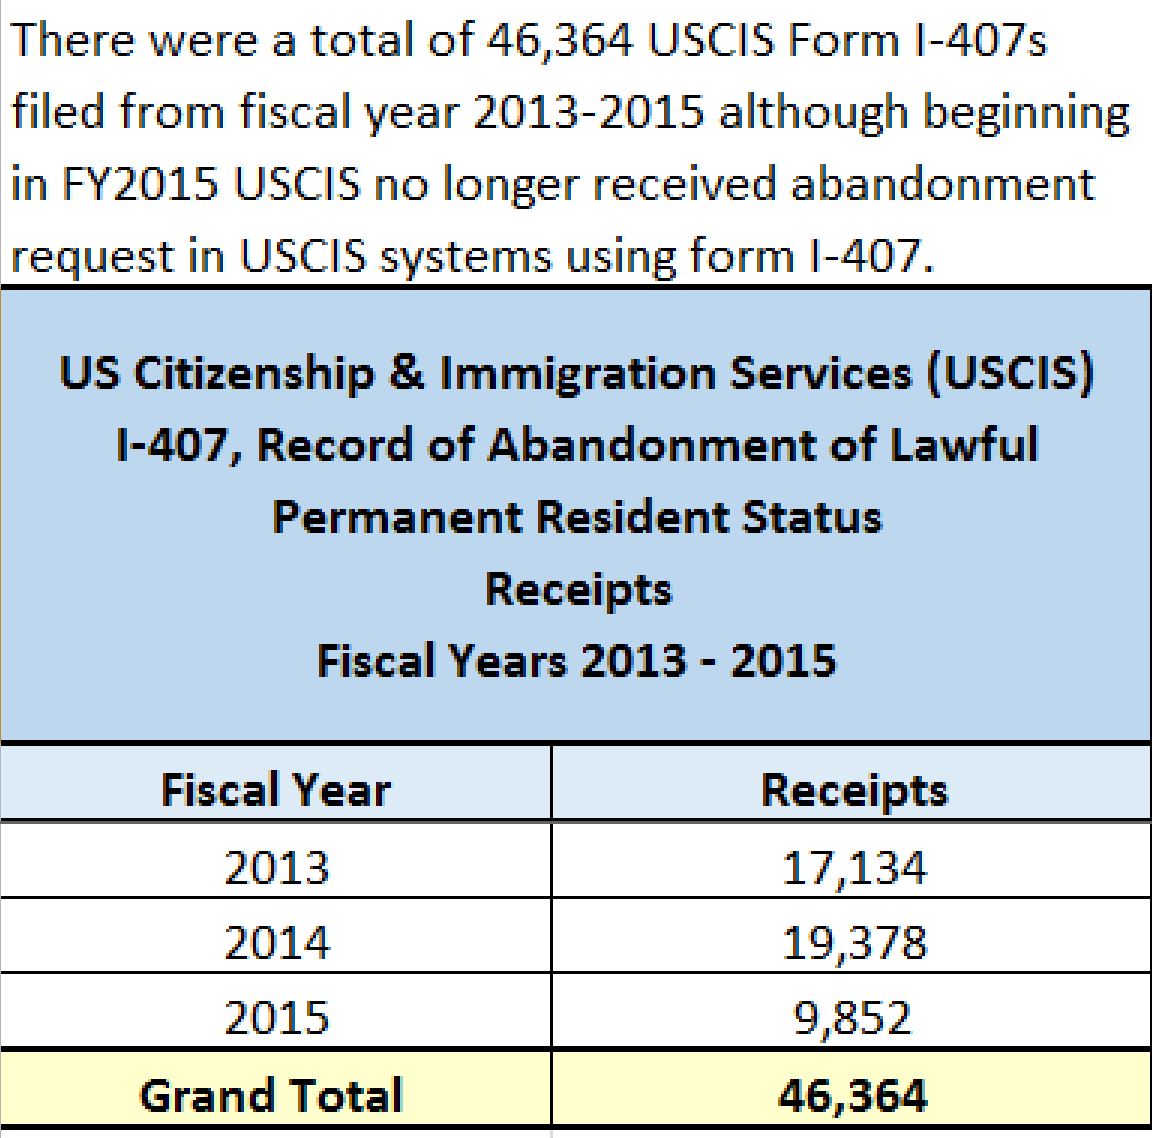
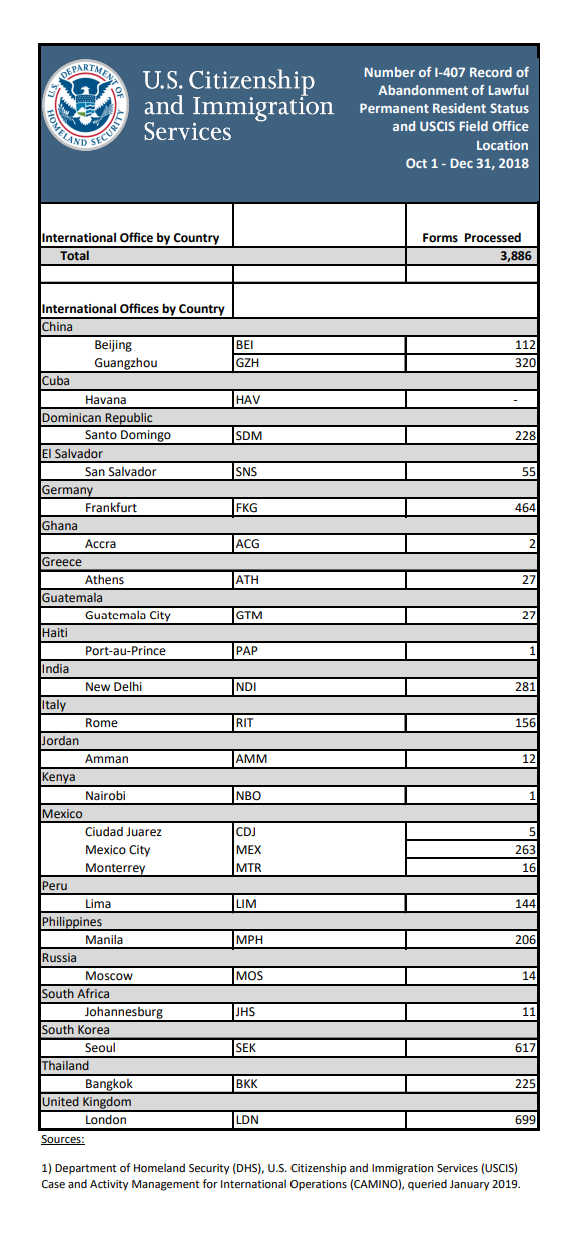
The graph I created several years ago, shows that formal LPR abandonments are mlutiple times greater than citizenship renunciation. I made a FOIA request with the government to request information about the number USCIS Forms I-407 that are filed with the government. See, also quarterly statistics of the USCIS – Form I-407, Record of Abandonment of Lawful Permanent Resident Status (partial information for years 2016-2019).
I have made a new FOIA request for more recent records, since this data is no longer public after the year 2019 year.
The statistics reflected above demonstrate that:
Formal green card abandonment significantly exceeds formal citizenship renunciations.
The population potentially affected by the expatriation rules is therefore much larger than many individuals around the world appreciate.
Lack of Control Over the Timing of Termination
One of the greatest risks for green card holders is that they often do not control the legal date on which their LPR status terminates, especially if they reside in a tax treaty country, per the analysis in the landmark case:
If abandonment is later determined by tax treaty law, effectively an CPB officer, the Executive Office for Immigration Review (EOIR) immigration court, the Board of Immigration Appeals (BIA)or a even a Federal District Court:
The taxpayer may not control the effective date of termination – “expatriation”.
If they are a “covered expatriate” or not.
The tax consequences may arise unexpectedly.
The timing can directly impact whether the tax expatriation rules apply and all of the potential consequences.
These timing issues become important when the IRS challenges tax positions taken on tax returns filed (or filed late) as was the case in Topsnik v. Commissioner (143 T.C. 240 (2014) – “Topsnik I”) and the subsequent case of Topsnik v. Commissioner (146 T.C. No. 1, 2016) – “Topsnik II”). In Topsnik II, Judge Kerrigan agreed with the IRS and ” . . . determined that P [taxpayer] was a “covered expatriate” who expatriated in 2010 and must recognize gain on the deemed sale of his installment obligation on the day before his expatriation under I.R.C. sec. 877A.” The U.S. Tax Court cited IRS Notice 2009-85 and explained it was not legally binding as follows:
We are not bound by Notice 2009-85, supra, see Compaq Computer Corp. v. Commissioner, 113 T.C. 363, 372 (1999), but it is an official statement of the Commissioner’s position and we may let it persuade us, see Nationalist Movement v. Commissioner, 102 T.C. 558, 583 (1994), aff’d, 37 F.3d 216 (5th Cir.1994).
The Tax Court went on to conclude these facts caused the court to conclude and uphold the IRS assessment of the “exit tax” on the German citizen Mr. Topsnik as a “covered expatriate” quoted as follows:
Notice 2009-85, sec. 8, 2009-45 I.R.B. at 611, explains that for purposes of certifying tax compliance for the five years before expatriation pursuant to section 877(a)(2)(C):
All U.S. citizens who relinquish their U.S. citizenship and all long-term residents who cease to be lawful permanent residents of the United States (within the meaning of section 7701(b)(6)) must file Form 8854 in order to certify, under penalties of perjury, that they have been in compliance with all federal tax laws during the five years preceding the year of expatriation. Individuals who fail to make such certification will be treated as covered expatriates within the meaning of section 877A(g) * * *
For the year of his expatriation petitioner failed to complete and file a Form 8854 certifying under penalties of perjury that he has complied with all of his U.S. Federal tax obligations for the five taxable years preceding the taxable year that includes his expatriation date. Respondent [IRS] has provided evidence that petitioner did not file all of his U.S. income tax returns before expatriatingand was not in payment compliance for taxes owed for the five years before expatriation in taxable year 2010. Thus petitioner could not have certified under penalties of perjury on a Form 8854 that he had been in tax compliance for the five years before expatriation. Consequently, because petitioner failed to certify tax compliance for the five years before expatriation, he is a “covered expatriate” as defined by section 877A(g)(1)(A).
Importantly, the court in Aroeste concluded IRS Form 8854 was not required to be filed (even though the DOJ attorney argued it was required – as set forth in the instructions to the form) as explained below:
C. Whether Aroeste Was Required to File Form 8854
The Government next argues that even if the IRS had accepted Aroeste’s amended
returns, neither amended return would have properly notified the IRS of a commencement of treaty benefits because both failed to attach Form 8854, as required by IRS Notice 2009- 85.(Doc. No. 76-1 at 4–5.) The Government concedes Aroeste attached Form 8833 to both
amended forms. (Id.)
Aroeste responds that Notice 2009-85 is not binding authority as it fails to comply
with the Administrative Procedures Act (“APA”). (Doc. No. 78-1 at 8 (citing Green Valley
Investors, LLC v. Comm’r of Internal Revenue, 159 T.C. No. 5, at *4 (Nov. 9, 2022)) (under
the APA, agencies must follow a three-step procedure for “notice-and-comment”
rulemaking, but this requirement does not apply to “interpretive rules, general statements
of policy, or rules of agency organization, procedure, or practice.”).) The Court agrees. In
Mann Construction, Inc. v. United States, 27 F.4th 1138 (6th Cir. 2022), the court found
that Notice 2007-83 failed to comply with the APA’s notice-and-comment procedure.
Similarly here, because Notice 2009-85 has not been subject to a notice-and-comment procedure, it does not comply with the APA and thus is not binding. As such, Aroeste was not required to file Form 8854 with his amended returns.
Both the Green Valley Investors LLC case and Mann Construction were 2022 cases, some 6 years after Topsnik II.
My law firm, Chamberlain Hrdlicka, successfully represented the taxpayers in Green Valley and of course in Aroeste.
Practical Lessons for Green Card Holders
The combined lessons from Aroeste, Topsnik I, and Topsnik II are significant.
Before Obtaining a Green Card
Individuals should understand:
The long-term resident rules and their U.S. tax obligations and reporting obligations;
The expatriation tax provisions and how they generally apply;
The “covered expatriate” tax regime and what steps to take;
The impact of income tax treaties with countries in the United States.
Before Formally Reporting the Abandonment (or Informally Abandoning) a Green Card
Individuals should carefully evaluate:
The date expatriation may occur;
Whether Form I-407 should be filed;
Tax compliance under U.S. tax laws (and what that means), including for the preceding five years to abandonment;
What notifications should be provided and when (not necessarily formal tax form filings);
Potential exit tax exposure – depending upon total assets, liabilities, type of assets and anticipated future income and gains;
Treaty residency positions and the particular facts of each case;
Reporting obligations, and which ones are mandatory or not – including IRS Forms 8833 and 8854.
Most Important Takeaway?
A green card holder does not necessarily need to spend seven or eight years physically living in the United States before becoming subject to the long-term resident and expatriation tax rules. The interaction of immigration law, tax law, treaty provisions, and reporting requirements can produce unexpected results. The recent landmark decision in Aroeste that I handled, confirms that these issues are not merely theoretical—they are increasingly becoming the subject of significant litigation and judicial scrutiny.
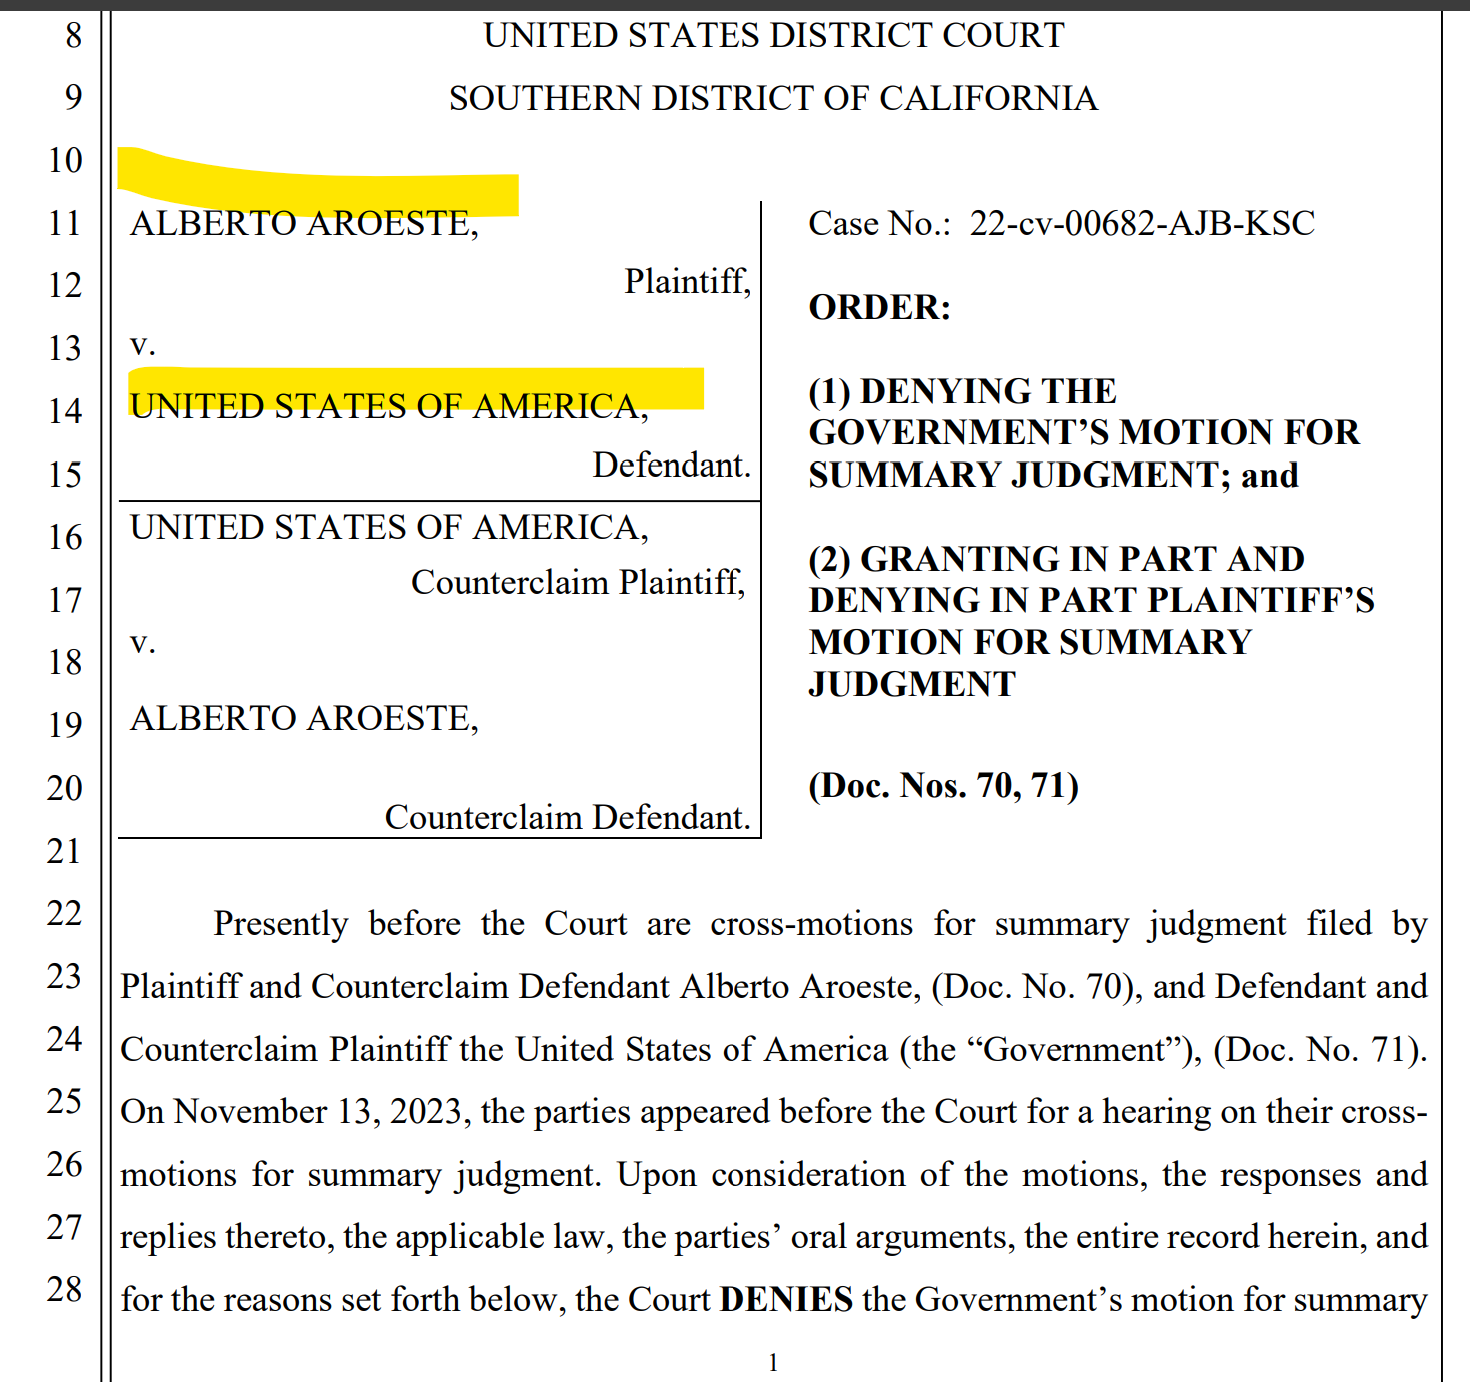
Many individuals have no idea that, under the legal principles confirmed in the federal district court case I litigated — Aroeste v United States, 22-cv-00682-AJB-KSC (20 Nov. 2023) – they may already be treated as “covered expatriates” as a matter of law.
Along Comes Section 2801 – and 2025 Final Regulations – The “Forever Taint” to Family and Friends (Paying the Taxman)
Aroeste – Landmark Decision Confirms the Law – Tax Treaty Law Applies – Taxpayers Do Not Waive Benefits per Gov’t
These writings all addressed the same underlying legal and policy expectations that courts would eventually be required to confront — issues now directly addressed in Aroeste. The Aroestedecision is also consistent with positions I successfully advanced in three separate U.S. Tax Court cases involving green card holders, none of which resulted in published opinions because the government ultimately conceded to my arguments and my clients prevailed prior to trial.
This case law has great impact on green card holders who are living principally outside of the U.S. There are 3.88 million individuals who are living outside the U.S. – per the 2024 report by the U.S. federal government. Many of them live in a treaty country. Many of these individuals might be considering their immigration law consequences (particularly after the latest announcement from the USCIS – impact these immigration consequences: U.S. Citizenship and Immigration Services Will Grant ‘Adjustment of Status’ Only in Extraordinary Circumstances (May 2026) Few have considered the tax law implications.
Most important Questions for “Green Card” Holders (“lawful permanent residents”): Part I of VI
Those individuals who have green cards and live in and outside of the United States, should understand the tax and legal implications to them.
There are millions of individuals in this category. i.e., those who have “emigrated” with an “e” from the United States. There are 3.88 million of these green card holders, as of 2024 according to the U.S. federal government’s latest report. The statistics are striking – that so many individuals reside outside the U.S.
These nearly 4 million individuals who do not reside principally in the U.S. are similar to the fact pattern of Mr. Aroeste residing in Mexico City. See the case where yours truly, Patrick W. Martin, was lead counsel in that landmark case – and the analysis of the District Court in Aroeste v. United States. The government lost.
Today’s post is a series of simple and key questions for those with green cards, to help them better hone in on the legal issues and U.S. tax risks that may be applicable to them:
Am I still a U.S. taxpayer?
What does it mean to be a U.S. taxpayer, when there are technical tax terms such as “United States person” and an individual who is a “lawful permanent resident” (not defined in the immigration law)?
I have a green card but I’ve lived outside the U.S. for years — do I still have to file U.S. tax returns?
The date on my physical green card has expired – does that mean I am no longer a a “lawful permanent resident” for tax purposes?
Does it matter whether my green card is expired, taken back at the airport, or just sitting in a drawer overseas?
Is there a difference between “giving up” my green card and just letting it lapse?
Aroeste v. United States — what does it mean for me? –
Why are all of the above questions so important to me – since I previously obtained a “green card”?
Subsequent posts will address additional key questions that can have a significant legal consequence to individuals who had or have a green card and spend substantial time outside of the United States. For a preview, look at Oops.. .Did I Expatriate and Never Know It – International Tax Journal 2014










 Many individuals have no idea that, under the legal principles confirmed in the federal district court case I litigated —