International Tax · Citizenship Renunciation · LPR Abandonment
International Tax Shareholder
FAQs re: Tax Expatriation: Aroeste v. United States Impact – Frequently Asked Questions
The U.S. tax law is complicated generally. It gets really complex when you renounce your United States citizenship or you cease to be a “lawful permanent resident” as that term is technically defined in the U.S. federal tax law. The comments in Tax-Expatriation.com are designed to help demystify some of this complexity.
Hence, posts addressing various FAQs – for those who have or “had” a “green card” – please see the following:
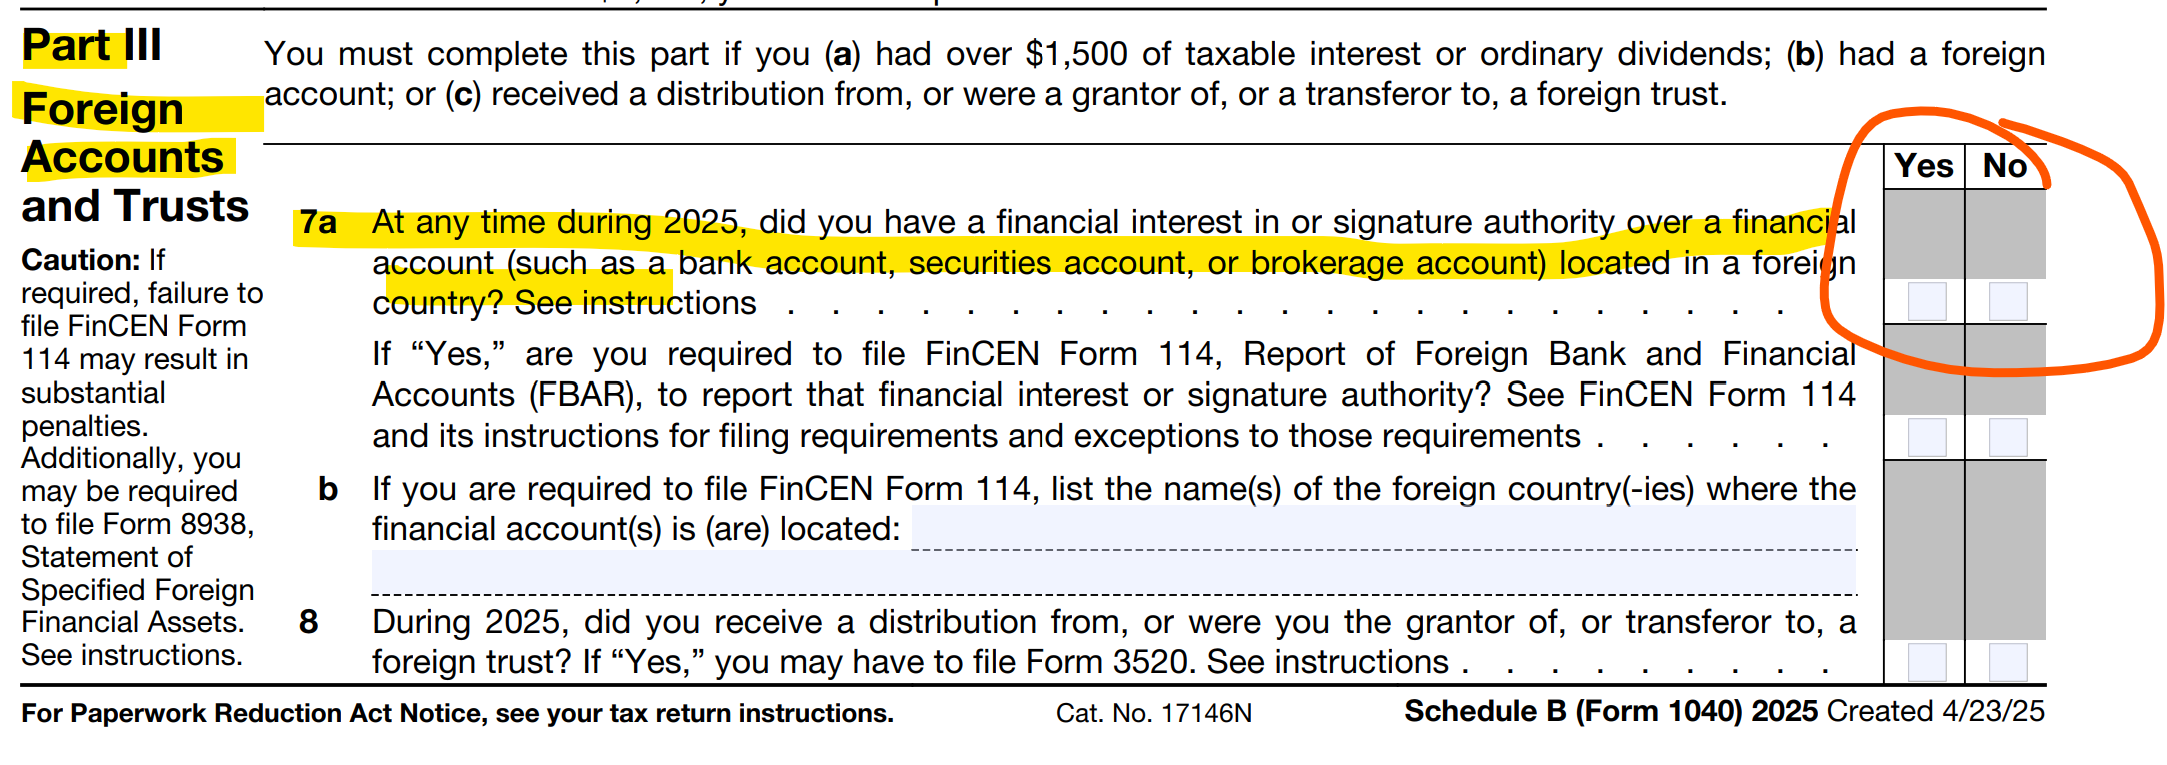
“Delinquent FBAR Filing Procedures”: The IRS Webpage Is Gone, but the Real Questions Remain
“Delinquent FBAR Filing Procedures”
There has been considerable commentary—and some concern—about the IRS’s removal, around the end of June 2026, of its longstanding webpage titled “Delinquent FBAR Filing Procedures.” The IRS originally created those procedures in 2014.
The disappearance of the webpage is noteworthy. But it may not be nearly as important as some commentators suggest.
TIGTA report: $157 Billion of Potentially Unreported Foreign Accounts?
As the TIGTA reports: “Foreign financial institutions (FFI) are required to File IRS Form 8966, FATCA Report, to report information about financial accounts in which U.S. taxpayers hold certain ‘ownership interests.'”
TIGTA noted that foreign financial institutions report U.S.-owned financial accounts to the IRS on Form 8966, FATCA Report, while U.S. taxpayers separately report specified foreign financial assets on Form 8938. The disparity identified by TIGTA was enormous.
For 2017 and 2018, taxpayers reported (on their IRS Form 8938) approximately $6.6 billion and $15.9 billion, respectively, while foreign financial institutions reported (on IRS Form 8966) approximately $106.8 billion and $173.0 billion.
From these figures, TIGTA concluded that the data indicated potential unreported or underreported foreign bank-account values of approximately $157 billion.
That conclusion deserves considerable skepticism. Among other questions: how many of those reported foreign assets belong to lawful permanent residents—“green card” holders—who actually reside overseas and may qualify as residents of a treaty country under an applicable U.S. income tax treaty?
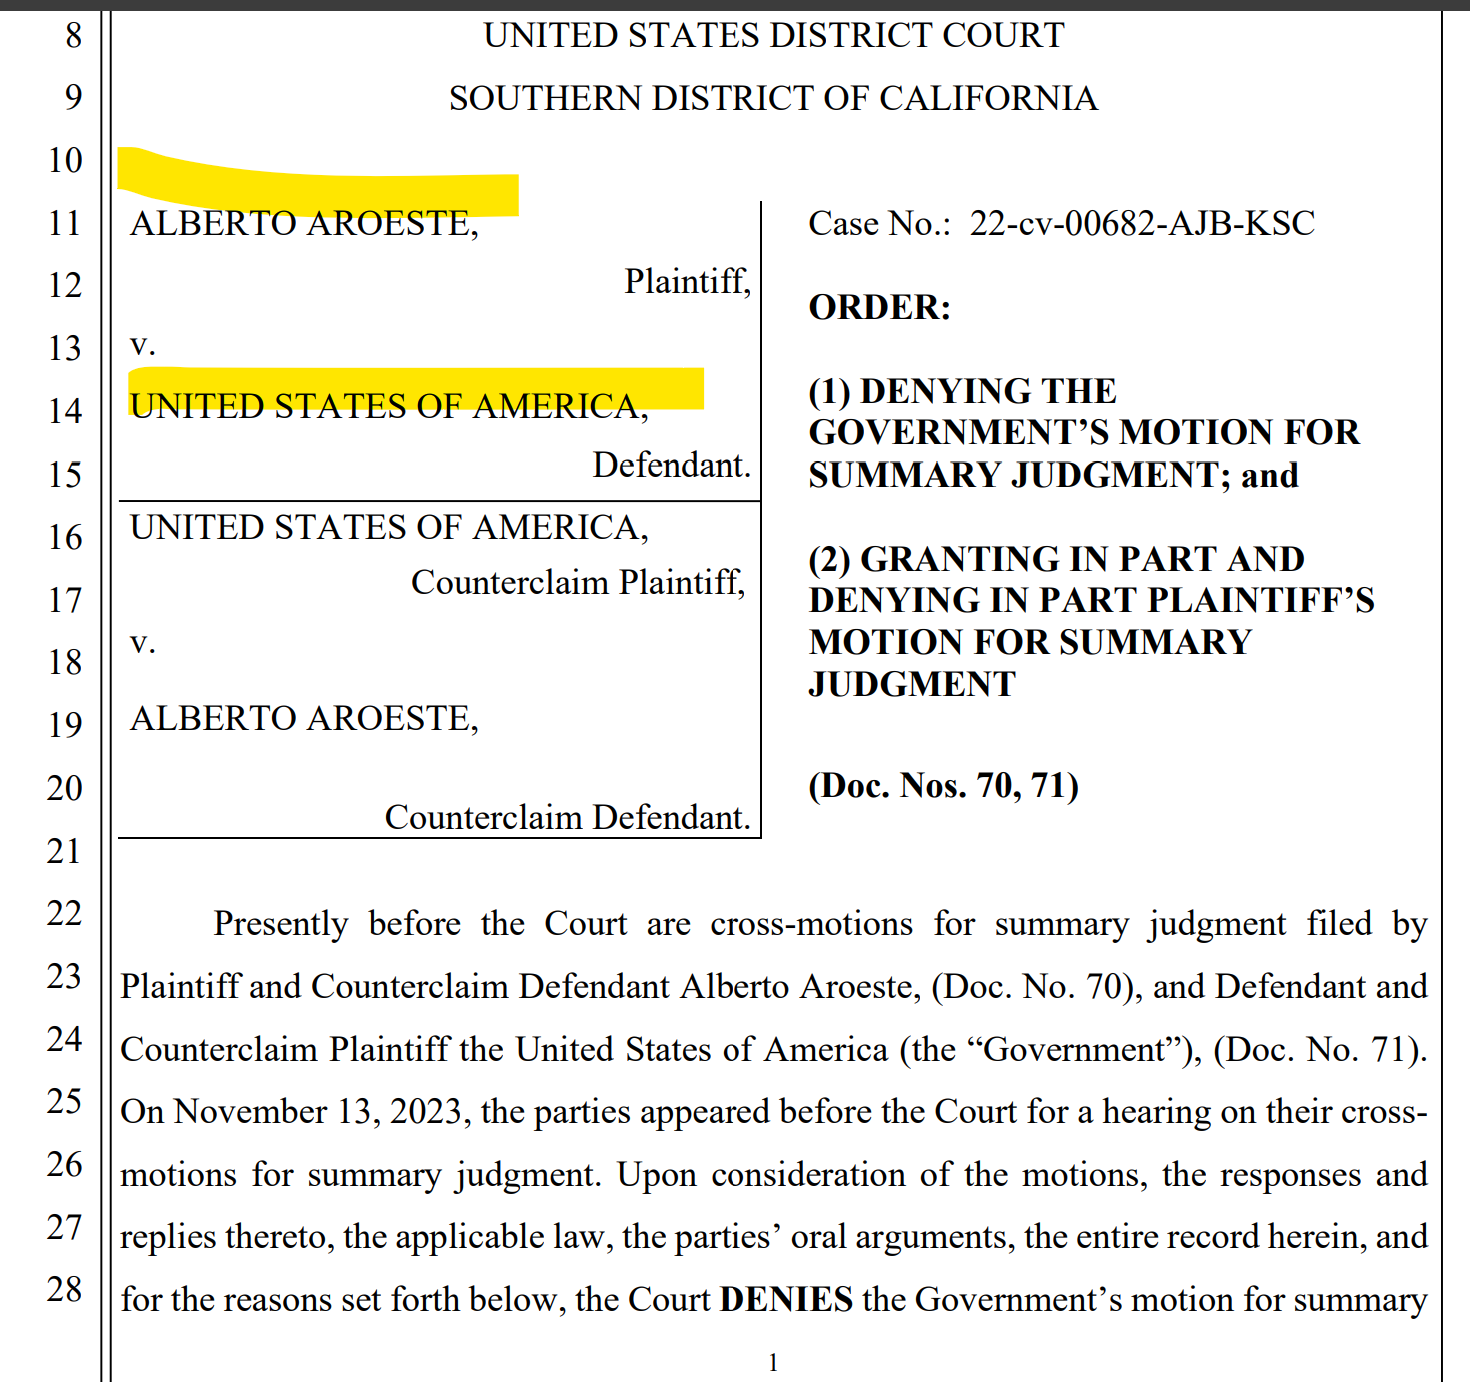
That was precisely the type of residency issue presented in my case of Aroeste v. United States, Case No. 22-cv-00682-AJB-KSC (S.D. Cal. 2023).
Account holders and their advisors nevertheless have good reason to take FBAR exposure seriously. Federal courts have increasingly accepted a relatively low threshold for establishing a “willful” FBAR violation. The government generally needs to prove its civil FBAR case only by a preponderance of the evidence, and courts have repeatedly held that willfulness can include recklessness or willful blindness, rather than requiring proof that the taxpayer deliberately intended to violate the FBAR statute.
See, among others, United States v. Reyes (2d Cir. 2026); Bedrosian (3d Cir.); Horowitz (4th Cir.); Kelly (6th Cir.); Rum and Schwarzbaum (11th Cir.); and Norman and Kimble (Federal Circuit).
That is where the real concern lies, not simply in the disappearance of an IRS webpage.
The IRS Removed the Webpage—Not Its Internal Guidance in the IRM (the IRS’ “Bible”)
The IRS removed the public-facing “Delinquent FBAR Filing Procedures” webpage, but the same guidance remains in the Internal Revenue Manual (IRM) to still encourage late filed FBAR filings. The same language is found in the IRM, which is the most important since revenue agents and managers “are responsible for adhering to the content of this IRM”. See, IRM 4.26.16.1(i).
The IRM continues to provide that an FBAR penalty should not be imposed when:
the violation was due to reasonable cause; and
accurate delinquent or amended FBARs are filed to correct the prior violations.
The critical point is that filing a delinquent FBAR does not itself establish reasonable cause or eliminate a potential penalty, but notification of the government is required if you go down this path.
IRM 4.26.16.3.11 continues to describe the delinquent FBAR filing procedures. Among other things, it instructs taxpayers to file delinquent FBARs electronically, using the instructions applicable to the year being reported, and to provide the reason why the FBAR was filed late.
Most importantly, the IRM states that a penalty will not be asserted for an account “if it is determined” that:
the failure was not willful;
the failure was due to reasonable cause; and
the account was properly reported on the delinquent FBAR.
The words “if it is determined” are crucial. Who makes that determination? See my case of Jones v. United States, No. 19-CV-4950 (C.D. Cal. 2020), as a cautionary tale.
Ultimately, the IRS makes this determination which starts the government machinery running. Its not the account holder, the person with signature authority, or the taxpayer’s advisor; no matter how convinced they are of their reasonable cause and their facts.
The More Important Question (Implied Above): Should You File a Late FBAR at All?
This is the question that deserves considerably more attention.
Whether someone should file a delinquent FBAR depends entirely upon the person’s particular facts and circumstances. Filing late is not automatically the safest course.
One of the most important considerations is the six-year FBAR statute of limitations under 31 U.S.C. § 5321(b)(1). That limitation period is fundamentally different from certain Title 26 international information-reporting rules, where the assessment period can remain open under IRC § 6501(c)(8).
Accordingly, before filing a delinquent FBAR, an account holder should understand at least two competing questions:
What are the consequences of filing late?
What are the consequences of not filing at all?
Those questions cannot responsibly be answered without examining the particular years involved, when the six-year limitations period expires, the underlying income-tax filings, what the taxpayer knew, all of the surrounding facts, what advice was received, and whether the government might characterize the conduct as willful or reckless.
Bittner Changed the Economics of FBAR Enforcement
The Supreme Court’s decision in Bittner v. United States, 598 U.S. 85 (2023), significantly changed the strategic landscape.
The Court held that the non-willful FBAR penalty applies on a per-report, rather than per-account, basis. That substantially reduced the government’s potential penalties in all non-willful cases involving numerous foreign accounts.
As a practical matter, Bittner also changed the economics of FBAR enforcement. I had the privilege of working on the ACTEC amicus brief filed in Bittner – which was cited in both the majority opinion by Justice Gorsuch and the dissent by Justice Barrett – See Brief for American College of Trust and Estate Counsel as Amicus Curiae 5–7.
In my view, the IRS now has a greater incentive to focus its enforcement resources on cases in which it believes it can establish willfulness through reckless disregard or willful blindness, thereby potentially supporting the much larger willful FBAR penalty.
These Are the IRS’s Own Rules
It is also important to distinguish the statute from the IRS’s administrative procedures.
I sometimes refer to these as the IRS’s “Monopoly rules.” They are the government’s administrative rules for handling delinquent FBARs; they are not themselves statutory safe harbors enacted by Congress.
That distinction matters.
The IRM says a penalty will not be asserted “if it is determined” that reasonable cause exists and the other requirements are satisfied. But “reasonable cause” is not defined in the FBAR statute itself, Title 31.
Instead, courts and the government have borrowed concepts developed under Title 26, including the Supreme Court’s familiar “ordinary business care and prudence” standard. See United States v. Boyle, 469 U.S. 241 (1985); see also Moore v. United States, No. C13-2063RAJ (W.D. Wash. 2015), and United States v. Ott, No. 2:18-cv-12174 (E.D. Mich. 2019).
Filing Late Does Not Erase the Original Violation
This point is sometimes overlooked.
Once an FBAR filing deadline has passed without the required report being filed, subsequently filing the FBAR does not somehow erase the historical failure.
The water has already passed under the bridge.
A delinquent filing may become highly relevant to reasonable cause, mitigation, cooperation, and the government’s ultimate enforcement decision. But it does not make the original failure disappear.
Moore provides an important cautionary example. An even more dramatic example arose in Jones v. United States, No. 19-CV-4950 (C.D. Cal. 2020), a case I represented as we prepared for a jury trial during the COVID period.
Mrs. Jones, an elderly widow, and her late husband’s estate challenged approximately $3.4 million in willful FBAR penalties. She had affirmatively disclosed her late filings to the IRS through the streamlined process after filing the delinquent FBARs. The government nevertheless pursued a willfulness theory based substantially on willful blindness.
The government argued willful blindness and Mrs. Jones (90+ years of age), ironically, was legally blind by the time the case was set to go to trial.
That is one reason the facts surrounding preparation and signing of the income-tax return can become just as important as the FBAR itself.
The lesson is important: coming forward and filing late does not itself immunize an account holder from an FBAR penalty examination. It does not mean a revenue agent will come to the right result based upon the facts of your case. It can be a bit like the lottery.
“Reasonable Cause” May Not Mean What You Think
What does it take for the IRS to conclude that reasonable cause does not exist?
Sometimes, not much.
A simple “mistake” or “oversight” does not necessarily constitute reasonable cause. The government generally looks for evidence that the person exercised ordinary business care and prudence but nevertheless could not comply.
Death, serious illness, destruction of records, fire, or natural disaster can support reasonable cause under appropriate circumstances. But even those facts do not automatically establish it.
Likewise, ignorance of the FBAR requirement ordinarily does not automatically establish reasonable cause. Even reliance on professional tax advice may be insufficient—particularly where the government contends that the advisor lacked appropriate international-tax expertise or that the taxpayer failed to provide the advisor with the relevant information.
The disappearance of the IRS webpage titled “Delinquent FBAR Filing Procedures” should not itself drive a taxpayer’s decision.
The underlying IRS guidance remains in the Internal Revenue Manual.
The much more important question is whether filing a delinquent FBAR is actually the appropriate strategy for the particular individual and the particular years involved.
That requires understanding the six-year FBAR statute of limitations, the taxpayer’s underlying filing history, the reason the FBAR was not timely filed, what the taxpayer knew, what professional advice was received, the information appearing on Schedule B and other returns, and the possibility that the government could characterize the conduct as reckless or willful.
Once a delinquent FBAR is filed, the filing—and the taxpayer’s explanation for filing late—cannot simply be taken back.
So be thoughtful when someone recommends entering the “Delinquent FBAR Filing Procedures” for a low low fee of just US$**99.99.
Understand why you are filing, what you are saying to the government, what years remain open, and what consequences may follow.
Dive in with your eyes wide open – and make sure you can see the bottom before you jump.
IRS Removes Practice Unit from their Website – titled “Determining Tax Residency Status of Lawful Permanent Residents” – Post-Aroeste
The decision in Aroeste v. United States, continues to affect how U.S. tax treaty rules apply to green card holders. In Aroeste, the federal district court rejected important IRS-DOJ arguments concerning when a lawful permanent resident is not treated as a resident of the United States under an income tax treaty. I refer to the broader consequences of the case as the Aroeste Effect, which rears its head in proposed Treasury Regulations to be discussed for another day.
For years, the IRS Large Business and International Division (LB&I) published a Practice Unit titled Determining Tax Residency Status of Lawful Permanent Residents. Issued in 2013 and updated in 2014, it was used to help IRS personnel determine the U.S. tax residency of green card holders—the very subject litigated in Aroeste. That Practice Unit has now been removed from the IRS website.
The removal is notable because the IRS continues to publish other related international tax Practice Units. For example, its 2018 Practice Unit, remains available: Determining an Individual’s Residency for Treaty Purposes PDF This 2018 Practice Unit has not been updated to address Aroeste. Importantly, however, it does not repeat the government’s argument in Aroeste that a taxpayer can lose or waive treaty benefits by failing to timely “take” a treaty position. The district court rejected the government’s position on that issue.
The IRS has not publicly explained why it removed the Practice Unit specifically addressing lawful permanent residents. Nevertheless, its disappearance after Aroeste is significant. For green card holders living outside the United States, the practical issue is straightforward: holding a green card does not necessarily mean the individual must always be a “United States person” – i.e., a U.S. tax resident. An applicable tax treaty can change that result.
The intricacies of the law can be complex, depending upon the facts of each person. The IRS’s removal of its own Practice Unit on this subject is another noteworthy example of the Aroeste Effect.
A U.S. Immigration Officer Stops You at at the Airport – @ the Point of Entry (Demands your Green Card be Turned Over))
Being stopped, searched, interrogated or simply questioned by U.S. federal government agents can be intimidating. Especially, if you do not know your legal rights.
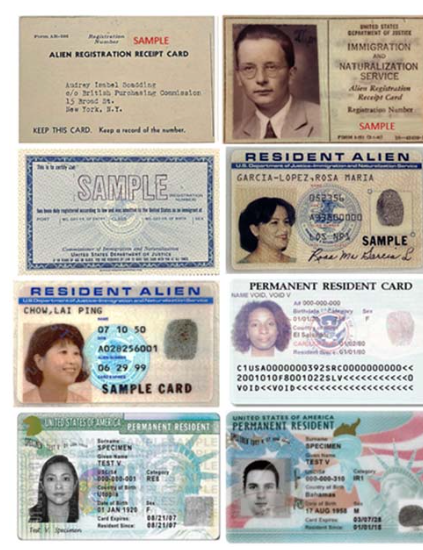
It can be more intimidating on your arrival to the U.S. airport, if the CBP officer (U.S. Customs and Border Protection) demands that you physically “return voluntarily” your green card. The consequences they tell you will be immediate deportation from the U.S.
Removal from the U.S. – is it voluntary or not, under these circumstances?
What are the U.S. federal tax consequences if you “return voluntarily” your green card?
What if the CBP officer pulls out Forms W-8s you previously signed with your foreign financial institution and presents them to you in the airport and asks the following questions:
Why did you certify “under penalty of perjury” you were not a United States person on your foreign bank produced documents (you received in France, Germany, the U.K., Canada, Mexico, Japan, Indonesia, Australia — or any other foreign country)?
The officer then asks for all of the envelopes and papers in your luggage and opens the letters and files in your possession – See, the U.S. Supreme Court decision United States v. Ramsey, 431 U.S. 606 (1977).
World Cup & Playing in the United States: Green Card Holders, the Treaty Tiebreaker, and the Global Athlete or Entertainer
As the world’s athletes have arrived to perform on U.S. soil, the U.S. tax system is a broad net. The 2026 FIFA World Cup—hosted across the United States, Mexico, and Canada—is a useful occasion to revisit a question that recurs every time a global athlete or entertainer steps onto a U.S. field, stage, or court: what does the United States get to tax, what forms govern the answer, and when does a visiting performer or athlete cross the line from nonresident into resident – including if they hold a lawful permanent resident card?
This blog is dedicated to issues of “tax expatriation” which crosses into different professions and global lifestyles. See, for instance the following prior blogs:
There are of course many famous athletes who were not U.S. citizens and then became green card holders and oftentimes then became naturalized U.S. citizens. Since the Knicks just won the NBA championship after 53 years, one of their greatest, Patrick (mi tocayo) Ewing left Jamaica as a boy, became a green card holder and then a naturalized citizen. A 1985 New York Times article, A Favorite Son Goes Home, describes his first return to the island since a boy.
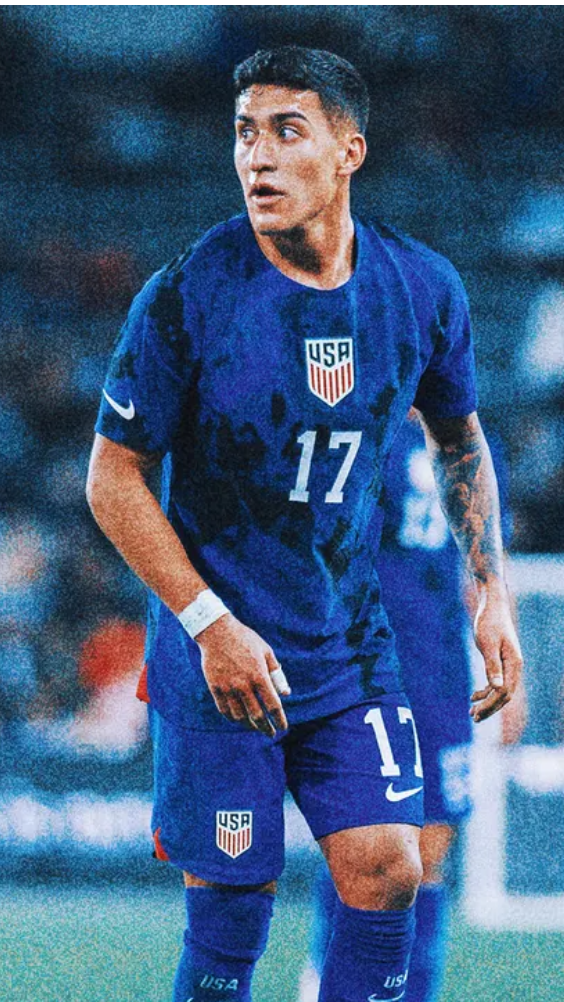
Soccer players, have moved all over the world and Alejandro Zendejas is a current U.S. World Cup player born in Ciudad Juarez, Chihuahua, Mexico, at the border who later obtained lawful permanent residency and also became a naturalized citizen. That means (as a result of his naturalized U.S. citizenship) if he were ever to renounce his U.S. citizenship, he would necessarily become a “covered expatriate” as defined in the tax statute.
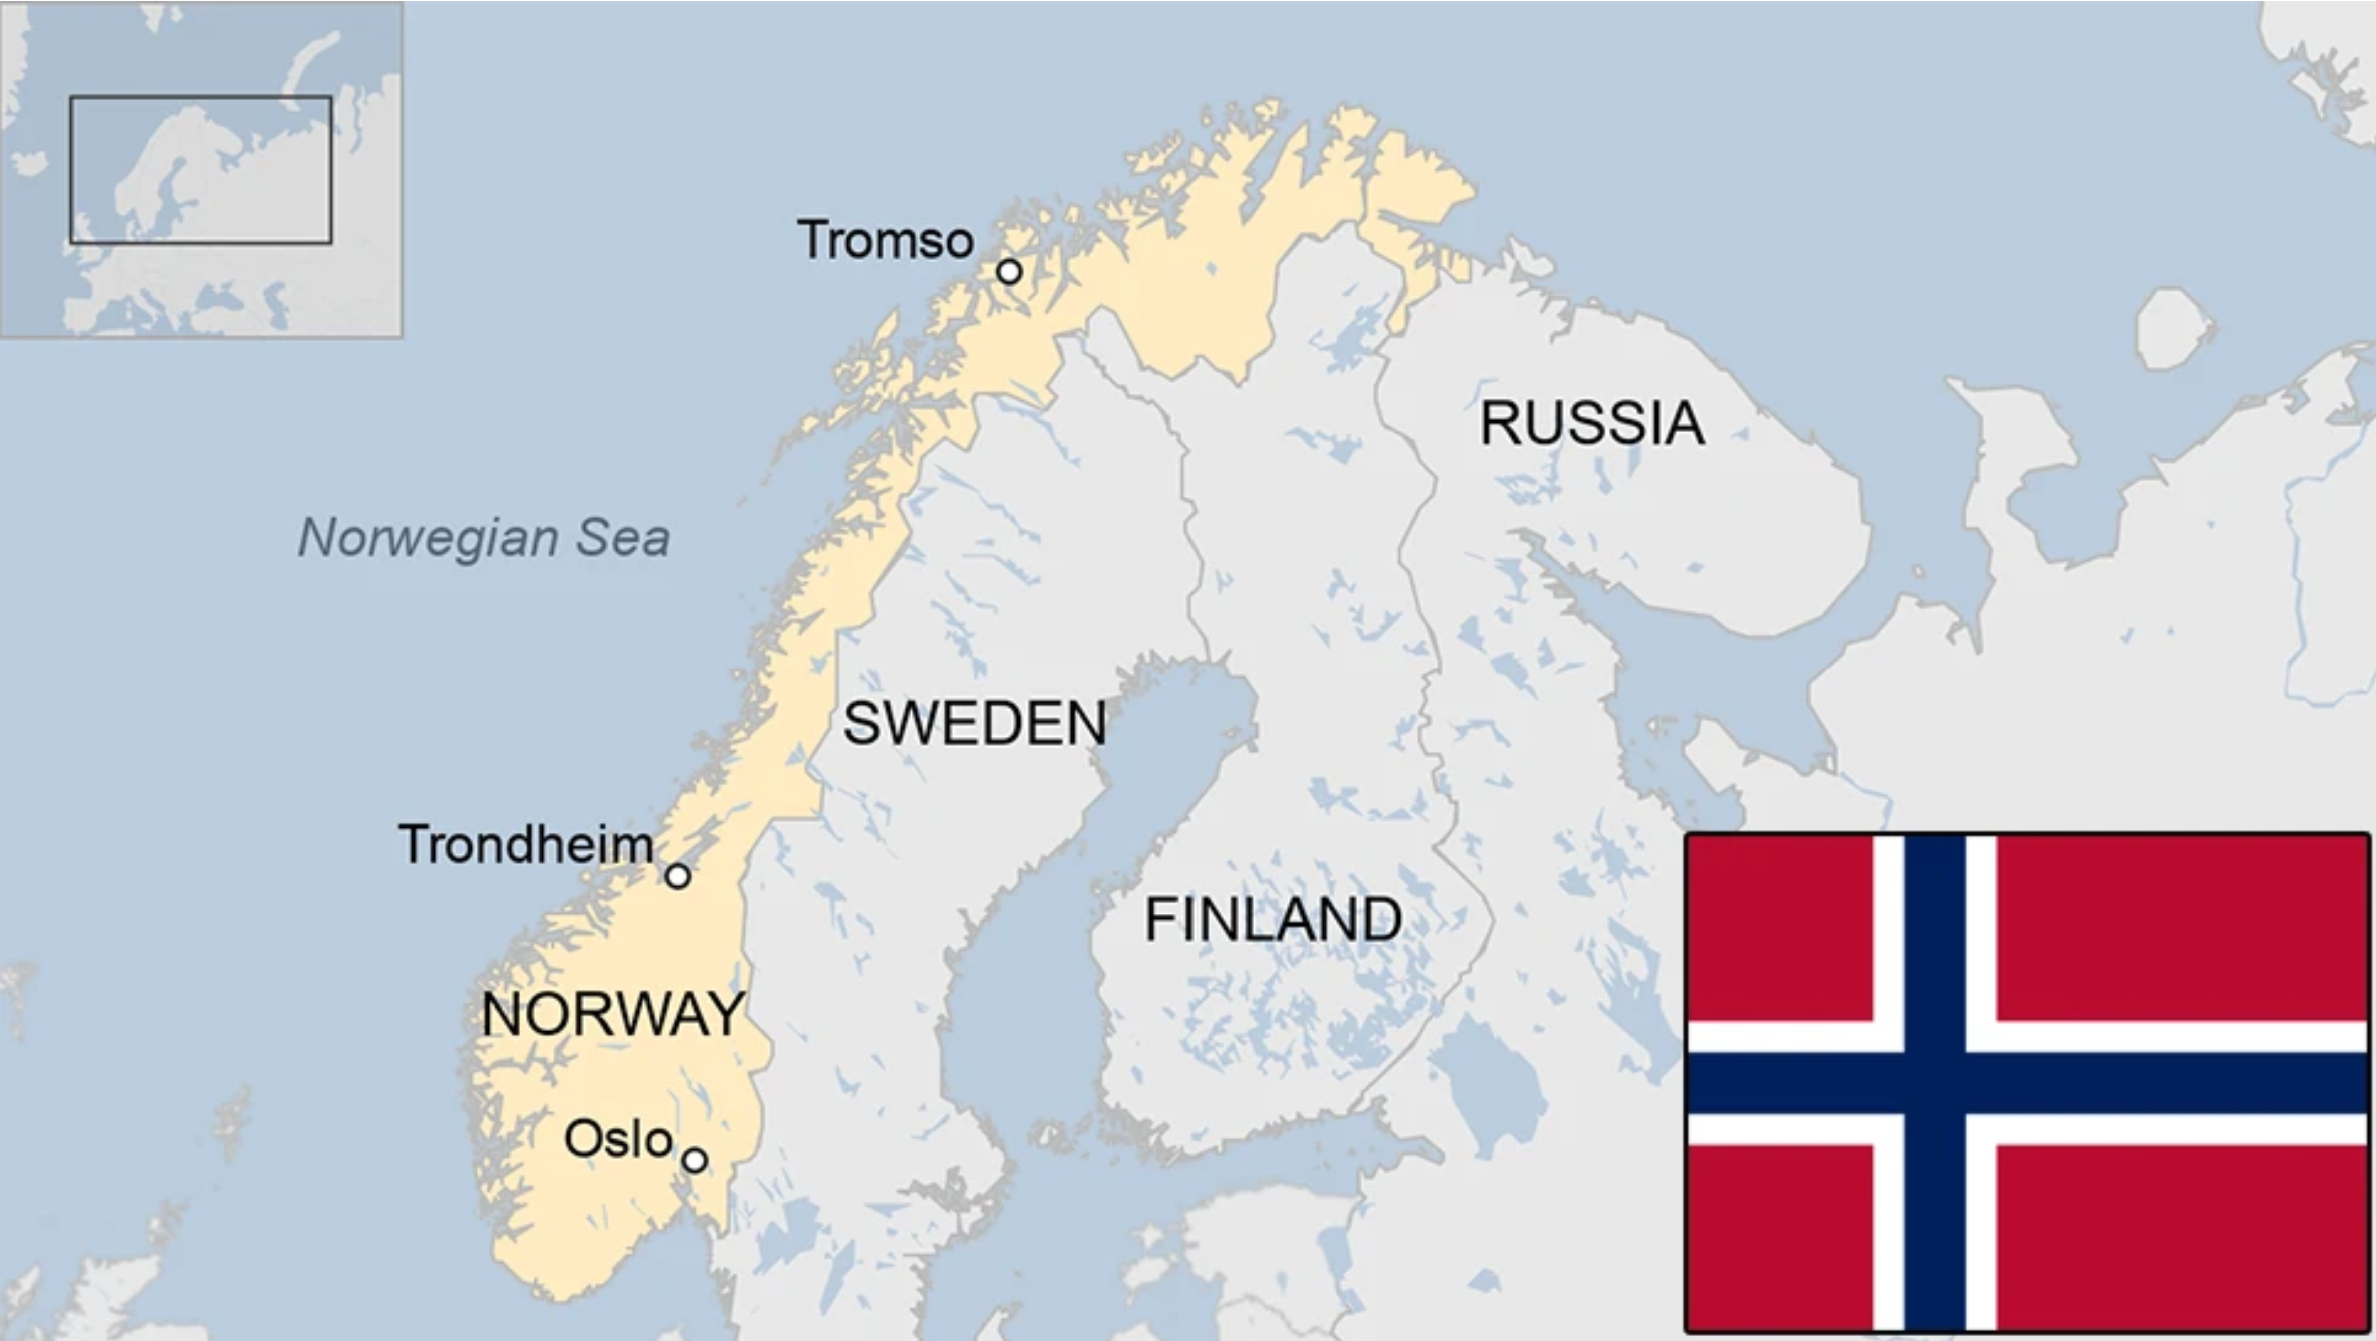
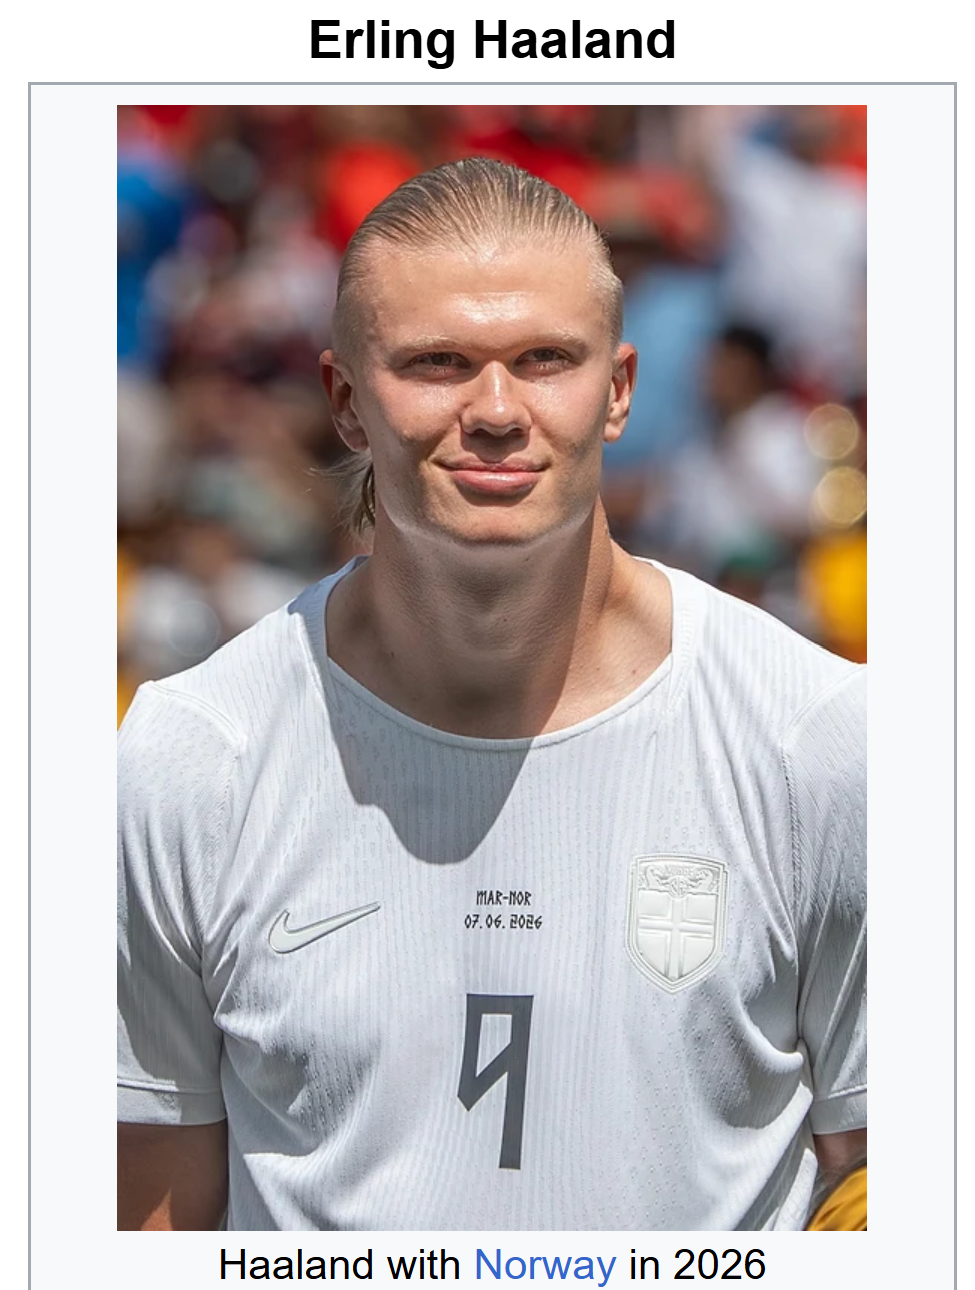
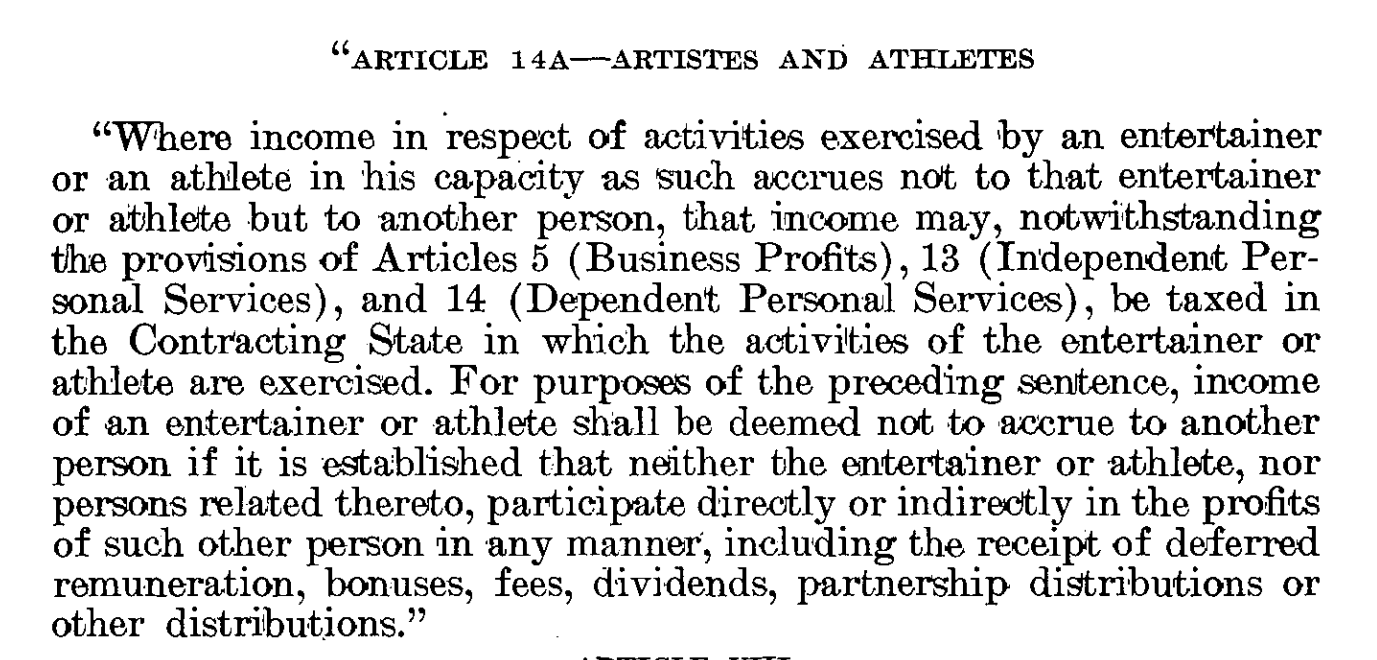
Athletes and entertainers are specially taxed in the U.S. in the sense they typically receive few benefits from the U.S. income tax treaty network. For instance, a world famous Norwegian soccer player such as Erling Haaland who has already equaled the Norwegian record (in just his first match) for most World Cup goals, previously belonging to midfielder Kjetil Rekdal is presumably subject to the U.S.-Norway treaty. The U.S.-Norwegian Income Tax Treaty is one of the very old tax treaties (1971) still on the books and has an “old fashioned” artist/entertainer/athlete provisions imbedded in the independent services provision that allows each government to specially tax artists and athletes if they earn over US$3,000.
A protocol to the treaty adopted in 1980 has a “new” article 14A specific to artists and athletes as reflected here in its entirety allowing the government to tax athletes and entertainers when they perform in the country (overriding other protective provisions of the treaty – e.g., Business Profits Art. 5, Independent Personal Services Art. 13 and Dependent Personal Services Art. 14):
The IRS also adopted a specific program, called the Central Withholding Agreement (“CWA”) program created by Revenue Procedure 89-47 specific to artists and athletes. I personally think it is a program that is not authorized by the statute and often applied by the IRS in a manner that violates the withholding tax regime we have in Chapter 3 of our statutory tax law, Subtitle A. In practice, third parties are subject to the 30% withholding tax on certain gross proceeds paid to companies other than the artist or athlete, if the athlete or artist doe not participate with the IRS in their CWA.
Mexico
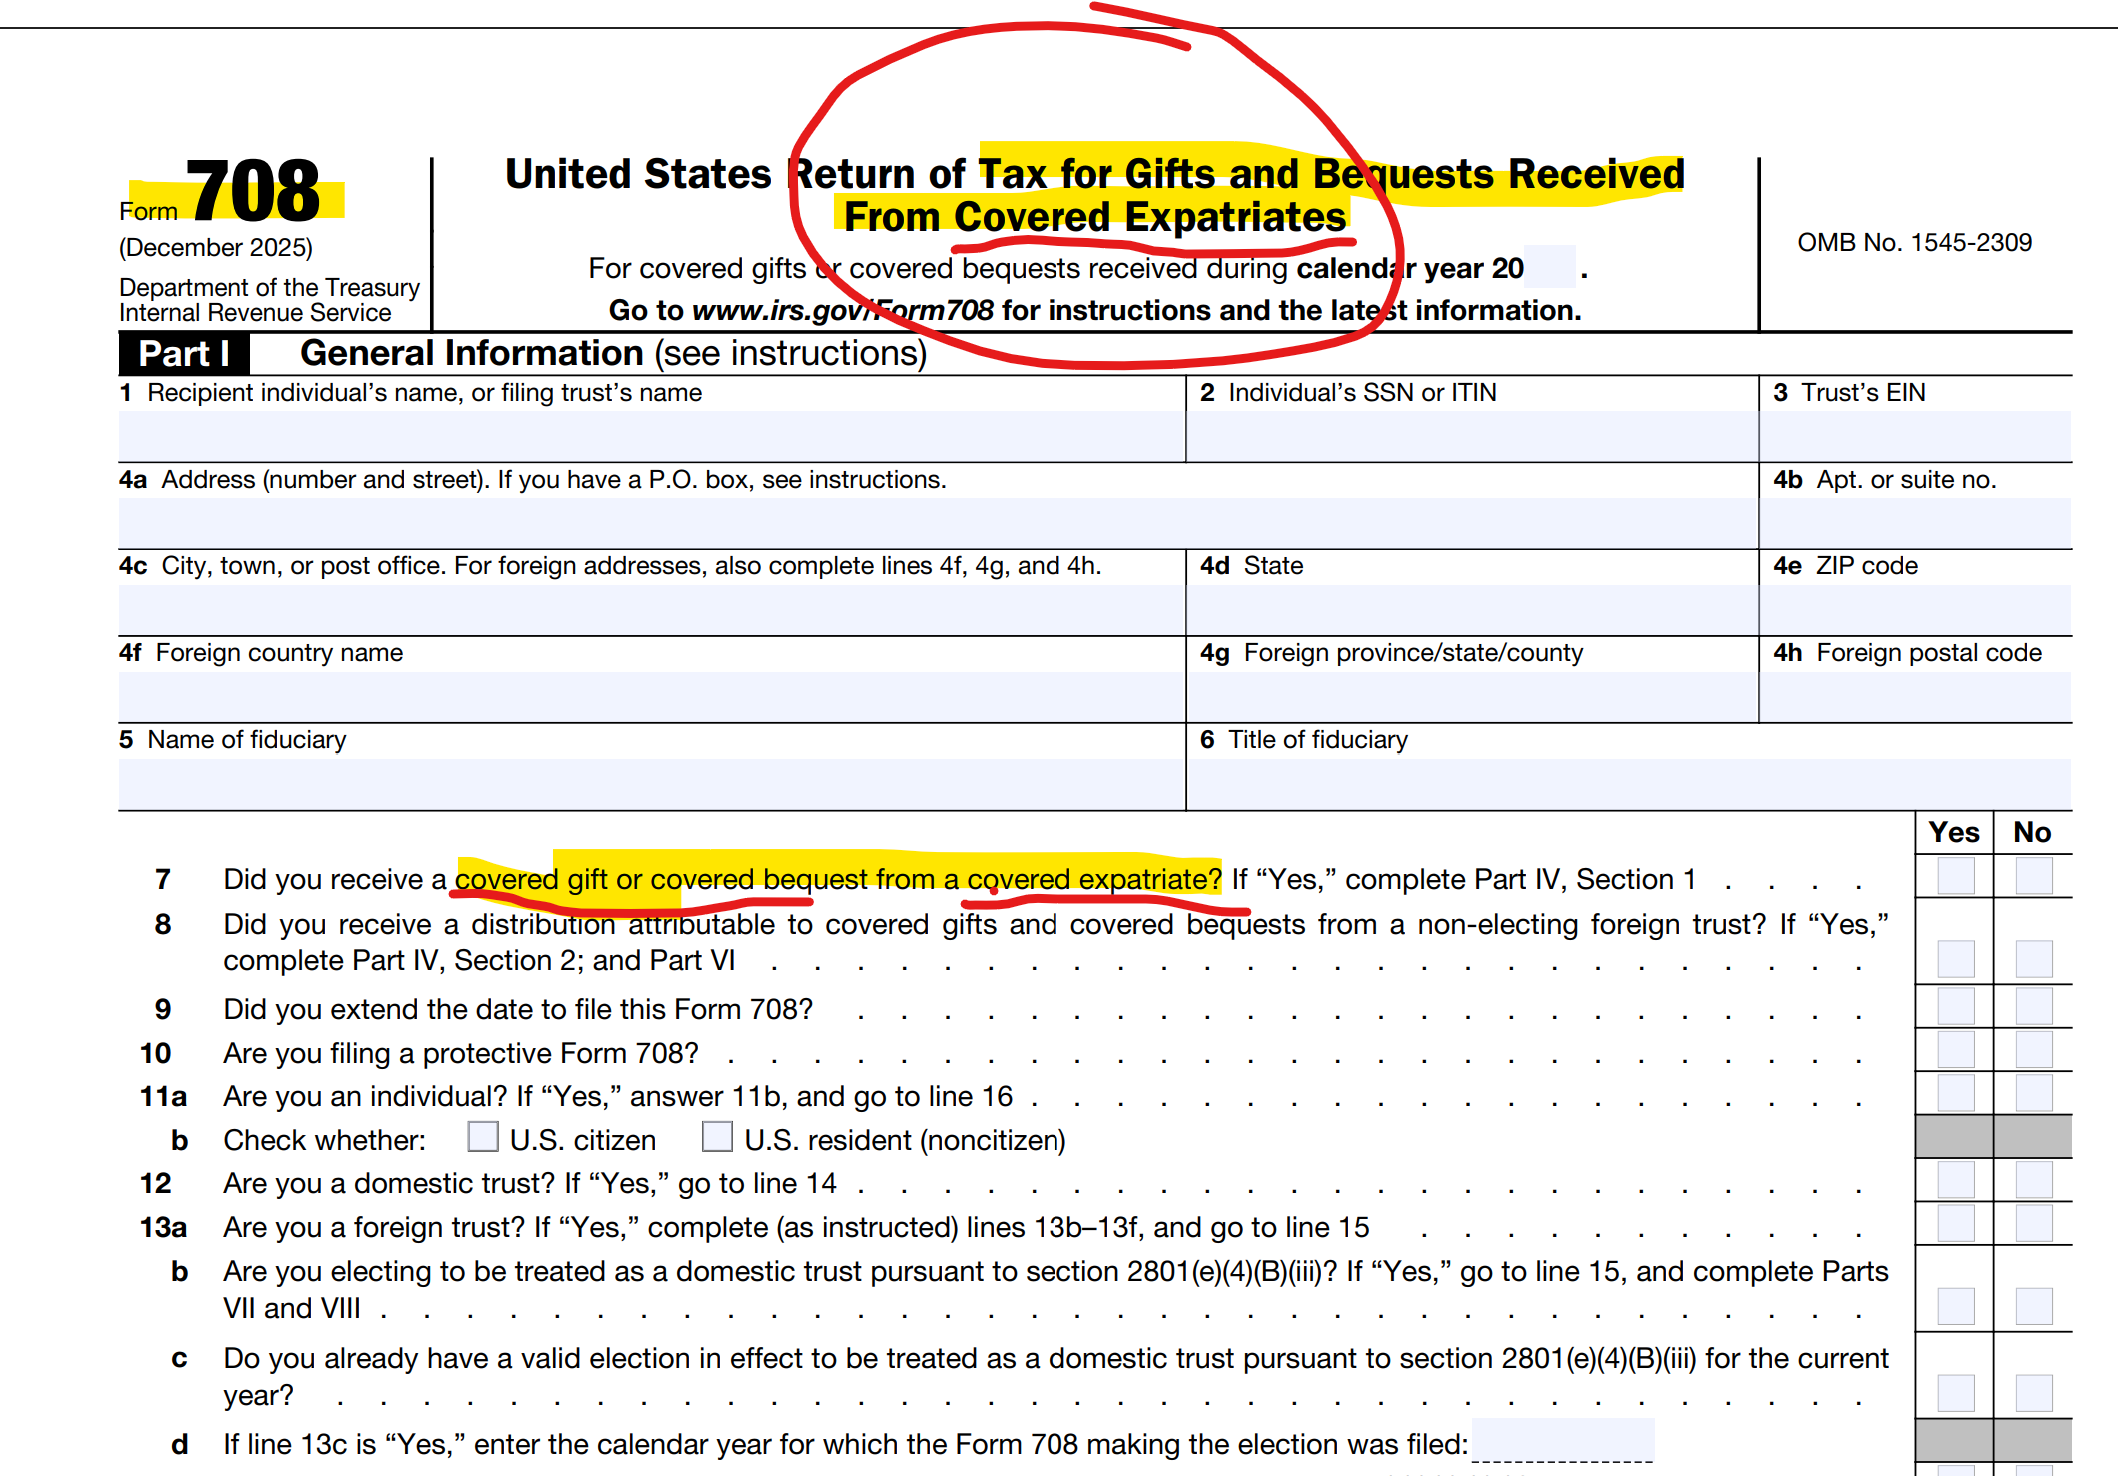
In the case of global soccer players, even one with a “lawful permanent resident” card (i.e., a “green card”) they may be subject to the Chapter 3 withholding tax rules if the athlete is like Mr. Aroeste (Aroeste v. United States (Case No. 22-cv-00682-AJB-KSC)) holding a green card in his pocket, but not a U.S. income tax resident by application of the residency rules set forth in an income tax treaty. Will the soccer player become a “covered expatriate” and not even know it (oops)?! It can get tricky quickly. There are important unintended tax consequences that can befall individuals here: see, Oops…Did I “Expatriate” and Never Know It: Lawful Permanent Residents Beware!International Tax Journal, CCH Wolters Kluwer, Jan.-Feb. 2014, Vol. 40 Issue 1, p9).
Meanwhile, Mexico and the U.S. have both advanced to the knockout round.
Canada plays Switzerland and presumably has a 99% chance of advancing to the Round of 23.
Why Long-Term Green Card Holders Cannot Escape the Exit Tax Rules
When long-term green card holders give up their green card, they face the same exit tax rules as US citizens who renounce citizenship. There is one exception in the law that allows certain dual citizens by birth to avoid covered expatriate status even if they meet the income or asset tests. Long-term green card holders cannot use it. Here is why.
When you give up your green card (or renounce US citizenship), the law determines whether you are a covered expatriate. You are a covered expatriate if you meet any one of three tests: an average annual income tax liability above an inflation-adjusted threshold, a net worth of $2 million or more on the date of expatriation, or a failure to certify 5 years of US tax compliance – where it is commonly certified on IRS Form 8854.
Meeting even one of these three tests makes you a covered expatriate. All three tests apply equally to US citizens who renounce and to long-term lawful permanent residents (LPRs) who give up their green card.
Is there an exception to the income and asset tests?
Yes, for some people. Under IRC Section 877A(g)(1)(B), certain individuals are exempt from the income and asset tests. If this exception applies to you, you can avoid covered expatriate status even if your net worth exceeds $2 million or your income exceeds the threshold. The certification requirement under Section 877(a)(2)(C) still applies to everyone, including those who qualify for this exception.
Who can use this exception?
The exception is narrow. Under the statute, it applies only to an individual who: became a citizen of the United States and a citizen of another country at birth; as of the date of expatriation, continues to be a citizen of and is taxed as a resident of that other country; and has been a US resident for no more than 10 taxable years during the 15-year period ending with the taxable year of expatriation. Only someone who acquired US citizenship automatically at birth, while also holding citizenship of another country from birth, can potentially qualify.
Why green card holders cannot use it
Lawful permanent residents are not US citizens. They hold a green card, which is a grant of permanent resident status, not citizenship. Because the exception in Section 877A(g)(1)(B) applies only to individuals who became US citizens at birth, long-term LPRs cannot satisfy this requirement by definition. The exception is simply not available to them.
What this means if you are a long-term green card holder
A long-term LPR who meets either the $2 million asset test or the income tax liability test will become a covered expatriate, even if they fully satisfy the 5-year certification requirement. Satisfying the certification requirement is necessary for everyone, but for long-term LPRs it is not sufficient on its own. If you also meet the income or asset test, you are a covered expatriate regardless.
The consequences include the mark-to-market exit tax on unrealized gains and the Section 2801 tax on covered gifts and bequests to US persons. These consequences can affect your US family members for decades. Understanding them well before you give up your green card, not after, is the only way to plan for them.
There are important unintended tax consequences that can befall individuals who have a green card depending upon their factual circumstances: see, Oops…Did I “Expatriate” and Never Know It: Lawful Permanent Residents Beware!International Tax Journal, CCH Wolters Kluwer, Jan.-Feb. 2014, Vol. 40 Issue 1, p9):
This post provides general information only and is not legal advice. Consult an experienced attorney for guidance specific to your situation.
Form W-8 or W-9? Why the Wrong Choice Could Cost Green Card Holders Abroad
The choice between Form W-8 and Form W-9 comes down to one thing: your U.S. tax residency status, not your immigration status. Green card holders living abroad may be able to sign Form W-8 under a U.S. income tax treaty, but picking the wrong form means signing a false statement under penalty of perjury. And claiming treaty benefits carries a risk that many people never see coming. Consulting an experienced attorney before signing anything is essential.
What is the difference between Form W-8 and Form W-9?
Both forms tell your bank or financial institution whether you are a U.S. tax resident or not. Form W-9 is for U.S. residents, who must pay U.S. taxes on income they earn anywhere in the world. Form W-8BEN is for non-residents, who generally only pay U.S. taxes on certain types of income that come from U.S. sources. The form you sign has real legal consequences, not just administrative ones.
What happens if you sign the wrong form?
Signing either form is a certification made under penalties of perjury. If you are a U.S. tax resident and you sign Form W-8, you are making a false statement, and serious legal consequences may follow.
Why is this more complicated for green card holders living abroad?
U.S. citizens always sign Form W-9, with no exceptions. For everyone else, it depends on tax residency status. Green card holders are generally treated as U.S. tax residents even while living in another country, which would normally mean they sign Form W-9. But there is an important exception: if the country where they live has an income tax treaty with the United States, they may be able to claim non-resident status under that treaty and sign Form W-8 instead. There are important unintended tax consequences that can befall individuals here: see, Oops…Did I “Expatriate” and Never Know It: Lawful Permanent Residents Beware!International Tax Journal, CCH Wolters Kluwer, Jan.-Feb. 2014, Vol. 40 Issue 1, p9).
The United States has 58 income tax treaties that together cover 66 countries. That includes the 1973 U.S. and U.S.S.R. income tax treaty, which still applies today to nine former Soviet republics: Armenia, Azerbaijan, Belarus, Georgia, Kyrgyzstan, Moldova, Tajikistan, Turkmenistan, and Uzbekistan.
What did the court decide in Aroeste v. United States, and why does it matter?
Aroeste v. United States (Case No. 22-cv-00682-AJB-KSC) is a federal court decision that established a 5-step analysis for green card holders who have not formally given up their green card but are living abroad. The key question the court addresses is whether a green card holder qualifies to be treated as a resident of a foreign country under an applicable U.S. income tax treaty. This ruling matters for the more than 3 million LPRs who are living outside the United States.
What are the benefits of successfully claiming non-resident status under a treaty?
If a green card holder qualifies as a non-resident under a tax treaty, they may be able to stop filing U.S. federal income tax returns on their worldwide income. They may also no longer be required to file the Foreign Bank Account Report, known as the FBAR, which would help them avoid the significant penalties that come with missing that filing. The court in Aroeste laid out the specific steps required to make this claim correctly.
One important note: if you claim non-resident status under a treaty but fail to report that treaty position to the IRS on time, you face a separate penalty under IRC Section 6712(a) of $1,000 for each failure to timely file. Claiming treaty status correctly and reporting it on time are both required.
What is the risk on the other side?
Claiming treaty-based non-resident status may also legally end your U.S. tax residency. Under IRC Section 7701(b)(6), this shift may cause you to cease to be a lawful permanent resident of the United States. That change may trigger the U.S. expatriation tax rules under IRC Section 877A(g)(3), which could classify you as a covered expatriate. The Aroeste court did not address these consequences because they were not part of that case, but they are real and potentially serious.
What does covered expatriate status mean for your family?
Covered expatriate status does not only affect you. If your family members or friends in the United States later receive gifts or an inheritance from you, they may owe U.S. tax on those transfers under the covered gift and covered bequest rules. This may affect children, spouses, and anyone else who would receive something from you.
Do you need an attorney before making this decision?
The answer depends on which country you live in, which treaty applies, the value of your assets, and your long-term plans. Getting it wrong may trigger exit taxes, affect your family’s inheritance, and have consequences that cannot easily be undone. This post explains the framework but is not a substitute for legal advice specific to your situation.
Green Card Holders (Abandonment) – so Many More than U.S. Citizens who Renounce: The Topsnik Problem(s)!
I have previously written (pre-Aroeste v. United States) about the thorny issues that LPRs face when spending substantial time outside the United States. See an earlier post titled:
I highlighted some key concepts about why it matters if you become a “long-term” resident as that term is defined in the tax law and now the case law in Aroeste makes these risks clear as confirmed in the landmark case.
A LPR can reside for substantially shorter periods in the U.S. (shorter than the apparent 7 or 8 years identified in the statute), and still be a “long-term resident” per IRC Section 877 (e)(2) depending upon the facts of any particular case.
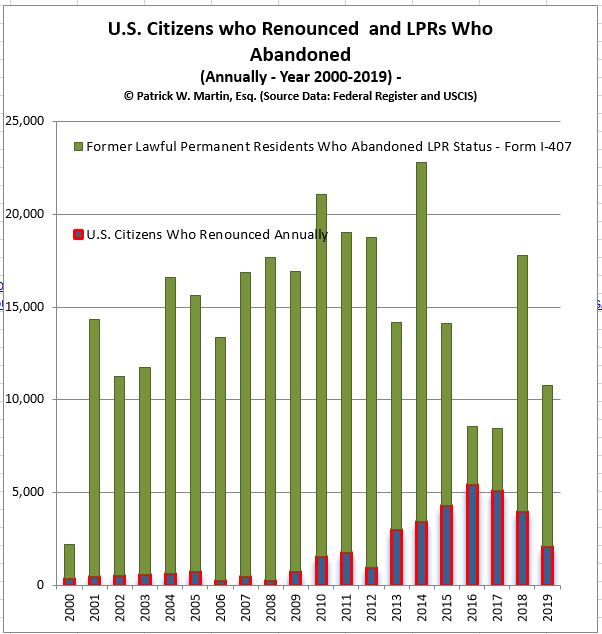
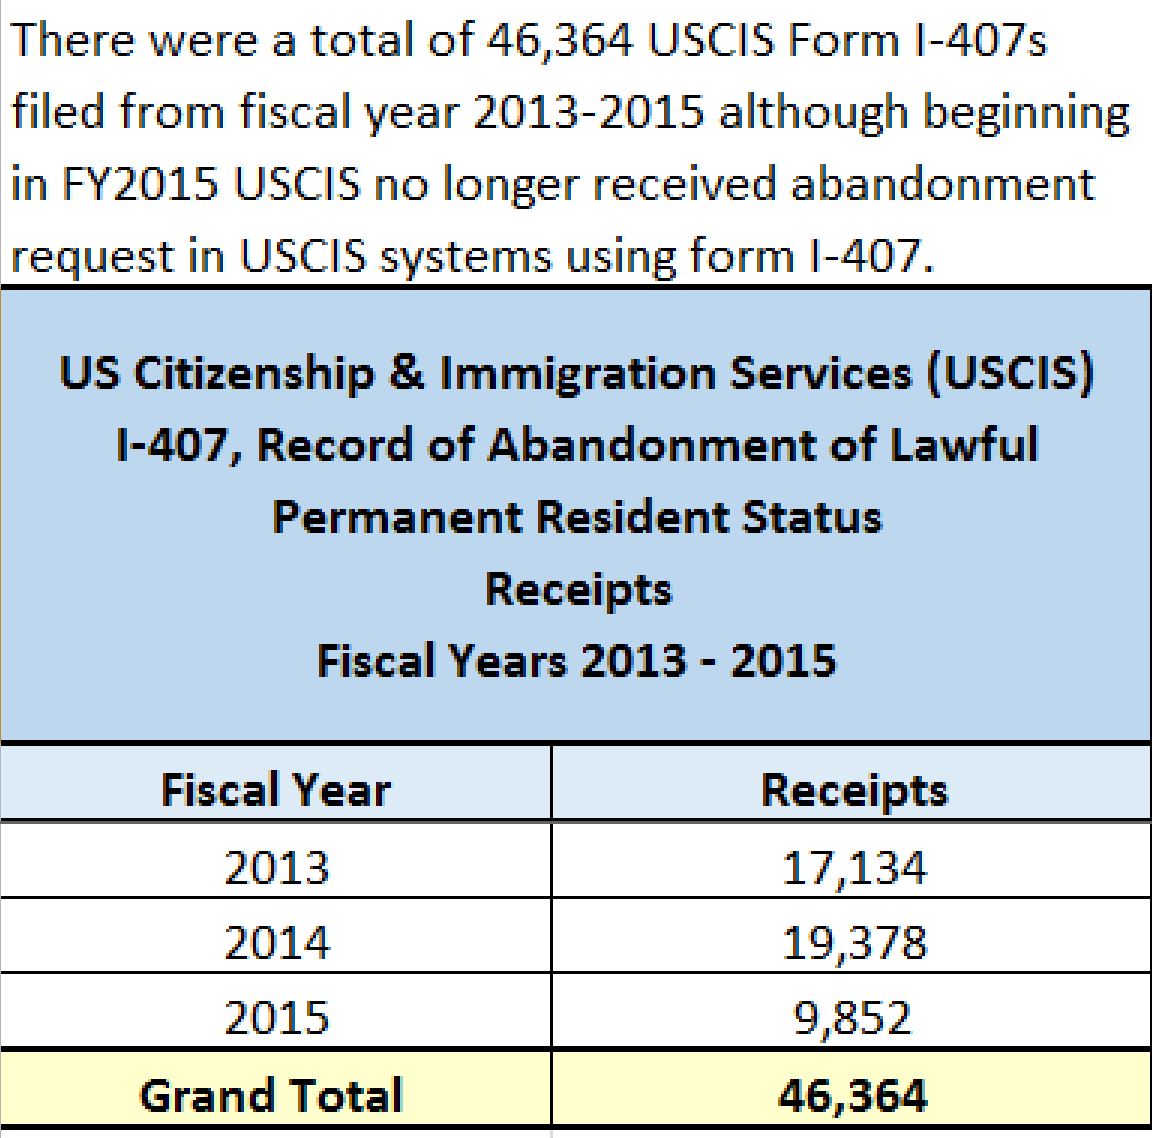
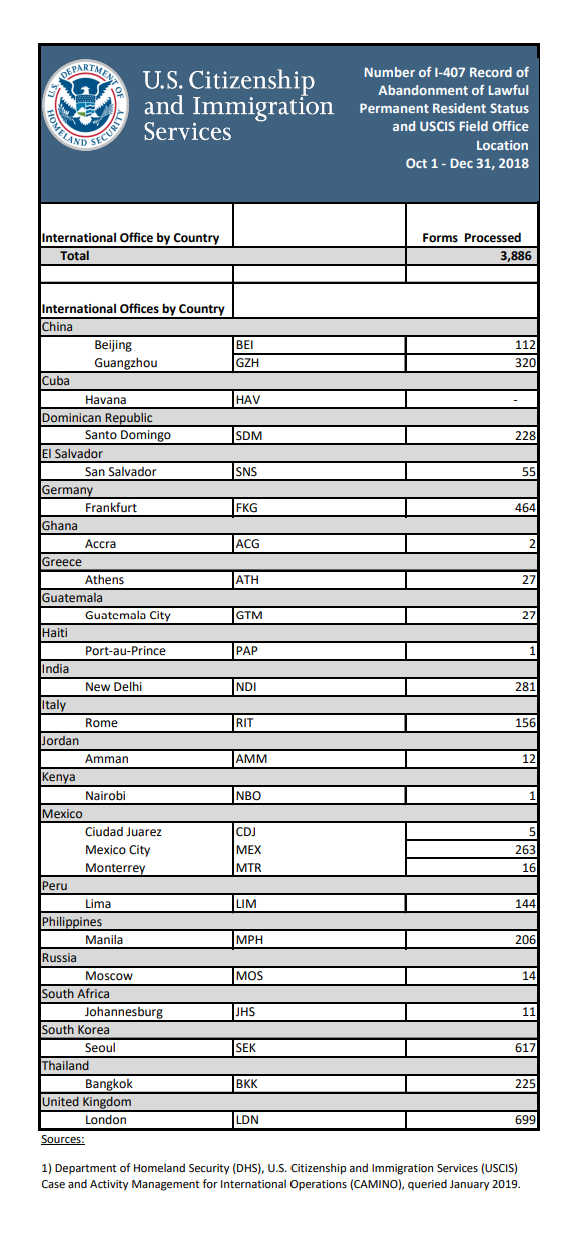
There are far more LPRs who abandon their status (formally) than U.S. citizens who formally take the oath of renunciation. See the table above reflecting those who have formally renounced U.S. citizenship versus those who have formally abandoned their LPR status.
Plenty of LPRs informally abandon their LPR status for immigration purposes by moving and living permanently outside the U.S.
There are plenty of timing issues for LPRs surrounding how and when they have “abandoned” their LPR status for purposes of IRC Section 877 (e)(2). See –
* More Green Card Holders Abandon Status Than Citizens Renounce Citizenship
A frequently overlooked fact is that:
Formal Abandonment of LPR Status Is More Common Than Citizenship Renunciation
Each year, substantially more lawful permanent residents formally abandon their green cards than U.S. citizens formally renounce citizenship. The focus in the press and media is typically U.S. citizens who formally renounce. Here is my most recently compiled graph, the total number of U.S. citizens renouncing is typically in the thousands (few) each year. It has trended downward post-COVID.
However, with LPRs, formal recognition of abandonment by filing Form I-407 (not including informal abandonments which are multiple times greater) is multiple times greater.
The graph I created several years ago, shows that formal LPR abandonments are mlutiple times greater than citizenship renunciation. I made a FOIA request with the government to request information about the number USCIS Forms I-407 that are filed with the government. See, also quarterly statistics of the USCIS – Form I-407, Record of Abandonment of Lawful Permanent Resident Status (partial information for years 2016-2019).
I have made a new FOIA request for more recent records, since this data is no longer public after the year 2019 year.
The statistics reflected above demonstrate that:
Formal green card abandonment significantly exceeds formal citizenship renunciations.
The population potentially affected by the expatriation rules is therefore much larger than many individuals around the world appreciate.
Lack of Control Over the Timing of Termination
One of the greatest risks for green card holders is that they often do not control the legal date on which their LPR status terminates, especially if they reside in a tax treaty country, per the analysis in the landmark case:
If abandonment is later determined by tax treaty law, effectively an CPB officer, the Executive Office for Immigration Review (EOIR) immigration court, the Board of Immigration Appeals (BIA)or a even a Federal District Court:
The taxpayer may not control the effective date of termination – “expatriation”.
If they are a “covered expatriate” or not.
The tax consequences may arise unexpectedly.
The timing can directly impact whether the tax expatriation rules apply and all of the potential consequences.
These timing issues become important when the IRS challenges tax positions taken on tax returns filed (or filed late) as was the case in Topsnik v. Commissioner (143 T.C. 240 (2014) – “Topsnik I”) and the subsequent case of Topsnik v. Commissioner (146 T.C. No. 1, 2016) – “Topsnik II”). In Topsnik II, Judge Kerrigan agreed with the IRS and ” . . . determined that P [taxpayer] was a “covered expatriate” who expatriated in 2010 and must recognize gain on the deemed sale of his installment obligation on the day before his expatriation under I.R.C. sec. 877A.” The U.S. Tax Court cited IRS Notice 2009-85 and explained it was not legally binding as follows:
We are not bound by Notice 2009-85, supra, see Compaq Computer Corp. v. Commissioner, 113 T.C. 363, 372 (1999), but it is an official statement of the Commissioner’s position and we may let it persuade us, see Nationalist Movement v. Commissioner, 102 T.C. 558, 583 (1994), aff’d, 37 F.3d 216 (5th Cir.1994).
The Tax Court went on to conclude these facts caused the court to conclude and uphold the IRS assessment of the “exit tax” on the German citizen Mr. Topsnik as a “covered expatriate” quoted as follows:
Notice 2009-85, sec. 8, 2009-45 I.R.B. at 611, explains that for purposes of certifying tax compliance for the five years before expatriation pursuant to section 877(a)(2)(C):
All U.S. citizens who relinquish their U.S. citizenship and all long-term residents who cease to be lawful permanent residents of the United States (within the meaning of section 7701(b)(6)) must file Form 8854 in order to certify, under penalties of perjury, that they have been in compliance with all federal tax laws during the five years preceding the year of expatriation. Individuals who fail to make such certification will be treated as covered expatriates within the meaning of section 877A(g) * * *
For the year of his expatriation petitioner failed to complete and file a Form 8854 certifying under penalties of perjury that he has complied with all of his U.S. Federal tax obligations for the five taxable years preceding the taxable year that includes his expatriation date. Respondent [IRS] has provided evidence that petitioner did not file all of his U.S. income tax returns before expatriatingand was not in payment compliance for taxes owed for the five years before expatriation in taxable year 2010. Thus petitioner could not have certified under penalties of perjury on a Form 8854 that he had been in tax compliance for the five years before expatriation. Consequently, because petitioner failed to certify tax compliance for the five years before expatriation, he is a “covered expatriate” as defined by section 877A(g)(1)(A).
Importantly, the court in Aroeste concluded IRS Form 8854 was not required to be filed (even though the DOJ attorney argued it was required – as set forth in the instructions to the form) as explained below:
C. Whether Aroeste Was Required to File Form 8854
The Government next argues that even if the IRS had accepted Aroeste’s amended
returns, neither amended return would have properly notified the IRS of a commencement of treaty benefits because both failed to attach Form 8854, as required by IRS Notice 2009- 85.(Doc. No. 76-1 at 4–5.) The Government concedes Aroeste attached Form 8833 to both
amended forms. (Id.)
Aroeste responds that Notice 2009-85 is not binding authority as it fails to comply
with the Administrative Procedures Act (“APA”). (Doc. No. 78-1 at 8 (citing Green Valley
Investors, LLC v. Comm’r of Internal Revenue, 159 T.C. No. 5, at *4 (Nov. 9, 2022)) (under
the APA, agencies must follow a three-step procedure for “notice-and-comment”
rulemaking, but this requirement does not apply to “interpretive rules, general statements
of policy, or rules of agency organization, procedure, or practice.”).) The Court agrees. In
Mann Construction, Inc. v. United States, 27 F.4th 1138 (6th Cir. 2022), the court found
that Notice 2007-83 failed to comply with the APA’s notice-and-comment procedure.
Similarly here, because Notice 2009-85 has not been subject to a notice-and-comment procedure, it does not comply with the APA and thus is not binding. As such, Aroeste was not required to file Form 8854 with his amended returns.
Both the Green Valley Investors LLC case and Mann Construction were 2022 cases, some 6 years after Topsnik II.
My law firm, Chamberlain Hrdlicka, successfully represented the taxpayers in Green Valley and of course in Aroeste.
Practical Lessons for Green Card Holders
The combined lessons from Aroeste, Topsnik I, and Topsnik II are significant.
Before Obtaining a Green Card
Individuals should understand:
The long-term resident rules and their U.S. tax obligations and reporting obligations;
The expatriation tax provisions and how they generally apply;
The “covered expatriate” tax regime and what steps to take;
The impact of income tax treaties with countries in the United States.
Before Formally Reporting the Abandonment (or Informally Abandoning) a Green Card
Individuals should carefully evaluate:
The date expatriation may occur;
Whether Form I-407 should be filed;
Tax compliance under U.S. tax laws (and what that means), including for the preceding five years to abandonment;
What notifications should be provided and when (not necessarily formal tax form filings);
Potential exit tax exposure – depending upon total assets, liabilities, type of assets and anticipated future income and gains;
Treaty residency positions and the particular facts of each case;
Reporting obligations, and which ones are mandatory or not – including IRS Forms 8833 and 8854.
Most Important Takeaway?
A green card holder does not necessarily need to spend seven or eight years physically living in the United States before becoming subject to the long-term resident and expatriation tax rules. The interaction of immigration law, tax law, treaty provisions, and reporting requirements can produce unexpected results. The recent landmark decision in Aroeste that I handled, confirms that these issues are not merely theoretical—they are increasingly becoming the subject of significant litigation and judicial scrutiny.
Many individuals have no idea that, under the legal principles confirmed in the federal district court case I litigated — Aroeste v United States, 22-cv-00682-AJB-KSC (20 Nov. 2023) – they may already be treated as “covered expatriates” as a matter of law.
Along Comes Section 2801 – and 2025 Final Regulations – The “Forever Taint” to Family and Friends (Paying the Taxman)
Aroeste – Landmark Decision Confirms the Law – Tax Treaty Law Applies – Taxpayers Do Not Waive Benefits per Gov’t
These writings all addressed the same underlying legal and policy expectations that courts would eventually be required to confront — issues now directly addressed in Aroeste. The Aroestedecision is also consistent with positions I successfully advanced in three separate U.S. Tax Court cases involving green card holders, none of which resulted in published opinions because the government ultimately conceded to my arguments and my clients prevailed prior to trial.
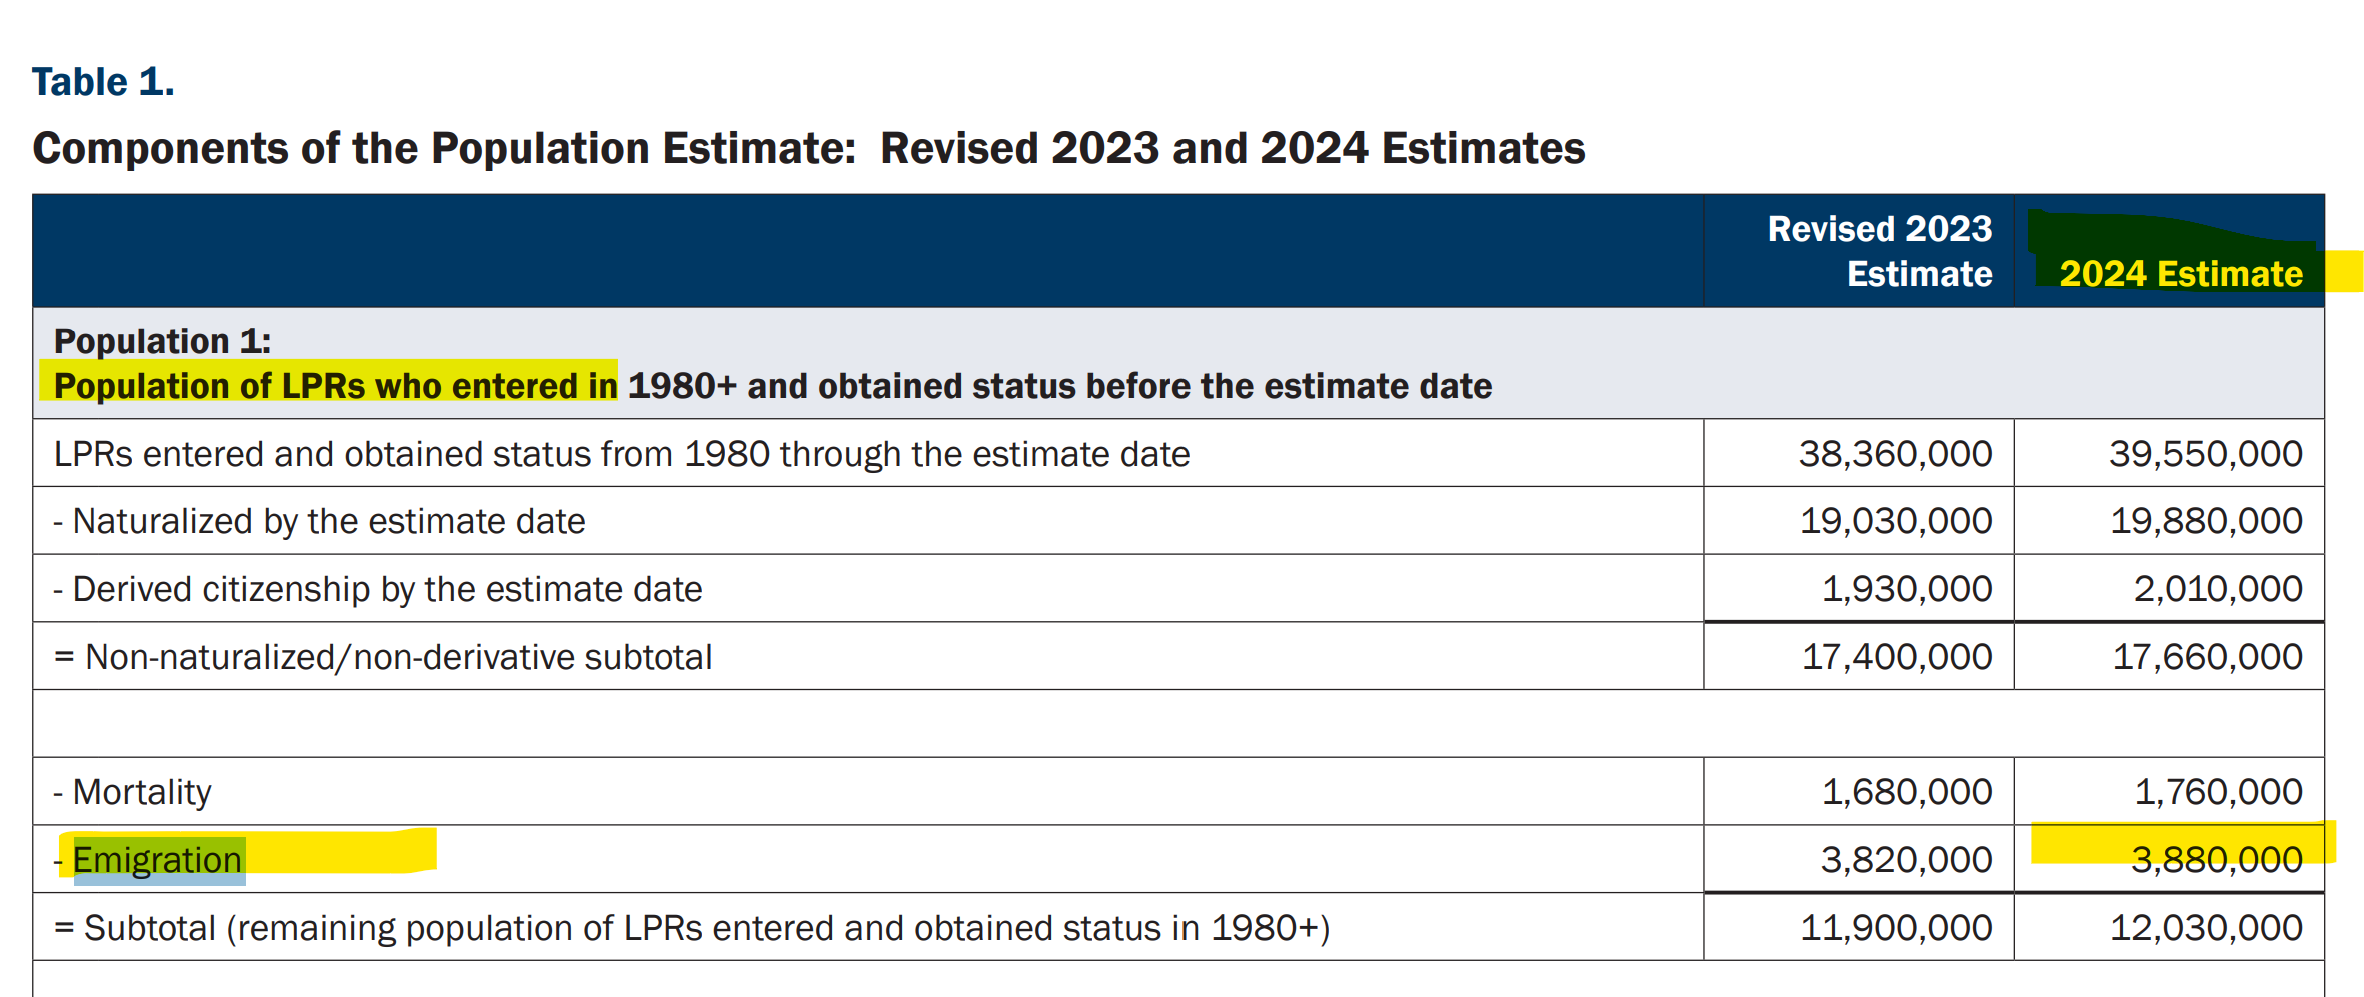
This case law has great impact on green card holders who are living principally outside of the U.S. There are 3.88 million individuals who are living outside the U.S. – per the 2024 report by the U.S. federal government. Many of them live in a treaty country. Many of these individuals might be considering their immigration law consequences (particularly after the latest announcement from the USCIS – impact these immigration consequences: U.S. Citizenship and Immigration Services Will Grant ‘Adjustment of Status’ Only in Extraordinary Circumstances (May 2026) Few have considered the tax law implications.
Most important Questions for “Green Card” Holders (“lawful permanent residents”): Part I of VI
Those individuals who have green cards and live in and outside of the United States, should understand the tax and legal implications to them.
There are millions of individuals in this category. i.e., those who have “emigrated” with an “e” from the United States. There are 3.88 million of these green card holders, as of 2024 according to the U.S. federal government’s latest report. The statistics are striking – that so many individuals reside outside the U.S.
These nearly 4 million individuals who do not reside principally in the U.S. are similar to the fact pattern of Mr. Aroeste residing in Mexico City. See the case where yours truly, Patrick W. Martin, was lead counsel in that landmark case – and the analysis of the District Court in Aroeste v. United States. The government lost.
Today’s post is a series of simple and key questions for those with green cards, to help them better hone in on the legal issues and U.S. tax risks that may be applicable to them:
Am I still a U.S. taxpayer?
What does it mean to be a U.S. taxpayer, when there are technical tax terms such as “United States person” and an individual who is a “lawful permanent resident” (not defined in the immigration law)?
I have a green card but I’ve lived outside the U.S. for years — do I still have to file U.S. tax returns?
The date on my physical green card has expired – does that mean I am no longer a a “lawful permanent resident” for tax purposes?
Does it matter whether my green card is expired, taken back at the airport, or just sitting in a drawer overseas?
Is there a difference between “giving up” my green card and just letting it lapse?
Aroeste v. United States — what does it mean for me? –
Why are all of the above questions so important to me – since I previously obtained a “green card”?
Subsequent posts will address additional key questions that can have a significant legal consequence to individuals who had or have a green card and spend substantial time outside of the United States. For a preview, look at Oops.. .Did I Expatriate and Never Know It – International Tax Journal 2014







 Many individuals have no idea that, under the legal principles confirmed in the federal district court case I litigated —