International Tax · Citizenship Renunciation · LPR Abandonment
International Tax Shareholder
Countries From Which Viewers Read Posts – Tax-Expatriation.com – First Week of 2024 (Which Ones are Tax Treaty Countries?) – Applying the “Escape Hatch”
The whole idea of the “escape hatch” for tax treaties is an excellent way of explaining how and when tax treaty law applies in different circumstances. Importantly, the U.S. federal government cannot deny an individual (or presumably a company either) from properly applying the law of a tax treaty – even if they “gave [an] untimely notice of his treaty position “. See further comments at the end of this post and the District Court’s opinion here – Aroeste v United States – Order (Nov 2023). Meanwhile, see below the 22 countries from where global readers viewed Tax-Expatriation.comduring the first full week of 2024.
Below is the list of 22 countries (including the United States) from where readers hailed, who read Tax-Expatriation.comduring the first week of 2024. All, but Brazil, Croatia, Nigeria, the United Arab Emirates, Colombia, Kenya and Bermuda have income tax treaties with the United States.
This means that all other individuals are connected with the following 14 countries that have tax treaties with the United States:
Mexico
India
Canada
United Kingdom
Switzerland
Australia
China
Spain
Turkey
Germany
Japan
Romania
Portugal
Netherlands
Further, all individuals who might have never formally abandoned their lawful permanent residency (“green card”), maybe never filed specific IRS tax forms, and yet reside in one of these fourteen (14) treaty countries could be eligible for the application and the specific benefits of international income tax treaty law. This, along the lines of the decision in Aroeste v United States (Nov. 2023). In addition, there could be other tax treaty benefits applicable to those individuals in these fourteen countries depending upon where are their assets, what type of income they have, where does the income come from, and where do they reside.
The tax treaty rights discussed here are established by law, as elucidated by the Federal District Court in Aroeste v United States (Nov. 2023). The Court determined that the IRS cannot simply assert an individual’s ineligibility for treaty law provisions based solely on the failure to file specific IRS forms within the government-defined “timely” period. The Court emphasized that there is no automatic waiver of treaty benefits as a matter of law, while acknowledging: “. . . Aroeste gave untimely notice of his treaty position. . .” For specific excerpts from the opinion, please refer to the highlighted portions below. To access the complete opinion, please consult Aroeste v United States – Order (Nov 2023).
* * * * * * * * *
B. Whether Aroeste Did Not Waive the Benefits of the Treaty Applicable to Residents of Mexico and Notified the Secretary of Commencement of Such Treatment.
To establish Mexican residency under the Treaty, and thus avoid the reporting requirements of “United States persons,” Aroeste must have filed a timely income tax return as a non-resident (Form 1040NR) with a Form 8833, Treaty-Based Return Position Case 3:22-cv-00682-AJB-KSC Document 90 Filed 11/20/23 PageID.2722 Page 8 of 17 9 22-cv-00682-AJB-KSC Disclosure Under Section 6114 or 7701(b). Indeed, Aroeste did not submit Form 8833 to notify the IRS of his desired treaty position for the years 2012 and 2013 until October 12, 2016, when he submitted an amended tax return for both years at issue. (Id.) The Government asserts that because Aroeste did not timely submit these forms, he cannot establish that he notified the IRS of his desire to be treated solely as a resident of Mexico and not waive the benefits of the Treaty. (Id. at 4.) The Government relies upon United States v. Little, 828 Fed. App’x 34 (2d Cir. 2020) (“Little II”), a criminal appeal in which the court held a lawful permanent resident of a foreign country was a “‘resident alien’ or ‘person subject to the jurisdiction of the United States’ with an obligation to file an FBAR.” Id. at 38 (quoting 31 C.F.R. § 1010.350(a), (b)(2)).
In response, Aroeste asserts that while he agrees with the Government that I.R.C. § 6114 requires disclosure of a treaty position, he disagrees as to the consequences for a taxpayer’s failure to timely file the disclosure. (Doc. No. 75-1 at 6.) While the Government asserts the failure to timely file Forms 1040NR and 8833 deprives individuals of the Treaty benefits provided, Aroeste argues instead that I.R.C. § 6712 provides explicit consequences for failure to comply with § 6114. Specifically, § 6712 states that “[i]f a taxpayer fails to meet the requirements of section 6114, there is hereby imposed a penalty equal to $1,000 . . . on each such failure.” I.R.C. § 6712(a). Based on the foregoing, Aroeste argues the taxpayer does not lose the benefits or application of the treaty law.1 (Doc. No. 75-1 at 6.) In United States v. Little, 12-cr-647 (PKC), 2017 WL 1743837, at *5 (S.D. N.Y. 1 Aroeste further asserts that published agency guidance, letter rulings, and technical advice support his position. (Doc. No. 75-1 at 7.) For example, in 2007, an IRS agent sought advice from IRS Counsel asking, “Do we have legal authority to deny a tax treaty because Form 8833 is not attached or the treaty is claimed on the wrong Form (1040EZ or 1040)?” Legal Advice Issued to Program Managers During 2007 Document Number 2007-01188, IRS. IRS Counsel responded, “No, you cannot deny treaty benefits if the taxpayer is entitled to them. You may impose a penalty of $1,000 under section 6712 of the Code on an individual who is obligated to file and does not.” Id. As to this, the Court finds it has no precedential value under I.R.C. § 6110(k)(3), which states that “a written determination may not be used or cited as precedent.” See Amtel, Inc. v. United States, 31 Fed. Cl. 598, 602 (1994) (“The [Internal Revenue] Code specifically precludes [plaintiff] and the court from using or citing a technical advice memorandum as precedent.”) Case 3:22-cv-00682-AJB-KSC Document 90 Filed 11/20/23 PageID.2723 Page 9 of 17 10 22-cv-00682-AJB-KSC May 3, 2017) (“Little I”), a criminal case for the plaintiff’s willful failure to file tax returns, the court stated the plaintiff’s same argument “that the failure to take a Treaty position can result only in a financial penalty also lacks merit. 26 U.S.C. § 6712(c) expressly states that ‘[t]he penalty imposed by this section shall be in addition to any other penalty imposed by law.’” (emphasis added).
I have been consulted over the years by other taxpayers which are cited now as published decisions by the government and the Federal District Court (Southern District of California). These cases are referenced and cited in my own most recent case of Aroeste v United States (Nov. 2023).
However, in Little I, the plaintiff never attempted to take a treaty position. Next, in Shnier v. United States, 151 Fed. Cl. 1, 21 (2020), the court denied the plaintiffs’ claims for relief based on tax treaties because they failed to disclose a treaty based position on their tax returns pursuant to I.R.C. § 6114 “and did not attempt to cure this omission in their briefing[.]” Although the plaintiffs in Shnier were naturalized U.S. citizens who attempted to recover their income taxes under I.R.C § 1297, the court’s brief discussion of I.R.C. § 6114 in relation to a treaty-based position is instructive that an untimely notice of a treaty position does not bar the individual from taking such position. Moreover, in Pekar v. C.I.R., 113 T.C. 158 (1999), the court noted that a taxpayer who fails to disclose a treaty-based position as required by § 6114 is subject to the $1,000 penalty, but stated “there is no indication that this failure estops a taxpayer from taking such a position.” Id. at 161 n.5.2 The Court agrees with Aroeste.
Although Aroeste gave untimely notice of his treaty position, the Court finds this does not waive the benefits of the Treaty as asserted by the Government. Rather, I.R.C. § 6712 provides the consequences for failure to comply with I.R.C. § 6114, namely a penalty of $1,000 for each failure to meet § 6114’s requirements of disclosing a treaty position.
* * * * * * * * *
For individuals living in any of these 14 tax treaty countries (or any of the total 67 income tax treaty countries), the key takeaway is that, based on their specific circumstances, they might be eligible to leverage the international tax treaty principles outlined in the Aroeste v United States case (Nov. 2023). The forthcoming post will pose questions for consideration by the potentially millions of individuals affected by these rules of law.
DHS Report: 3.89M Emigrated LPRs — Who Falls Under the Tax Treaty Escape Hatch?
Clear U.S. tax and legal relief now exists for a significant portion of the 3.89 million Lawful Permanent Residents (LPRs) who never formally abandoned their U.S. immigration status. This relief stems from two sources in the law:
(i) Tax treaty laws that apply to individuals residing in one of the 67 income tax treaty countries with the United States, recently including Chile.
(ii) Legal principles, recently confirmed by the Federal Court in Aroeste v. United States, that establish that individuals can apply tax treaty laws (when applicable) even if they missed certain filing deadlines set by the Internal Revenue Service. The Court termed this provision an “escape hatch,” allowing individuals, depending on specific circumstances, to be considered non-residents of the United States (not “United States persons”). This can be true under the relevant treaty, even if they never formally abandoned their LPR status.
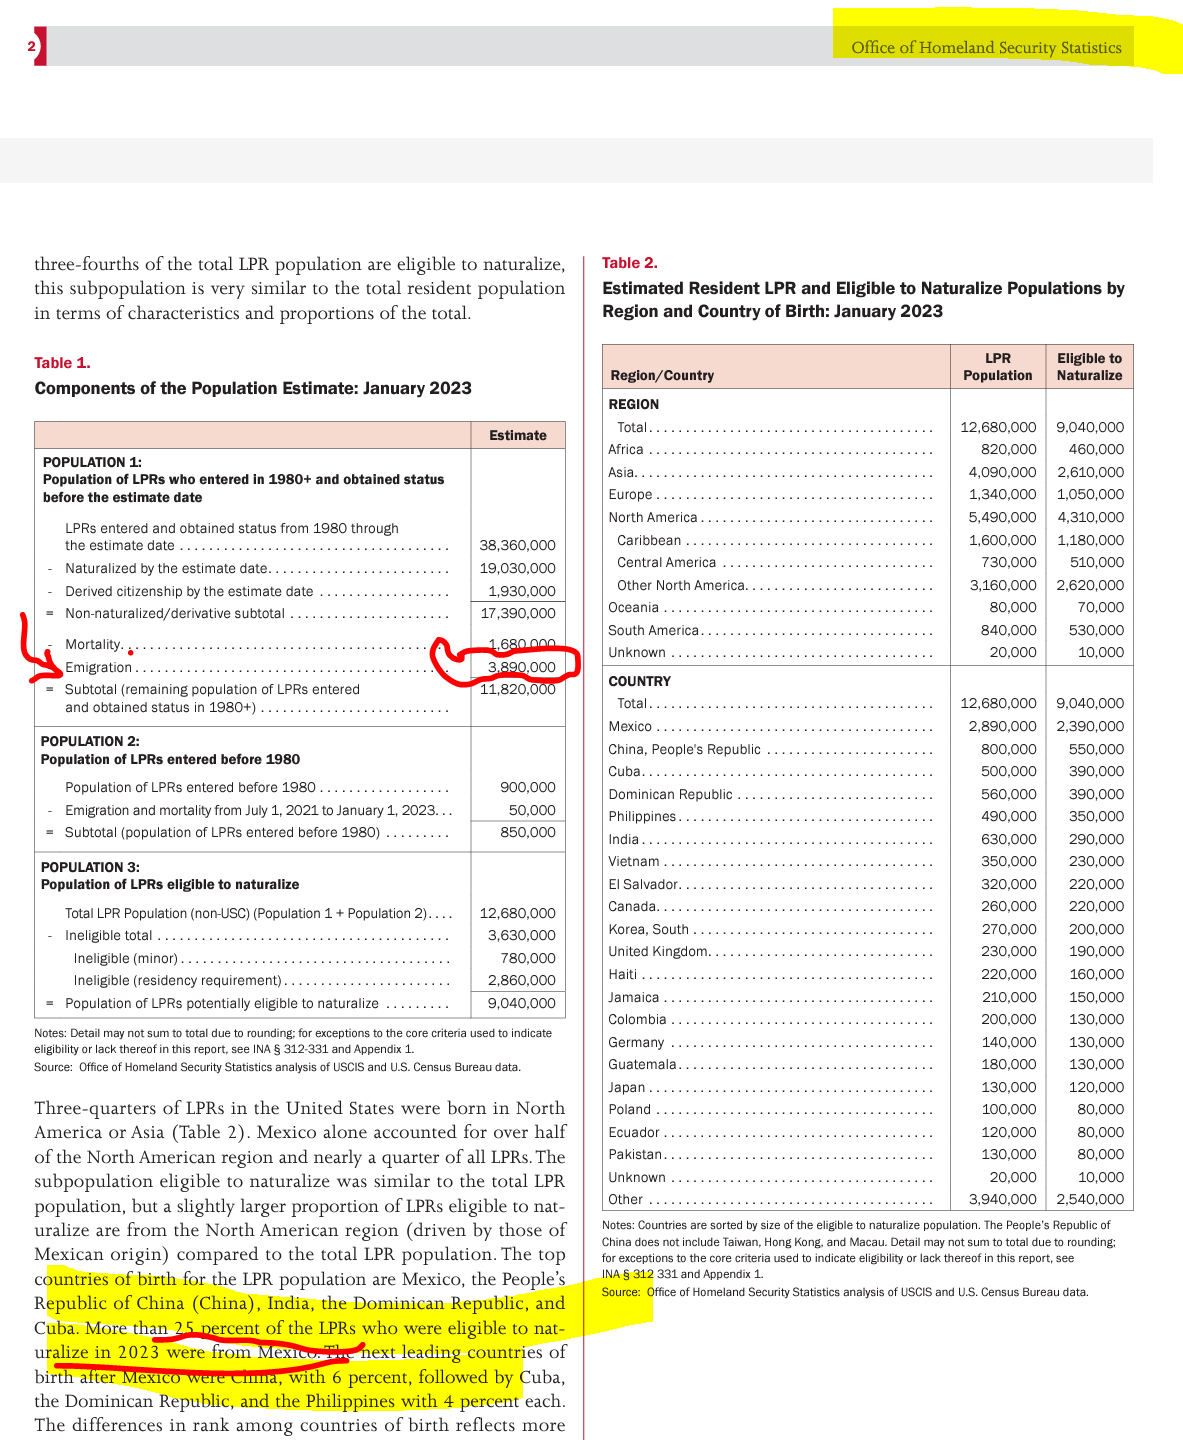
The 2023 DHS report estimates that nearly 4 million individuals have emigrated from and left the United States and are now living somewhere around the world. Notably, Mexico constitutes the largest share at about 25% of the total LPR population who have left the United States.
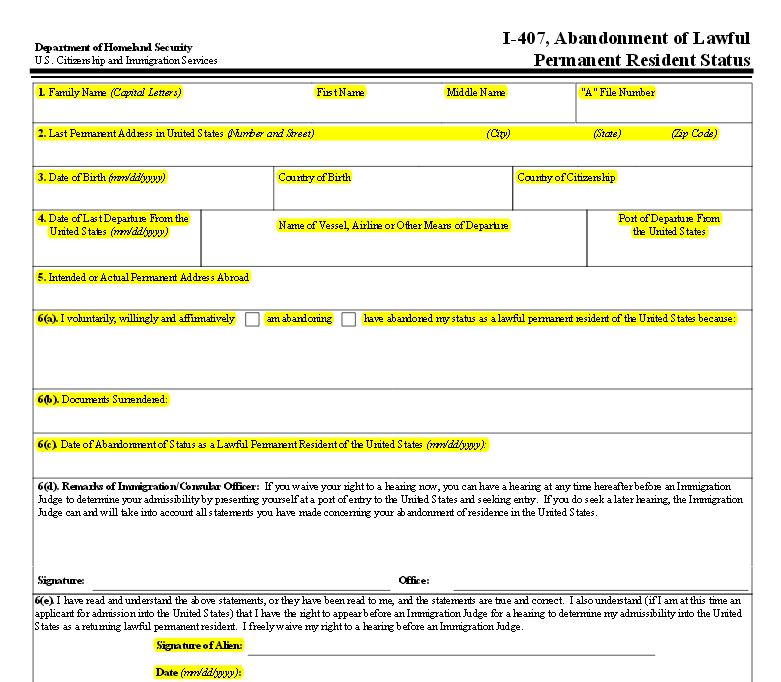
The DHS report allows the reader to extrapolate that around 1 million individuals, similar to Mr. Aroeste, are living in Mexico and did not formally abandon their LPR status by filing Form I-407, Record of Abandonment of Lawful Permanent Resident.
Aroeste v. United States is the third case I’ve litigated, examining whether individuals with a “green card” residing outside the United States in a tax treaty country are considered U.S. income tax residents. The previous two cases (involving Mexican and German citizens) didn’t progress to the oral argument stage; as the government conceded both before trial. See, IRS Chief Counsel Concedes Tax Treaty Residency Position for LPR German Taxpayer in Tax Court
A FOIA response yielded surprising information; the government records indicate that only 46,364 Forms I-407 were filed from 2013 to 2015.
(Source: Federal Government Response to FOIA Request: Office of Performance and Quality (OPQ), Performance Analysis and External Reporting (PAER), JJ)
SOURCE: Federal Government Response to FOIA Request: Office of Performance and Quality (OPQ), Performance Analysis and External Reporting (PAER), JJ
What can we glean from the DHS report and the LPR – I-407 information obtained through the FOIA response? There is a substantial gap in the millions; millions of individuals who have physically left the U.S. to reside elsewhere globally, compared to the relatively smaller number of tens of thousands who have officially filed Form I-407, Record of Abandonment of Lawful Permanent Resident.
Conclusion
Importantly, now under the legal principles established in Aroeste v. United States, individuals residing in one of the 67 countries covered by an income tax treaty have specific legal relief from the worldwide reporting of income to the United States government.
Mérida – the Place to be in February (19th and 20th)
The implications of the Aroeste v United States – Order (Nov 2023) particularly for millions of taxpayers globally and “U.S.” taxpayers affected by pertinent tax treaty provisions, will be a focal point of discussion at the upcoming international tax conference in February.
The University of San Diego School of Law – Chamberlain International Tax Institute will take place on February 19th and 20th, 2024, at the International Convention Center in Mérida, Yucatán, México. You can register for the conference – HERE –
Among the courses offered, there will be a detailed examination of- Aroeste v. the United States: Limits on Government Authority Re: Tax Treaty Law ++– along with other international tax topics and sessions featuring much Moore:
United States Supreme Court – Tax Decisions & Moore
International Tax Reporting: New Reporting of International Partnerships – K-2s & K-3s
United States-based Cross-Border Real Estate Investments (Advanced)
U.S. Investor Visa Options and Limitations
California, Texas & Florida Probate Proceedings of Cross-Border Estates
Federal District Court Rules in Favor of Mexican Citizen – Aroeste vs. United States (LPR) – Tax Treaty Applies: Government’s Motion for Summary Judgment is Denied
Last week (Nov. 20, 2023), Judge Battaglia in the Southern District of California (San Diego) ruled in favor of our client Mr. Alberto Aroeste regarding the application of the U.S.-Mexico Tax Treaty. The DOJ, Tax Division arguments on behalf of the Internal Revenue Service in the case (and their Motion for Summary Judgment – MSJ) were largely rejected by the Court.
A thorough read of the Order from the Court is recommended to understand the substantial legal findings and legal analysis made by the Court relevant to those who possess a “green card” referred to as “lawfully admitted for permanent residence” in Title 8, § 1101(a)(13) [Immigration and Nationality Act]. Key to this case, Title 26, § 7701(b)(6) [Federal Tax Code] then rather contorts the concept by saying an individual is a “lawful permanent resident” in accordance with immigration laws; but then goes on to put conditions on who apparently is a “lawful permanent resident” for federal tax purposes. While immigration law requires the individual be ” . . . accorded the privilege of residing permanently in the United States as an immigrant in accordance with the immigration laws, such status not having changed”; the tax definition seems to ignore that status (i.e., has it changed and is the personal no longer accorded the privilege of residing permanently in the U.S.?).
The Board of Immigration Appeals (the “Board”), has long recognized that an alien’s status may change by operation of law, such that an alien may abandon his LPR status without a finding of removability (or, formerly, deportability or excludability) after a formal adjudicatory process. See United States v. Yakou, 428 F.3d 241, 247 (D.C. Cir. 2005); at 247-51 (discussing case law regarding abandonment and holding that an alien may abandon LPR status without formal administrative action); see also Matter of Quijencio, 15 I. & N. Dec. 95 (B.I.A. 1974); Matter of Kane, 15 I. & N. Dec. 258 (B.I.A. 1975); Matter of Muller, 16 I. & N. Dec. 637 (B.I.A. 1978); Matter of Abdoulin, 17 I. & N. Dec. 458, 460 (B.I.A. 1980); Matter of Huang, 19 I. & N. Dec. 749 (B.I.A. 1988).
The Court did not need to get into the nuances of immigration law to rule against the government in this case.
Some of the substantial takeaways from the decision are:
Waiver of the Tax Treaty: The government cannot assert an individual waived the treaty law because she initially filed the wrong IRS forms (1040) instead of the non-resident form (1040NR) and IRS Form 8833.
The Court agrees with Aroeste. Although Aroeste gave untimely notice of his treaty position, the Court finds this does not waive the benefits of the Treaty as asserted by the Government. Rather, I.R.C. § 6712 provides the consequences for failure to comply with I.R.C. § 6114, namely a penalty of $1,000 for each failure to meet § 6114’s requirements of disclosing a treaty position.
Aroeste v United States – Order 20 Nov 2023 (p. 17)
Expatriation Tax form – IRS Form 8854: Validity and its Failure to Comply with the Administrative Procedure Act (“APA”)
C. Whether Aroeste Was Required to File Form 8854 The Government next argues that even if the IRS had accepted Aroeste’s amended returns, neither amended return would have properly notified the IRS of a commencement of treaty benefits because both failed to attach Form 8854, as required by IRS Notice 2009-85. (Doc. No. 76-1 at 4–5.) The Government concedes Aroeste attached Form 8833 to both amended forms. (Id.) Aroeste responds that Notice 2009-85 is not binding authority as it fails to comply with the Administrative Procedures Act (“APA”). (Doc. No. 78-1 at 8 (citing Green Valley Investors, LLC v. Comm’r of Internal Revenue, 159 T.C. No. 5, at *4 (Nov. 9, 2022)) (under the APA, agencies must follow a three-step procedure for “notice-and-comment” rulemaking, but this requirement does
not apply to “interpretive rules, general statements of policy, or rules of agency organization, procedure, or practice.”).) The Court agrees. In Mann Construction, Inc. v. United States, 27 F.4th 1138 (6th Cir. 2022), the court found that Notice 2007-83 failed to comply with the APA’s notice-and-comment procedure. Similarly here, because Notice 2009-85 has not been subject to a notice-and-comment procedure, it does not comply with the APA and thus is not binding. As such, Aroeste was not required to file Form 8854 with his amended returns.
Aroeste v United States – Order 20 Nov 2023 (p. 11)
Tax Treaty Law Applies – Article 4 Regarding Tax Residency
Various detailed analysis and discussions from the Court –
Aroeste v United States – Order 20 Nov 2023 (p. 11-14)
The Preamble to the FBAR Regulations is Not the Law –
. . . the Government points to the preamble to the 31 C.F.R. Part 1010 regulations, providing that “[a] legal permanent resident who elects under a tax treaty to be treated as a non-resident for tax purposes must still file the FBAR.” Amendment to the Bank Secrecy Act Regulations—Reports of Foreign Financial Accounts, 76 Fed. Reg. 10234-01 (Feb. 24, 2011). The Court finds this unavailing. The Government’s argument does not refute the plain language of the FBAR regulations, which explicitly invoke provisions of Title 26, including the provision that requires consideration of an individual’s status under an applicable tax treaty for the purpose of determining whether an individual is a “United States person” subject to FBAR filing. Specifically, Title 31 C.F.R. § 1010.350, which governs reporting of FBARs, subsection (b)(2) states that a “resident of the United States is an individual who is a resident alien under 26 U.S.C. 7701(b) and the regulations thereunder . . . .” The Government fails to cite to any case law or statue indicating otherwise, and the Court finds none. As such, because the Court finds the Treaty applicable to Aroeste, then the residence provisions of the Treaty, or the “tie breaker rules” dictates whether Aroeste may be treated as a nonresident alien.
Aroeste v United States – Order 20 Nov 2023 (p. 14)
This is the third court case (the other two were in U.S. Tax Court) I have had over the last several years where the IRS tried to assess substantial penalties and taxes against LPRs who resided substantially outside the United States. The other two cases were conceded by the IRS prior to going to trial. One case had over US$40M at stake as assessed by the IRS. This case, in federal district court, was pushed all the way to this favorable (to Mr. Aroeste and those around the world in similar circumstances) outcome by the government. We were successful with all of these non-U.S. citizen cases (two brothers from Mexico and an individual from Germany).
The Number of LPRs Declined in the Corona-virus Pandemic
Not surprisingly, the number of new LPRs into the U.S. dropped substantially in correlation with the Corona-virus pandemic. See, the Office of Immigration Statistics, 28 Sept. 2021: Fiscal Year 2021 U.S. Lawful Permanent Residents Annual Flow Report. The Figure 1 (highlighted by me) and that report notes:
Just over 700 thousand persons became LPRs in 2020, as reduced international travel during the COVID-19 pandemic and policy changes brought new LPR admissions in 2020 to their lowest
level since 2003. The majority of these LPRs (62 percent) were already present in the United States when they were granted lawful permanent residence. A little under two-thirds (63 percent) were granted LPR status based on a family relationship with a U.S. citizen or current LPR. The leading countries of birth of new LPRs were Mexico, India, and People’s Republic of China (China). In 2020, there was a 31 percent reduction in U.S. grants of LPR status compared to 2019.
Largely due to the COVID-19 pandemic, LPR flows in 2020 were not representative of typical trends (Figure 1). Travel restrictions and processing slowdowns generally resulted in fewer inflows, while foreign-born residents within the United States also confronted immigration status-specific COVID-19 vulnerabilities.5
The key tax question for LPRs who no longer live in the U.S. (or who are planning to leave the U.S. to live in another country) is: Are they (or will they become) a so-called “long-term resident” as defined in the federal “expatriation” tax law?
IRC Section 877(e)(1) and (2) define a “long-term resident” and these paragraphs are included below in their entirety:
(1) In general
Any long-term resident of the United States who ceases to be a lawful permanent resident of the United States (within the meaning of section 7701(b)(6)) shall be treated for purposes of this section and sections 2107, 2501, and 6039G in the same manner as if such resident were a citizen of the United States who lost United States citizenship on the date of such cessation or commencement.
(2) Long-term resident
For purposes of this subsection, the term “long-term resident” means any individual (other than a citizen of the United States) who is a lawful permanent resident of the United States in at least 8 taxable years during the period of 15 taxable years ending with the taxable year during which the event described in paragraph (1) occurs. For purposes of the preceding sentence, an individual shall not be treated as a lawful permanent resident for any taxable year if such individual is treated as a resident of a foreign country for the taxable year under the provisions of a tax treaty between the United States and the foreign country and does not waive the benefits of such treaty applicable to residents of the foreign country.
The Next Post on this topic will break down the elements of –
(1) who will necessarily be a “long-term resident”?
(2) who may be “long-term resident”?
(3) what steps can be taken to necessarily avoid “long-term resident” status?
Finally, a discussion will be had in the last post in this series of some of the potential adverse tax consequences to “long-term residents” depending upon different factual scenarios.
Why have U.S. Citizenship Renunciation Numbers Plateaued?
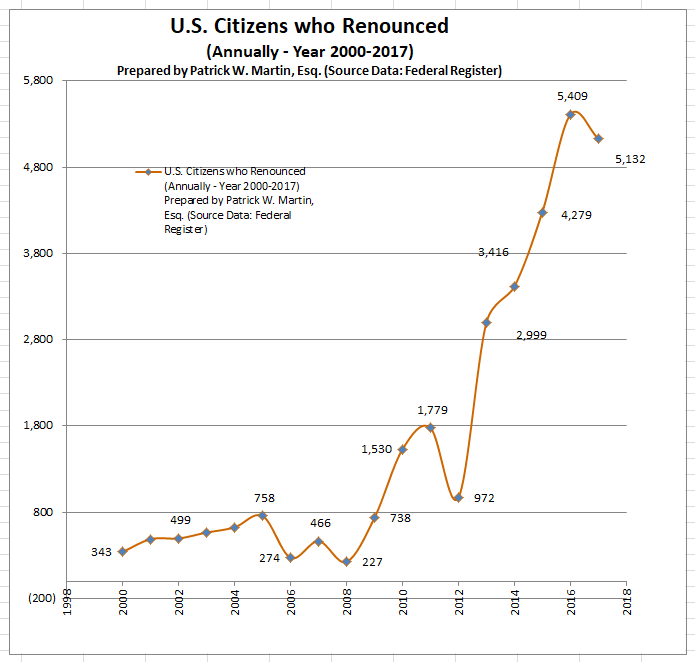
The number of U.S. citizens who have renounced has plateaued starting in 2016. That was the peak year with 5,409 renunciations followed by a similar number of 5,132 in 2017. See an older 2014 post that highlighted the then record of 2,999 for the entire year.
The data used for these running compilations, with the individuals names published can be reviewed on the federal government’s website. The complete set of lists going back to the mid-1990s can be reviewed here. Quarterly Publications. Quarterly Publication of Individuals, Who Have Chosen to Expatriate
The total number of renunciations for the first two quarters of 2018 was 2,185.
None of this answers why these numbers have stopped increasing in a ski slope fashion?
Part II: Who is a “long-term” lawful permanent resident (“LPR”) and why does it matter?
A post in August 2014 explained the basic rule of who is a “long-term resident” as that technical term is defined for tax purposes in IRC Section 877 (e)(2). There is much confusion about how the tax law defines a “lawful permanent resident” (“LPR”) versus how immigration law defines what is almost the same concept. The statutes are different and have definitions in two separate federal codes (Title 26, the federal tax provisions and Title 8, the immigration law provisions).
This follow-up comment is to highlight some key concepts about why it matters if you become a “long-term” resident as that term is defined in the tax law.
A LPR can reside for substantially shorter periods in the U.S. (shorter than the apparent 7 or 8 years identified in the statute), and still be a “long-term resident” per IRC Section 877 (e)(2) depending upon the facts of any particicular case.
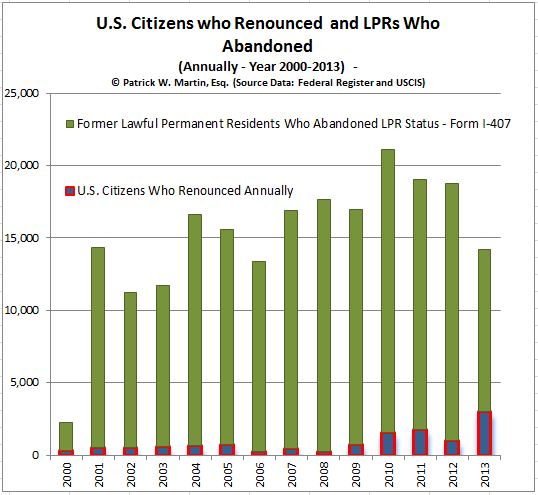
There are far more LPRs who abandon their status (formally) than U.S. citizens who formally take the oath of renunciation. See the table above reflecting those who have formally renounced U.S. citizenship versus those who have formally abandoned their LPR status.
Plenty of LPRs informally abandon their LPR status for immigration purposes by moving and living permanently outside the U.S.
There are plenty of timing issues for LPRs surrounding how and when they have “abandoned” their LPR status for purposes of IRC Section 877 (e)(2). See –
I have prepared a graphical representation going back to the year 2000, when only 343 individuals annually renounced citizenship. In 2008 there were only 227, according to the records published by the U.S. Treasury Department.
Will the current political climate in the U.S. contribute to more individuals renouncing U.S. citizenship in 2016 and beyond?
Survey of the Law of Expatriation from 2002: Department of Justice Analysis (Not a Tax Discussion)
Most discussions regarding renunciation/relinquishment of U.S. citizenship are highly focused towards the U.S. federal tax consequences. Today, the focus is on a 2002 report prepared by the DOJ for the Solicitor General, who supervises and conducts government litigation in the United States Supreme Court.
You have asked us for a general survey of the laws governing loss of citizenship, a process known as “expatriation” (also known within the specific context of naturalized citizens as “denaturalization”). See, e.g.,Perkins v. Elg, 307 U.S. 325, 334 (1939) (“Expatriation is the voluntary renunciation or abandonment of nationality and allegiance.”). Part I of this memorandum provides a general description of the expatriation process. Part II notes the relative difficulty of expatriating a person on the grounds that he has either obtained naturalization in, or declared allegiance to, a foreign state, absent evidence of a specific intention to relinquish U.S. citizenship apart from the act of naturalization or declaration itself. Part III analyzes the expatriation of a person who serves in a foreign armed force
engaged in hostilities against the United States.1
*
1 Editor’s Note: The original footnote 1 has been removed in order to preserve the confidentiality of internal government deliberations.
* * *
*
. . . In 1868, Congress declared that “the right of expatriation is a natural and inherent right of all people, indispensable to the enjoyment of the rights of life, liberty, and the pursuit of happiness.” Act of July 27, 1868, ch. 249, pmbl., 15 Stat. 223, 223; see also 8 U.S.C. § 1481 note (2000) (quoting Rev. Stat. § 1999 (2d. ed. 1878), 18 Stat. pt. 1, at 350 (repl. vol.)) (same).
*
That declaration further stated that “any declaration, instruction, opinion, order, or decision of any officers of this government which denies, restricts, impairs, or questions the right of expatriation, is hereby declared inconsistent with the fundamental principles of this government.” 15 Stat. at 224. Similarly, the Burlingame Treaty of 1868 between the United States and China recognized “the inherent and inalienable right of man to change his home and allegiance, and also the mutual advantage of . . . free migration and emigration . . . for purposes of curiosity, of trade, or as permanent resident s.” U.S.-China, art. 5, July 28, 1868, 16 Stat. 739, 740. Congress provided specific legislative authority for nullifying citizenship when, in 1907, it enacted the predecessor of the modern federal expatriation statute.
* * *
*
II. Foreign Naturalization or Declaration of Foreign Allegiance
*
Under federal law, a U.S. citizen can lose his nationality if he voluntarily “obtain[s] naturalization in a foreign state… after having attained the age of eighteen years.” 8 U.S.C. § 1481(a)(1). Likewise, a citizen of the United States could be expatriated if he voluntarily “tak[es] an oath or mak[es] an affirmation or other formal declaration of allegiance to a foreign state or a political subdivision thereof, after having attained the age of eighteen years.” Id. § 1481(a)(2). In either case, however, no loss of citizenship may result unless the citizen acts “with the intention of relinquishing United States nationality.” Id. § 1481(a).
*
The most common obstacle to expatriation in cases involving foreign naturalization or declaration of foreign allegiance is sufficient proof of a specific intention to renounce U.S. citizenship. Intent need not be proved with direct evidence, to be sure. It can be demonstrated circumstantially through conduct. Thus, in some cases, such as service in a hostile foreign military at war with the United States, the act of expatriation itself may even constitute “highly persuasive evidence…of a purpose to abandon citizenship.” Terrazas , 444 U.S. at 261 (quotations omitted).
*
* * *
Dual nationality, the Supreme Court has explained, is “a status long recognized
in the law.” Kawakita, 343 U.S. at 723. See also id. at 734 (“Dual nationality . . . is
the unavoidable consequence of the conflicting laws of different countries. One
who becomes a citizen of this country by reason of birth retains it, even though by
the law of another country he is also a citizen of it.”) (citation omitted); Savorgnan, 338 U.S. at 500 (although “[t]he United States has long recognized the general undesirability of dual allegiances[,] . . . [t]emporary or limited duality of citizenship has arisen inevitably from differences in the laws of the respective nations as to when naturalization and expatriation shall become effective . . .
See WSJ = World/Expats – For an Excellent Overview of U.S. Taxation for U.S. Citizen Individuals in Plain English
For an excellent overview (without penalty hype or exaggeration of the U.S. tax law), read the following article from Eric Scali of H&R Block’s expat-focused service titled –Puncturing 7 Common Myths about U.S. Expat Tax Rules, Nov. 15, 2015, WSJ = Globe, EXPAT, For global nomads everywhere
Myth #1: Individuals living outside of the U.S. and filing tax returns with a foreign government don’t have to file annual U.S. tax returns.
Myth #2: Expats only need to report their U.S. income on their U.S. tax return.
Myth #3: If their foreign income is below the Foreign Earned Income Exclusion (FEIE), expats don’t need to file a U.S. tax return.
Myth #4: Work performed by an expat within the U.S. but paid by an expat’s foreign employer is foreign income because it’s paid by the foreign employer and not issued on a W-2.
Myth #5: Expats’ non-U.S.-based pension plans have the same tax treatment in the U.S. as they do in their country of residence.
Myth #6:When expats receive certain items of income, they’re only taxable in their country of residence under the rules provided for in the income tax treaty the foreign country has with the U.S.
Myth #7: An expat’s foreign investments are treated the same as they are in the foreign country.
Unfortunately, I have heard all of these and more (many times over) during my professional career as an international tax lawyer (and an accountant in the late 1980s) from both individuals and their tax advisers both inside the U.S. and outside the U.S. As someone who lives with their family outside the U.S., I have a good understanding about the difficulty of finding good U.S. tax resources that accurately and simply explain these very complex laws.








 2017. See an older 2014 post that highlighted the then record of 2,999 for the entire year.
 how immigration law defines what is almost the same concept. The statutes are different and have definitions in two separate federal codes (Title 26, the federal tax provisions and Title 8, the immigration law provisions).