Wowzers! Consular Fees for Processing U.S. Citizenship Renunciations Decreased to US$450 Fee – ($320 – inflation adjusted)!
More than a dozen years ago, I wrote a blog when the State Department jacked up the fee to US$ 2,350.

As of September 2026, the U.S. Department of State has reduced the U.S. citizenship renunciation fee from $2,350 to $450. Adjusted for inflation since the 2014 increase, $450 today is equivalent to approximately $320 in 2014 dollars — the lowest real-terms cost for renunciation in more than a decade.
This is what the updated government website provides regarding renunciation:
Overview
Relinquishment of U.S. citizenship by performing certain statutory expatriating acts, including taking the oath of renunciation, voluntarily and with the intent of relinquishing U.S. citizenship, is a personal right that cannot be exercised on a person’s behalf. For example, a person’s parent(s) or legal guardian may not take the oath of renunciation for that person. A Certificate of Loss of Nationality (CLN) approved by the Department of State is the final agency determination of loss of U.S. nationality.
NOTE: STEPS 1-4 below outline the process for requesting a CLN based on taking an oath of renunciation before a U.S. diplomatic or consular officer abroad under Immigration and Nationality Act (INA) Section 349(a)(5), 8 USC 1481(a)(5). For information on the parallel process to request a Certificate of Loss of Nationality (CLN) on the basis of the commission of another potentially expatriating act under INA 349(a)(1)-(4), 8 USC 1481(a)(1)-(4), please contact your location by selecting it below.
Oath of Renunciation of U.S. Nationality
Embassy, consulate, or office providing consular services process requests to take the oath of renunciation of U.S. citizenship. Minors, individuals who do not read or write English, individuals with mental health or cognitive disability or impairment and/or guardianship, and those for whom loss of U.S. nationality would result in statelessness are invited to contact your location to discuss taking the oath of renunciation.
Taking an oath to renounce U.S. nationality before a U.S. diplomatic or consular officer overseas is a serious and irrevocable act. Therefore, you should carefully consider and fully understand the consequences and ramifications of this act prior to your decision to begin the process.
Steps to Take
STEP 1: Review the legal requirements and consequences/ramifications of taking the oath of renunciation of U.S. citizenship.
Please read the information provided by the embassy, consulate, or office providing consular services and available online at the Department of State and Internal Revenue Service links below regarding the legal requirements for taking the oath of renunciation before beginning this process. Loss of U.S. nationality is irrevocable, and you should fully understand the consequences and ramifications before beginning this process.
For questions related to possible U.S. tax implications, please contact the Internal Revenue Service and/or review the Joint Foreign Account Tax Compliance Act (FATCA) FAQ .
For questions related to Social Security Administration (SSA) or other federal benefits, please contact your location.
Department of State and Internal Revenue Service links:
STEP 2: Email your location to initiate the process and receive instructions. Gather and submit scanned copies of the required documents and schedule your first interview.
To schedule an initial interview, which will be conducted by telephone or in-person at the embassy, consulate, or office providing consular services, please send an email to your location. Canada, Bern, Berlin, Amsterdam, Australia (Sydney and Melbourne), Singapore, Brussels, and Paris provide electronic first interviews
Applicants should personally review all documents and prepare all forms provided by the embassy, consulate, or office providing consular services in accordance with the instructions. DO NOT SIGN ANY FORMS BEFORE YOUR FINAL INTERVIEW.
STEP 3: Schedule and attend the final interview at the embassy, consulate, or office providing consular services with all required original documents and pay the fee.
Schedule your final interview appointment according to embassy, consulate, or office providing consular services instructions. On the day of your final interview appointment, you must bring all of the original documents you previously submitted by email. You will be asked to reschedule if you do not have the required documents at the time of your final interview appointment.
Your Consular Report of Birth Abroad, and Certificate of Naturalization or Citizenship, if applicable, generally will be retained by the embassy, consulate, or office providing consular services during the remainder of the process and then returned to you. Your U.S. passport also will be retained and, if your Certificate of Loss of Nationality is approved by the Department of State, it will be canceled before it is returned to you upon your request. If you need to travel to the United States on your U.S. passport after the second interview but before the Certificate of Loss of Nationality has been approved, please so advise the embassy, consulate, or office providing consular services at the second interview.
You will meet with a consular officer for your second interview and you will be given another opportunity to review the documents that you have already filled out (but not signed) Form DS-4079, Questionnaire; Loss of United States Nationality; Attestations prior to signing them and taking the oath of renunciation.
Fee: Immediately after taking the oath of renunciation, you must pay the non-refundable current fee of US $450 for administrative processing of a request for a Certificate of Loss of Nationality. The fee is not waivable, nor is it refundable if your request for a Certificate of Loss of Nationality is denied.
Step 4: Receive the Certificate of Loss of Nationality if approved by the Department of State
The Department of State will review each request for a Certificate of Loss of Nationality to determine whether there is a legal basis to approve it. This step may take several months or more. The embassy, consulate, or office providing consular services may contact you for further information before the Department of State decides your case. The embassy, consulate, or office providing consular services will email you if and when your request has been approved. If your request is denied, the embassy, consulate, or office providing consular services will send you an email attaching a denial letter.
NOTE: STEPS 1-4 above outline the process for requesting a CLN based on taking an oath of renunciation before a U.S. diplomatic or consular officer abroad under Immigration and Nationality Act (INA) Section 349(a)(5), 8 USC 1481(a)(5). For information on the parallel process to request a Certificate of Loss of Nationality (CLN) on the basis of the commission of another potentially expatriating act under INA 349(a)(1)-(4), 8 USC 1481(a)(1)-(4), please contact your location for inquiries.
Fees (Prices in U.S. Dollars)
Non-refundable fee of $450 USD at the time of the appointment.
What the Fee Reduction Does Not Change
The $450 consular fee covers only the State Department’s administrative processing of the renunciation appointment. It has no effect on the U.S. tax consequences of renunciation, which are governed entirely by separate federal tax law.
A U.S. citizen who renounces citizenship in 2026 still faces the same IRS obligations as before the fee change. Form 8854, the Initial and Annual Expatriation Information Statement, must still be filed. The five-year tax compliance certification is still required. If the renouncing individual qualifies as a covered expatriate under the three IRS tests — net worth, average annual tax liability, and compliance certification — the Section 877A mark-to-market exit tax still applies in full.
The fee reduction makes the administrative step of renouncing less expensive. It does not reduce the tax cost.
Is the $450 Fee the Only Cost of Renouncing?
No. The consular fee is the smallest cost most people encounter. The substantive costs of renunciation depend entirely on the individual’s financial situation and filing history. For individuals who are covered expatriates, the Section 877A exit tax can represent a significant liability. For individuals with unfiled FBARs or unreported foreign accounts, FBAR penalties may apply separately.
Attorney fees for proper pre-renunciation planning, tax preparation for Form 8854, and any exit tax liability are the costs that vary significantly from person to person. The $450 appointment fee is the one cost that is the same for everyone.
When Did the Fee Change Take Effect?
The State Department updated its fee schedule in September 2026, reducing the U.S. citizenship renunciation fee from $2,350 to $450 effective immediately. The $2,350 fee had been in place since September 2014, when it was increased by more than 500 percent from the prior $450 level. In real terms, adjusted for inflation since 2014, the current $450 fee is equivalent to approximately $320 in 2014 dollars.
FBAR Penalties Explained: What Happens If You Don’t File?
Few basic U.S. tax compliance questions matter more to a U.S. citizen or green-card holder living abroad than what an unfiled FBAR can actually cost in penalties. Also, a green-card holder might not have any reporting requirements at all – given the law explained in the federal district court decisions originally appealed by the government in my 9th Circuit decision: Aroeste v. United States, Case No. 22-cv-00682-AJB-KSC.
What Are the Penalties for Not Filing an FBAR?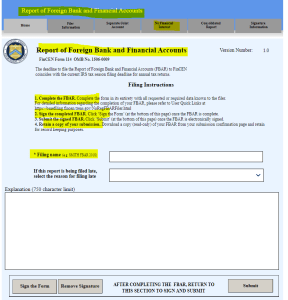
Failure to file an FBAR may result in a civil penalty if assessed by the government. The willful civil penalty is frankly more onerous than the criminal penalty that is maxed out by statute. The maximum civil penalty depends on whether the violation is determined to be non-willful or willful.
The statutory framework was initially set out by a federal district court in 2015, that also reviewed the FATCA laws, and it is worth reading the summary here:
A person who fails to file a required FBAR may be assessed a civil monetary penalty. 31 U.S.C. § 5321(a)(5)(A). The amount of the penalty is capped at $10,000 unless the failure was willful. See 5321(a)(5)(B)(i), (C). A willful failure to file increases the maximum penalty to $100,000 or half the value in the account at the time of the violation, whichever is greater. § 5321(a)(5)(C). In either case, whether to impose the penalty and the amount of the penalty are committed to the Secretary’s discretion. See § 5321(a)(5)(A) (“The Secretary of the Treasury may impose a civil money penalty[.]”)
Crawford v. U.S. Department of the Treasury (S.D. Ohio 2015 – Case No. 3:15-cv-00250)
The IRS internal revenue manual (4.26.16.4.1) summarizes how and why the IRS has purported authority to assess penalties for FBAR Title 31 violations as set forth below:
As of April 8th 2003, IRS was delegated the authority to assess and collect FBAR civil penalties. 31 C.F.R. § 103.56(g). The delegation includes the authority to investigate possible FBAR civil violations, provided in Treasury Directive No. 15-41 (Dec. 1, 1992), and the authority to assess and collect the penalties for violations of the reporting and recordkeeping requirements.
Was this delegation of authority from FinCEN to the IRS even valid as a matter of law? That questions has not been challenged yet in the courts.
When performing these FBAR functions, the IRS is not acting under Title 26 (the federal tax law) but, instead, is acting under the authority of Title 31 (the Bank Secrecy Act). Provisions of the Internal Revenue Code generally do not apply to FBARs and visa-versa. Does the IRS even have lawful authority to manage and assess these penalties – which previously were in the hands of the more obscure FinCEN.
What Is the Penalty for a Non-Willful FBAR Violation?
A non-willful FBAR violation may result in a civil penalty of up to $10,000 per violation. The Supreme Court has now held (after years of litigation) that, for non-willful violations, the penalty generally applies singularly – per report – rather than per account as the IRS argued for years. Bittner v. United States, 598 U.S. 85, 143 S. Ct. 713 (2023)
For years the government (IRS) read that $10,000 could be assessed for each account, and the Supreme Court finally resolved the question in 2023 against the government. The Ninth Circuit had ruled against the government in United States v. Boyd, 991 F.3d 1077 (9th Cir. 2021) and the Fifth Circuit (United States v. Bittner, 19 F.4th 734 (5th Cir. 2021)) overturned the federal district court in the eastern district of Texas in United States v. Bittner, No. 4:19-CV-415, 2020 WL 4200057 that had originally ruled in line with Boyd.
See an article I wrote on this issue along with two of my international tax colleagues at Chamberlain Hrdlicka: published as a Special Report in Tax Notes:
On February 28th, 2023, the Supreme Court of the United States (“SCOTUS”) resolved in Bittner that the applicable non-willful FBAR penalty is not measured by every foreign account of the individual as the Service had argued for years and as they put into their IRM. The author had the opportunity to draft as one of the co-authors of the ACTEC amicus brief that was filed in Bittner. After Bittner, the total maximum penalty per year is $10,000 for non-willful violations. A maximum penalty of $50,000 (x5 years) applied per the SCOTUS versus the IRS determined amount of US$2.7M+ multiplying each account by $10K.
“Best read, the BSA treats the failure to file a legally compliant report as one violation carrying a maximum penalty of $10,000, not a cascade of such penalties calculated on a per-account basis.” The ACTEC brief was cited by the majority opinion- “ We see evidence, too, that the point of these reports is to supply the government with information potentially relevant to various kinds of investigations, criminal and civil alike. But what we do not see is any indication that Congress sought to maximize penalties for every nonwillful mistake (whether a late filing, a transposed account number, or an out-of-date bank address). See Brief for American College of Trust and Estate Counsel as Amicus Curiae 5–7.”
Importantly, the U.S. Supreme Court rejected the IRS interpretation of multiple per year non-willful FBAR penalties in Bittner v. United States, 598 U.S. 85, 143 S. Ct. 713 (2023).
What Is the Penalty (Civil) for a Willful FBAR Violation?
A willful FBAR violation may result in substantially higher penalties. The maximum penalty is generally based on the greater of a statutory amount or a percentage of the account balance.
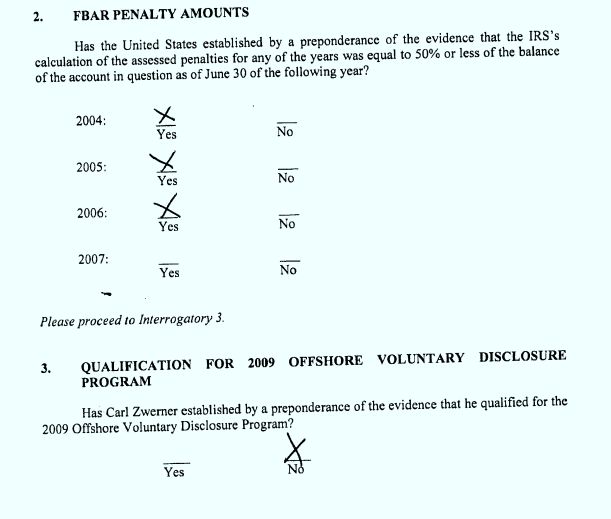
Because the willful penalty is measured against the account itself, it can exceed the balance entirely once assessed over several years. See, United States v. Carl R. Zwerner, Case No. 1:13-cv-22082-CMA (2014)
The government was on its face, very “successful” in the Zwerner case in convincing a jury they should render a verdict for 3 years of FBAR 50% willfulness penalties (150% of the account balance in total). The government tried to assert 4 years of willfulness penalties, which would have been 200% of the account balance; all under a civil penalty provision in the statute, that looks like a criminal penalty on its face and via its outcome.
In Zwerner, the taxpayer did come forward and disclose the unreported foreign accounts, and received a letter from the IRS CI on February 17, 2009, stating that ” . . . based upon the information provided a criminal investigation will not be initiated at this time. . . ” Nevertheless, the government pursued 50% civil willfulness penalty assessments for multiple years (4 years). The Tax Division of the Justice Department pursued this case through trial, incurring the time and costs of government resources, arguing Mr. Zwerner owed a total of $3,630,119.29 (on an account with a maximum value during the years at issue of apparently no more than US$1.69M) in their Motion for Summary Judgement.
In Count Six, Plaintiffs contend that the FBAR “Willfulness Penalty” is unconstitutional under the Excessive Fines Clause. Plaintiffs allege the Willfulness Penalty is designed to punish and is therefore subject to the Excessive Fines Clause. Plaintiffs further allege the Willfulness Penalty is grossly disproportionate to the gravity of the offense.
Can the IRS Penalize Each Foreign Account Separately?
Not for non-willful violations as explained above. The “jury is still out” regarding to what extent multiple years of 50% willfulness penalties may be assessed. The IRS has tempered their approach a bit over the last decade – particularly as of late, after losing a number of key FBAR cases going to trial.
Is the FBAR Penalty Mandatory?
No. The statute provides that the government may assess an FBAR penalty, giving the government discretion over whether, and in what amount, a penalty is imposed.
The distinction between what the statute permits and what it requires is easily missed, and it matters a great deal for individuals who have not filed FBARs. Especially for those residing outside the United States – including those individuals with green cards.
The relevant statutory provision is that “The Secretary of the Treasury may impose a civil money penalty on any person who violates, or causes any violation of, any provision of section 5314.” 31 U.S.C. Section 5321(a)(5)(B).
How Long Does the IRS Have to Assess an FBAR Penalty? – Six Years –
The IRS generally has six years to assess a civil FBAR penalty. This limitations period differs from the rules that apply to federal income tax returns.
The two bodies of law run on different time clocks.
The FBAR (the Foreign Bank Account Report) comes from a different law than the federal income tax. The income tax is from Title 26 of the U.S. Code. The FBAR comes from the Bank Secrecy Act, which is Title 31. These two laws are very different, with very different obligations and rights. One of the important differences is the time frame in which the government can assess penalties for not complying.
A statute of limitations is the time frame in which the government has to assess penalties for not complying with the law. For foreign accounts, these time periods are not the same under Title 31 (the Bank Secrecy Act) as they are under Title 26 (the income tax law). The gap between the two is what makes this area confusing.
No. When a U.S. citizen or LPRs residing overseas fails to file an income tax return, the time period for the IRS to make tax assessments never lapses. There is effectively no statute of limitations against the IRS in that situation. The clock to assess does not start until a return is filed.
Title 31, the Bank Secrecy Act, is different. It does have a time period that runs against the U.S. federal government, even if the FBAR was never filed. For civil assessments of penalties, that time period is 6 years. This important distinction helps drive strategic decisions of foreign account holders if they have failed to file FBARs.
There is a statute of limitations whether or not an FBAR was filed. Hence if a USC or LPR neglected to file an FBAR for the year 2006, for instance, the time period for the government to assess penalties has lapsed long ago. See, When does the Statute of Limitations Run Against the U.S. Government Regarding FBAR Filings?
How Does the IRS Collect an FBAR Penalty?
An FBAR penalty is generally not collected through the IRS’s ordinary tax lien and levy procedures. Instead, the government is typically required to bring a civil action to collect an unpaid penalty. They also have “off-set” rights that can be invoked against other payment amounts owed to the taxpayer. See, Bureau of the Fiscal Service and their powers through the 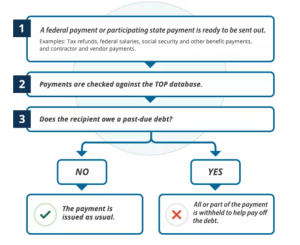 Treasury Offset Program (TOP).
Assessing a penalty and actually collecting it are separate problems for the government, particularly where the taxpayer and the assets are outside the United States.
The collection of the FBAR penalty is not as easily collected under the law, as is a tax claim. A Title 26 tax lien and levy claim against the taxpayer’s property cannot be used to collect an FBAR penalty. Instead, the government has rights of set-off and will typically be required to bring a judicial action in Court to enforce the penalty assessment. See, an early case, United States v. Williams, 489 F. App’x 655 (4th Cir. 2012), where the government sued to collect the 50% FBAR willfulness penalty.
The laws of many countries outside the U.S. often conclude that enforcing these FBAR penalties against a U.S. citizen or LPR, inside that person’s home country, violates the laws of that country. Canada is one example. Calgary based tax attorney Roy Berg has written on the question of whether the IRS can collect FBAR penalties under the Canada-US Treaty.
The “Revenue Rule” was a common law concept that generally prohibited the U.S. government from assisting in the collection of taxes of another country. Hence, the U.S. Treasury renegotiated the treaties with five countries (including Canada) that now have a specific treaty provision such as XXVI A above:
As a result of these cases and the Revenue Rule, the U.S. and Canada modified their income tax treaty to (at least in theory) to allow for the international enforcement of taxes. The U.S. now has five income treaties with “mutual assistance” provisions: Canada, Sweden, France, Denmark, and the Netherlands (with a clause in the newly negotiated, but yet to go into force, Swiss treaty).
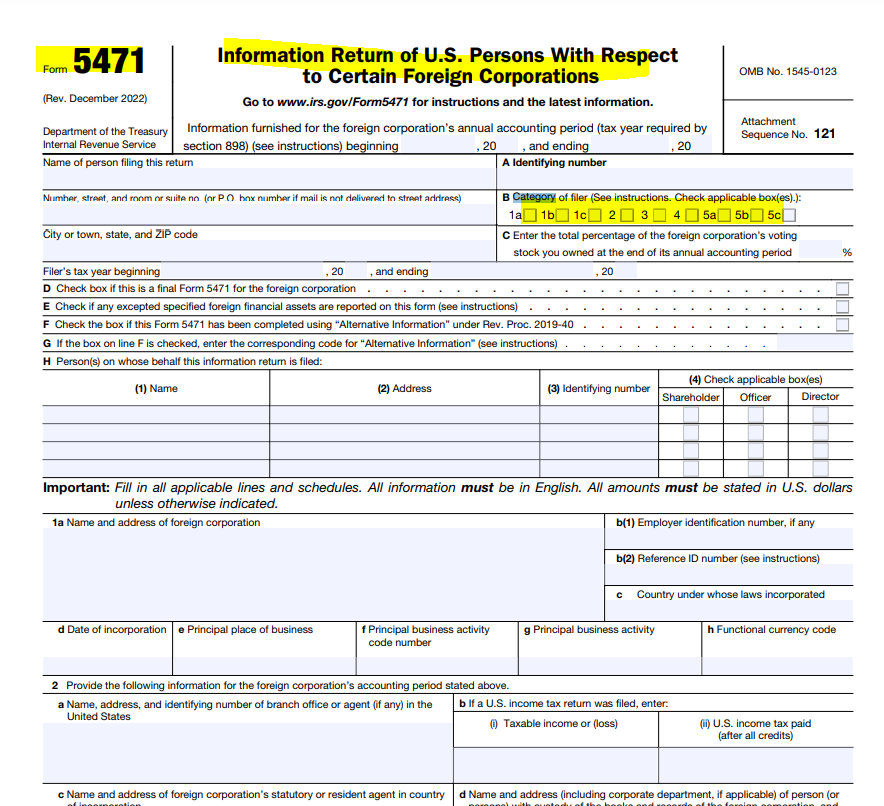
In the Dewees case, we learned that the assistance in collection provision is not merely a theoretical tool that can be used in collecting taxes. The IRS was successful in a long running case with FBAR penalties and Title 26 penalties for failure to file IRS forms 5471 regarding the U.S. citizens Canadian companies. He lived in Canada. See, Dewees v. United States, 272 F. Supp. 3d 96 (D.D.C. 2017), which was subsequently affirmed by the D.C. Circuit Court of Appeals (Dewees v. United States, 767 F. App’x 4 (D.C. Cir. 2019)). The actions of both the Canadian (CRA) and U.S. governments (IRS and District Court Judge), made the provision effective. The US$120,000 penalty, that has nothing to do with any U.S. income taxes owed (nor FBAR penalty), was collected by the IRS; a penalty under 26 U.S.C. § 6038(b) for failure to file informational returns – .
Can an FBAR Violation Lead to Criminal Charges?
Yes, but not every FBAR violation is a criminal matter. Criminal liability generally requires proof of willful conduct and carries a burden of proof on the government – (beyond a reasonable doubt) – and always depends on the facts of the case.
Yes. A U.S. citizen or LPR living overseas could in theory become criminally liable for willfully not filing the FBAR form. Criminal liability carries different legal consequences than a civil penalty. These are not easy cases for the government – and hence they rarely have brought criminal FBAR cases for taxpayers residing overseas. It all depends upon the facts.
IRS Criminal Investigation (division) has been delegated the authority to investigate possible criminal violations of the Bank Secrecy Act. 31 C.F.R. §103.56(c)(2). This should not be taken lightly.
Yes, there are also statutes of limitations for criminal charges the government brings for FBAR violations. The law gets much more complex here, especially when the taxpayer is residing outside the U.S. In that situation, the time period can be tolled or suspended in favor of the government, which extends the window to bring charges. Jack Townsend (an amazing, now retired criminal tax defense lawyer who has contributed extensively to the tax law practice) has written on the statutes of limitations for FBAR noncompliance related to tax reporting. Jack is co-author of Tax Crimes – John (“Jack”) Townsend with my law partner the esteemed criminal tax defense lawyer Larry Campagna along with Steve Johnson, and Scott Schumacher.
U.S. citizens residing overseas clearly have FBAR filing requirements – if they meet the thresholds. The law is quite different for those with “green cards” residing predominantly overseas in a country with an income tax treaty with the U.S. Here, it gets a lot more complicated, but see my case of Aroeste v. United States, Case No. 22-cv-00682-AJB-KSC (2023) that was appealed to the Ninth Circuit by the government after they lost.
What Can We Learn from Real FBAR Penalty Cases?
Reported cases show that the outcome of an FBAR penalty dispute depends heavily on the facts. They also demonstrate that proposed penalties may be successfully challenged in appropriate cases.
One case makes the point better than any summary of the rules could.
This case was covered extensively by various tax journalists and followed by tax professionals around the world from the time it started until it concluded. I know, because I was the lead attorney representing the then 91 year old widow from Canada, dear Mrs. Margaret Jones. The pleadings in the case can be viewed here – Margaret J. Jones v. United States (2:19-cv-04950)
In my view, this case should have never ended up before the U.S. District Court. The IRS erred in making a determination of “willful blindness” against Mrs. Jones who was legally blind at her advanced age. They conceded Mrs. Jones had no actual knowledge of the reporting requirement. She was advised for more than two decades by a CPA, both she and her late husband (an immigrant from New Zealand). They both had accounts that were decades old from their respective countries – Canada and New Zealand. Held openly and directly for the majority of their lives.
Mrs. Jones did the right thing by going to the Streamlined Filing Procedure (the streamlined filing procedure) and correcting her errors on her tax returns. She was then selected by the IRS for audit (because of that filing) where she got a tax refund of over $20,000. For that effort, time and expense, the IRS turned around and slapped her with US$3.4M of “willful blindness” penalties regarding her accounts in Canada and New Zealand, most of which were her husband’s accounts. Her late husband served in World War II while living in New Zealand before moving to the U.K. then Canada (where he met Mrs. Jones) and then on to the U.S. They both had high school diplomas.
The case was set for a jury trial (on two occasions) but Judge Selna postponed it on both occasions due to the Corona-virus. Unfortunately, Mrs. Jones never had her day in Court where I believe a jury would have found that the government did not carry its burden against Mrs. Jones and her late husband. Not even a close call. Her facts were not nefarious, unlike most of the cases where sophisticated taxpayers have been hiding their assets from the IRS, such as in Swiss bank accounts.
After the government conceded the bulk of the case and it was dismissed just before Christmas of 2020, Mrs. Jones passed away shortly afterwards. May her Soul Rest in Peace.
The DOJ drives the bus (NOT the IRS) once the case falls into their hands.
A jury trial should always be considered in the right case, a good faith taxpayer case, as jurors will generally see and understand the big picture.
By contrast, in Zwerner the penalty amount apparently sustained by the jury has been reported as “. . . $2,241,809 on an offshore account that had an apparent high balance of $1,691,054. . . “
The author has spoken on defending Title 31 FBAR penalties at the University of San Diego School of Law – International Tax Institute, alongside Caroline D. Ciraolo, former Acting Assistant Attorney General of the Justice Department’s Tax Division, and Robert S. Horwitz; and many other panels and forums advising clients on these FBAR issues. Seek advice on FBAR issues if you have a filing requirement.
What Is the IRS Non-Filer Program and How Does It Affect Americans Abroad?
U.S. Citizens and Green-Card Holders Abroad: The IRS Non-Filer Program Explained
On this page:
Read the full analysis here.
What is U.S. citizenship-based taxation, and who does it reach?
The U.S. taxes based on citizenship, not just on where a person lives. A U.S. citizen who has spent nearly all of their life outside the U.S. can still fall within the U.S. tax system. Lawful permanent residents (green-card holders, also called LPRs) residing outside the U.S. can be reached as well. Many people in both groups are shocked to learn how broad this scope is.
Why does the IRS focus so heavily on accounts and assets outside the U.S.?
In recent years the IRS and the Tax Division of the Department of Justice (DOJ) have aggressively pursued assets and accounts located outside the U.S. That pursuit has put a keen focus on the offshore holdings of U.S. citizens and green-card holders who live abroad.
What are the “New Filing Compliance Procedures for Non-Resident U.S. Taxpayers”?
In August the IRS articulated its position for U.S. citizens and lawful permanent residents residing outside the U.S. in a document titled “New Filing Compliance Procedures for Non-Resident U.S. Taxpayers.” It sets out how the IRS approaches the filing obligations of those taxpayers.
What is the IRS non-filer program?
The IRS has had, for years, a specific program aimed at “non-filers,” meaning persons who do not file U.S. income tax returns. The program is detailed in the Internal Revenue Manual (IRM), the IRS’s internal handbook of procedures. It can apply to U.S. citizens and green-card holders living overseas who have not filed.
What can happen if a U.S. citizen or green-card holder living abroad never files a U.S. return?
When a taxpayer does not file, the IRS may prepare a “substitute return” on that person’s behalf. A substitute return is a return the IRS files for the taxpayer, rather than one the taxpayer files. This can apply to U.S. citizens and lawful permanent residents residing overseas who are non-filers. Anyone facing this situation may want to consult an experienced attorney.
Where is the non-filer program actually written down?
The non-filer program is laid out in the Internal Revenue Manual at section 4.19.17, the Non-Filer Program. Its subsections cover the full process:
- 4.19.17.1 — Non-Filer Program
- 4.19.17.2 — Non-Filer Strategy
- 4.19.17.3 — Non-Filer Processing
- 4.19.17.4 — Non-Filer Penalties
- 4.19.17.5 — Undelivered Mail
- 4.19.17.6 — Taxpayer Replies
- 4.19.17.7 — Closures, Non-Examined
Read the full analysis here.
Why Are Foreign Banks Closing Accounts for Americans Abroad?
Is it hype, or is it real? Many U.S. citizens and lawful permanent residents (green-card holders) living overseas have heard that foreign banks are closing their accounts. Here is what actually shows up in practice, and why so many people are moving their money home.
On this page
Read the full analysis here.
Are foreign banks really closing the accounts of Americans living overseas?
It is hard to know with certainty how accurate these claims are. If it has happened to you, of course you will know it. In practice, account closings have turned up in places such as Hong Kong, London, Geneva, and Zurich. But they do not appear to be a widespread practice, at least not anecdotally.
What have news reports said about banks cutting off American expats?
Several published reports have raised the issue, including:
- The Wall Street Journal, “Expats Left Frustrated as Banks Cut Services Abroad” (11 Sept 2014).
- The Wall Street Journal opinion piece by Colleen Graffy, “How to Lose Friends, Citizens and Influence.”
- Time Magazine, “Swiss Banks Tell American Expats to Empty Their Accounts.”
- The Huffington Post (Aug 2014), “Expatriate Tax Sense or Broad-Brush Overreach: The U.S. Foreign Account Tax Compliance Act (FATCA).”
- The New York Times (April 2013), “Overseas Finances Can Trip Up Americans Abroad.”
- The Association of Americans Resident Overseas, on Americans abroad being denied access to banking and investment opportunities.
- American Citizens Abroad, which compiles various news accounts of accounts being closed.
Does the size of the account change how a foreign bank responds?
It appears to. For individuals with large investment accounts, for example greater than US$1 million, banks seem to accommodate them, or at least require them to move their assets to a U.S. affiliate or branch. Those with smaller accounts, for example less than US$100,000, appear to see a broader brush stroke of closures.
If foreign banks aren’t the main driver, who is closing these accounts?
Much of it is the individual’s own decision, not the bank’s. What has been widespread in practice is a plan by individuals to close foreign financial accounts and relocate the assets to a U.S. financial institution. This includes U.S. citizens and lawful permanent residents (green-card holders) living outside the U.S. The move is the individual’s choice, not the financial institution’s.
Why are U.S. citizens and green-card holders abroad choosing to close their foreign accounts?
The reason is generally not FATCA (the Foreign Account Tax Compliance Act) itself, but a desire to reduce the compliance costs of filing and reporting on foreign accounts. FATCA seeks to co-opt foreign banks as long-arm enforcement of U.S. tax law. Even so, the driver people cite is cost, not the statute. Multiple tiers of reporting of foreign assets is now required. It can cost a small fortune to retain a good international tax adviser who is aware of these reporting requirements.
What reporting makes holding foreign accounts so expensive?
Two main layers apply to U.S. citizens and lawful permanent residents living outside the U.S.: the FBAR (the Foreign Bank Account Report) and IRS Form 8938 (Specified Foreign Financial Assets). For those with significant assets and numerous accounts, the professional fees and costs of reporting these accounts accurately can become exorbitant. That is especially true when the risk of potentially devastating civil penalties is weighed into the mix.
What penalties are people worried about?
The IRS now regularly threatens large, multiple-year 50% willfulness penalties for those who did not file an FBAR. This risk is more than just perceived. The Zwerner FBAR case is one example, and it has been described as probably a Pyrrhic victory for the government for U.S. citizens and lawful permanent residents living outside the U.S. The combination of cost, compliance burden, and penalty risk is what drives many people to act.
Is it actually illegal for a U.S. person to hold a foreign bank account?
No. There is no legal restriction for a U.S. citizen to hold foreign accounts. A U.S. citizen or lawful permanent resident residing outside the U.S. will generally find it easier, from a lifestyle and personal financial management perspective, to have an account in their home country. The irony is that the practical effect pushes in the opposite direction.
Where are these assets ending up?
The practical effect, anecdotally, is that U.S. financial institutions are receiving these assets and investments. As individuals close foreign accounts to cut compliance costs and penalty risk, the money flows back into the U.S. rather than staying in their home country abroad.
Read the full analysis here.
What Are the Risks of Using the IRS Streamlined Filing Program?
On this page:
Read the full analysis here.
The IRS announced a new “streamlined” filing program in June 2014 for US citizens and lawful permanent residents with unreported foreign accounts. Here is how the program works and where its legal risks lie.
What is the IRS “streamlined” program for offshore accounts?
The streamlined program is an administrative procedure the IRS announced in June 2014 for US citizens (USCs) and lawful permanent residents (LPRs, or green-card holders) who did not file US tax returns, information returns, or FBARs (FinCEN Form 114, the Foreign Bank Account Report) covering their foreign accounts. An earlier version was announced in June 2012 and has since been removed from the IRS website. The program asks the taxpayer to file under a certification, and for US residents to pay a “5% miscellaneous offshore penalty.” It is an administrative procedure, not a change in the underlying law.
Does the streamlined program give any legal protection or finality?
No. Legally speaking, this administrative procedure provides no legal protection or finality to the taxpayer. It does not protect against penalties for failure to file tax returns, failure to file information returns, or failure to file FBAR forms. It also does not protect against IRS audits of prior years while the statute of limitations is still open. The IRS or the Justice Department can still fully pursue a US citizen or green-card holder who did not properly file US income tax returns, information returns on foreign assets, or FBARs for prior years, as provided under the law.
What is the “5% miscellaneous offshore penalty”?
For US residents using the streamlined program, the “5% miscellaneous offshore penalty” is an amount equal to 5% of the relevant foreign assets that the taxpayer agrees to pay in order to participate. It is not a penalty that exists under the law in the first place, and it may have no correlation with any income taxes actually owing. As a result, a good-faith taxpayer who made an inadvertent mistake about complex tax provisions can end up paying a portion of their principal assets, not just tax.
Can the IRS be required to refund the 5% penalty if you change your mind?
No. Under the terms of the Certification, the government will never be required to refund the 5% miscellaneous offshore penalty. The taxpayer waives “all defenses against and restrictions on the assessment and collection of the [5%] miscellaneous offshore penalty.” It is a one-way street. Once the money is paid it does not come back, even though the penalty is not something contemplated under Title 26.
What does the streamlined certification require, and who wrote it?
The certification is a statement the taxpayer signs under penalties of perjury. It is not drafted in the taxpayer’s own words; it is drafted by the US federal government. By signing, an individual may expose themselves to greater liability if the government later wants to challenge the certification. The certification turns on terms like “negligence,” “inadvertence,” and a “mistake” that is a “good faith misunderstanding” of the law. It is entirely unclear how the government will interpret these terms in any particular case.
Can the government challenge your certification after you file?
Yes. The IRS’s limited resources mean the vast majority of streamlined cases likely will not be challenged. Even so, there are many ways a certification can be challenged against a particular taxpayer. For example, if a taxpayer threw away the monthly bank statements for a foreign account for the year 2012, that may breach the Certification, and the terms seem to provide that all bets are off against the taxpayer. Signing under penalties of perjury is what creates this exposure.
Could the government later decide you belonged in the OVDP instead?
Yes. Some practitioners expect the government to selectively pursue taxpayers who entered the streamlined process when it believes they should have gone in under the Offshore Voluntary Disclosure Program (OVDP) instead. That determination is made by the government, not the individual taxpayer, and it can put the taxpayer in further jeopardy after they have already filed under streamlined.
Why is the FBAR described as a “trap”?
The FBAR has been used as a trap for the taxpayer. If an individual did not check the right box on Schedule B, Part III of their tax return, the government may argue they were “willfully blind” of the FBAR filing requirements, even if they genuinely did not know about them. The FBAR regulations are extremely complex. Few tax experts anywhere could pass a basic exam on what counts as a “financial interest in” or “signature authority over” an account under these regulations, with many scoring only around 75%, a C or maybe D grade.
Does the streamlined program apply to green-card holders as well as US citizens?
Yes. The same exposure applies to both US citizens (USCs) and lawful permanent residents (LPRs, or green-card holders) who did not properly file US income tax returns, information returns on foreign assets such as IRS Form 8938, or FBARs. Both groups face the same lack of protection from penalties and audits. Both can be pursued by the IRS or the Justice Department for prior years.
A concrete example: why might the program produce an unjust result?
Consider Pierre, who moved from France to the US about 10 years ago. He was an accountant in France, his English is poor, and he relies on an English-only return preparer who never asked whether he held non-US assets. Pierre inherited Swiss and French accounts worth about US$3M, plus real estate outside Paris worth about US$2.5M that generates monthly rent. His preparer always checked the “No” boxes on Schedule B, Part III and never filed FBARs or IRS Form 8938. His sophisticated French advisers told him those European assets were taxable only in France and Switzerland. Foreign taxes withheld there exceed his US tax, so after the US foreign tax credit he owes less than US$1,000 of federal income tax. To join the streamlined program, he would pay about US$325,000, which is 5% of US$6.5M.
Why would a good-faith taxpayer pay $325,000 to settle a $1,000 tax bill?
This is the core unfairness of the program for US residents. A taxpayer like Pierre may owe less than US$1,000 in federal income tax, yet the 5% miscellaneous offshore penalty would require paying about US$325,000, a large portion of a family inheritance, for an inadvertent mistake about very complex rules. That US$325,000 is not contemplated under Title 26. There is no clear legal basis for requiring a good-faith taxpayer to hand over part of their principal to the government for an honest misunderstanding.
What are the choices if you do not enter the streamlined program?
A taxpayer in Pierre’s position faces two hard choices. The first is to comply under Title 26 by filing amended returns, and risk that the IRS and Justice Department pursue multiple-year 50% willfulness penalties by arguing he was “willfully blind,” as in the Zwerner case, even though the penalty for failing to file IRS Form 8938 is generally limited to 3 years at $10,000 per year. The second is to be forced into the streamlined procedure and pay a large portion of his European family inheritance to the US, simply because he did not file IRS Form 8938 or FBARs. Both paths carry real risk.
Read the full analysis here.
Is There a Statute of Limitations on FBAR Penalties?
FBAR Statute of Limitations: How Long the Government Has to Act Against Filers Living Abroad
On this page:
Read the full analysis here.
What is the FBAR, and what law requires it?
The FBAR (the Foreign Bank Account Report) comes from a different law than the federal income tax. The income tax sits in Title 26 of the U.S. Code. The FBAR comes from the Bank Secrecy Act, which is Title 31. These two laws are very different, with very different obligations and rights. One of the important differences is the time frame in which the government can assess penalties for not complying.
Who has to file an FBAR?
By its expansive terms, which some would call extraterritorial, the FBAR law applies to U.S. citizens residing outside the U.S. It also applies to most LPRs (lawful permanent residents, or green card holders) residing outside the U.S. Many of these people are unaware the rules reach them.
What is a statute of limitations for these penalties?
A statute of limitations is the time frame in which the government has to assess penalties for not complying with the law. For foreign accounts, these time periods are not the same under Title 31 (the Bank Secrecy Act) as they are under Title 26 (the income tax law). The gap between the two is what makes this area confusing.
Is there a time limit for the IRS to assess income tax if a return was never filed?
No. When a U.S. citizen or LPR residing overseas fails to file an income tax return, the time period for the IRS to make tax assessments never lapses. There is effectively no statute of limitations against the IRS in that situation. The clock to assess does not start until a return is filed.
How long does the government have to assess civil FBAR penalties?
Title 31, the Bank Secrecy Act, is different. It does have a time period that runs against the U.S. federal government, even if the FBAR was never filed. For civil assessments of penalties, that time period is 6 years.
Can someone be criminally liable for not filing an FBAR?
Yes. A U.S. citizen or LPR living overseas could become criminally liable for willfully not filing the FBAR form. Criminal liability carries different legal consequences than a civil penalty. The key word is willfully, which separates a criminal matter from a civil one.
How is the FBAR filed now?
All FBARs must now be filed electronically. The form is not filed with the IRS. It is filed with FinCEN (the Financial Crimes Enforcement Network), on Form 114, Report of Foreign Bank and Financial Accounts, through the BSA E-Filing System website. The electronic Form 114 supersedes TD F 90-22.1, the paper FBAR form used in prior years.
Can the U.S. collect FBAR penalties in the filer’s home country?
Not always. The laws of many countries outside the U.S. often conclude that enforcing these FBAR penalties against a U.S. citizen, inside that person’s home country, violates the laws of that country. Canada is one example. Calgary based tax attorney Roy Berg has written on the question of whether the IRS can collect FBAR penalties under the Canada-US Treaty.
Is there a statute of limitations for criminal FBAR charges?
Yes, there are also statutes of limitations for criminal charges the government brings for FBAR violations. The law gets much more complex here, especially when the taxpayer is residing outside the U.S. In that situation, the time period can be tolled or suspended in favor of the government, which extends the window to bring charges. Jack Townsend has written on the statutes of limitations for FBAR noncompliance related to tax noncompliance.
Read the full analysis here.
What Is the Difference Between Willful and Non-Willful FBAR Violations?
Table of contents
Read the full analysis here.
What do “willful” and “non-willful” mean for US citizens and green-card holders living abroad who have not filed?
“Willful” and “non-willful” describe how a failure to file is characterized. For any US citizen (USC) or lawful permanent resident (LPR, a green-card holder) living outside the US who has not been filing US income tax returns or FBARs (the Foreign Bank Account Report), the willfulness question is one of the most important to understand. The IRS “streamlined” procedure requires a taxpayer to certify that the conduct was non-willful. The distinction shapes the options a person has for correcting past filings.
Why does the willful or non-willful question matter for a US citizen or green-card holder overseas?
The willful or non-willful question matters because it shapes what steps a US citizen or green-card holder living abroad needs to take about filing US income tax returns. The answer affects how a person who has not been filing may approach cleaning up past returns and FBAR filings.
Can a green-card holder living in a tax-treaty country clean up past US tax filings?
A green-card holder who lives predominantly in a country that has a US income tax treaty may be in the best position to clean up past US tax filings and return positions. The US has 68 income tax treaties. Under the “tie-breaker provisions” of such a treaty, typically Article 4, the person’s facts may allow them to file as a non-resident, and those filings may apply to several prior years.
When is a green-card holder no longer treated as a lawful permanent resident for US tax purposes?
A green-card holder is no longer treated as a lawful permanent resident for US federal tax purposes under IRC Section 7701(b)(6) when three tests are met:
- the individual is treated as a resident of a foreign country under the provisions of a tax treaty;
- the individual does not waive the benefits of the treaty; and
- the individual notifies the Secretary of the commencement of such treatment.
When a green-card holder notifies the IRS that he or she is not a US resident under an applicable income tax treaty and files the treaty position accordingly, the issue of “expatriation” becomes front and center.
Can a green card be given up for tax purposes just by moving outside the US?
In some cases, yes. Since the 2008 tax law changes, lawful permanent resident status can be abandoned for tax purposes by merely leaving and moving outside the US.
Does giving up long-term green-card status trigger the US exit tax?
Giving up green-card status can trigger the US “exit tax” for a green-card holder treated as a “long-term resident.” A green-card holder who has held that status for 8 years or more is generally treated as a long-term resident and may be subject to the exit tax of IRC Sections 877 and 877A. A separate tax may also apply to future US persons who receive gifts or inheritances from such a former green-card holder under Section 2801.
What does the IRS streamlined procedure require taxpayers to certify?
The IRS “streamlined” procedure, announced on June 18, 2014, has specific requirements that obligate the taxpayer to certify “non-willful” behavior. That certification is made under penalty of perjury. Where a green-card holder’s past failure to file US income tax returns was not non-willful, difficult legal questions arise about the consequences.
Read the full analysis here.
What Tax Forms Do US Citizens and Green Card Holders Living Abroad Need?
Living outside the United States does not eliminate your US tax obligations. US citizens and green card holders abroad must file a US tax return every year and may also need to file additional reports on foreign assets and accounts. Here is an overview of the key forms, what they cover, and how they interact.
Table of contents:
Foreign Earned Income Exclusion (FEIE)
Foreign Tax Credits (FTC)
Information Reporting and FBAR
Tax Preparation Software
Foreign Earned Income Exclusion (FEIE)
Is my foreign income automatically exempt from US reporting?
No. A common misconception is that foreign income is exempt because it can be excluded. Foreign earned income is not exempt. You must report it on a US tax return, and you must be a qualifying individual to elect the exclusion.
What types of income qualify for the exclusion on Form 2555?
The exclusion is available only for “earned” income. It cannot be used for passive investment income such as dividends, interest, or capital gains.
Foreign Tax Credits (FTC)
How does a Foreign Tax Credit work?
A Foreign Tax Credit provides a dollar-for-dollar reduction, subject to limitations, of your US federal tax burden for income taxes you paid to another country on income sourced there. It is claimed on Form 1116.
Can I claim both the FEIE and the Foreign Tax Credit?
No. Once you choose to exclude foreign earned income or housing costs, you cannot take a foreign tax credit on that same income. If you do take the credit, your previous choice to exclude that income may be treated as revoked.
Are there different forms for lawful permanent residents (LPRs)?
US citizens and LPRs generally use Form 1040. However, LPRs residing in a country with a US income tax treaty may be eligible to file Form 1040NR as a non-resident.
What is Form 8938?
Form 8938 (Statement of Specified Foreign Financial Assets) is used to report specified foreign financial assets. It often overlaps with FBAR reporting and must be attached to your annual income tax return when filed with the IRS.
Who must file an FBAR (Form 114)?
US citizens and LPRs with a financial interest in or signature authority over foreign accounts must file a Foreign Bank Account Report (FBAR). The definitions of “ownership interest” and “signature authority” are interpreted very broadly under the regulations.
Where is the FBAR filed?
Unlike other tax forms, the FBAR is not filed with the IRS. You must file it electronically with FinCEN (the Financial Crimes Enforcement Network) through the BSA E-Filing System on Form 114.
What are the penalties for FBAR non-compliance?
The statutory penalty for failing to file, or filing late, is $10,000 per failure. If the failure to file was intentional, the penalty can increase to 50% of the account balances.
There are important unintended tax consequences that can befall individuals who have a green card depending upon their factual circumstances: see, Oops…Did I “Expatriate” and Never Know It: Lawful Permanent Residents Beware! International Tax Journal, CCH Wolters Kluwer, Jan.-Feb. 2014, Vol. 40 Issue 1, p9).
Tax Preparation Software
Can I use standard tax software for these international forms?
Often, no. Most tax preparation software does not support Form 8938 or other forms related to non-US assets. These forms frequently require manual completion using an Adobe Acrobat version of the form.
Read the full analysis here.
Understanding Your FBAR Obligations: A Guide for U.S. Citizens and Residents Abroad
If you are a U.S. citizen or a Green Card holder living overseas, you may have heard of the “FBAR.” While it sounds like a complex tax term, it is actually a financial reporting requirement that follows you no matter where you live in the world.
Here is a breakdown of what you need to know to stay compliant, explained in plain English but with a focus on the legal details.
Table of contents:
What is the FBAR?
Who has to file?
What accounts are covered?
Is the FBAR the same as Form 8938?
The reality of FBAR penalties
How to file
What is the FBAR?
The FBAR stands for the Report of Foreign Bank and Financial Accounts. Its official name is FinCEN Form 114.
Legally, this is not an income tax requirement. It is a mandatory report required under Title 31, Section 5314 of the U.S. Code. Because it falls under “Money and Finance” laws rather than the Internal Revenue Code, you do not file it with the IRS. Instead, you file it with FinCEN (the Financial Crimes Enforcement Network), a separate branch of the Treasury Department.
Who has to file?
The requirement applies to all U.S. Citizens (USCs) and Lawful Permanent Residents (LPRs), regardless of their physical location.
Global Reach: If you are a U.S. citizen living in France, you are required to report your French bank accounts, as well as any other accounts you might hold in places like London or Geneva.
Green Card Holders: Similarly, a Green Card holder living in Sao Paulo, Brazil, must report their Brazilian accounts and any accounts held in other countries, such as Uruguay.
Defining “Resident”: Interestingly, the law for FBARs uses the tax code’s definition (Internal Revenue Code Section 7701(b)) to determine who counts as a “resident,” even though the FBAR itself is not a tax form.
Note: While many resources mention a $10,000 threshold for filing, this specific dollar amount is not mentioned in the legal excerpts provided here; you should verify current filing thresholds independently.
What accounts are covered?
The law is broad and covers bank and financial accounts located outside of the United States. This includes accounts in your country of residence and any other foreign country. Currently, all FBARs must be submitted using the electronic Form 114, which replaced the old paper form known as TD F 90-22.1.
No, though they are often confused because they involve duplicate reporting.
FBAR (Form 114): A financial report filed with FinCEN under Title 31.
Form 8938: A tax information return filed directly with your IRS tax return under Title 26.
A major legal distinction lies in the statute of limitations. The FBAR has a time limit after which the government can no longer assess penalties, even if you never filed the form. In contrast, if you fail to file Form 8938, there is no time limit for the IRS to come back and assess income taxes and penalties for that year.
The reality of FBAR penalties
The penalties for failing to file an FBAR are often discussed as being severe, but the law provides some unique protections.
Penalties are Elective: The law states the Secretary of the Treasury “may” (not “shall”) impose a penalty. This means the government has the discretion to decide whether or not to penalize a violation; it is not mandatory.
Limited Collection Powers: Unlike a standard tax debt, the government cannot simply place a tax lien or levy on your property to collect an FBAR penalty. Instead, the government typically must sue you in a judicial court action to enforce the penalty.
Expiration Dates: Because there is a statute of limitations, the government’s window to act is limited. For example, if a U.S. citizen missed a filing for the year 2006, the time for the government to assess a penalty has already lapsed.
How to file
Gone are the days of mailing paper forms. All FBARs must now be filed electronically through the BSA E-Filing System website.
Staying compliant is obligatory, but understanding these nuances can help you navigate the process with more confidence. If you have accounts abroad, ensuring your electronic Form 114 is submitted correctly is the best way to avoid the complications of a potential government investigation.
This post provides general information only and is not legal advice. Consult an experienced attorney for guidance specific to your situation.
Read the full analysis here.
Form W-8 or W-9? Why the Wrong Choice Could Cost Green Card Holders Abroad
The choice between Form W-8 and Form W-9 comes down to one thing: your U.S. tax residency status, not your immigration status. Green card holders living abroad may be able to sign Form W-8 under a U.S. income tax treaty, but picking the wrong form means signing a false statement under penalty of perjury. And claiming treaty benefits carries a risk that many people never see coming. Consulting an experienced attorney before signing anything is essential.
Table of contents:
Both forms tell your bank or financial institution whether you are a U.S. tax resident or not. Form W-9 is for U.S. residents, who must pay U.S. taxes on income they earn anywhere in the world. Form W-8BEN is for non-residents, who generally only pay U.S. taxes on certain types of income that come from U.S. sources. The form you sign has real legal consequences, not just administrative ones.
Signing either form is a certification made under penalties of perjury. If you are a U.S. tax resident and you sign Form W-8, you are making a false statement, and serious legal consequences may follow.
Why is this more complicated for green card holders living abroad?
U.S. citizens always sign Form W-9, with no exceptions. For everyone else, it depends on tax residency status. Green card holders are generally treated as U.S. tax residents even while living in another country, which would normally mean they sign Form W-9. But there is an important exception: if the country where they live has an income tax treaty with the United States, they may be able to claim non-resident status under that treaty and sign Form W-8 instead. There are important unintended tax consequences that can befall individuals here: see, Oops…Did I “Expatriate” and Never Know It: Lawful Permanent Residents Beware! International Tax Journal, CCH Wolters Kluwer, Jan.-Feb. 2014, Vol. 40 Issue 1, p9).
The United States has 58 income tax treaties that together cover 66 countries. That includes the 1973 U.S. and U.S.S.R. income tax treaty, which still applies today to nine former Soviet republics: Armenia, Azerbaijan, Belarus, Georgia, Kyrgyzstan, Moldova, Tajikistan, Turkmenistan, and Uzbekistan.
What did the court decide in Aroeste v. United States, and why does it matter?
Aroeste v. United States (Case No. 22-cv-00682-AJB-KSC) is a federal court decision that established a 5-step analysis for green card holders who have not formally given up their green card but are living abroad. The key question the court addresses is whether a green card holder qualifies to be treated as a resident of a foreign country under an applicable U.S. income tax treaty. This ruling matters for the more than 3 million LPRs who are living outside the United States.
(Patrick W. Martin of Chamberlain Hrdlicka served as lead counsel for the taxpayer in this case. Read his full analysis of Aroeste v. United States here.)
What are the benefits of successfully claiming non-resident status under a treaty?
If a green card holder qualifies as a non-resident under a tax treaty, they may be able to stop filing U.S. federal income tax returns on their worldwide income. They may also no longer be required to file the Foreign Bank Account Report, known as the FBAR, which would help them avoid the significant penalties that come with missing that filing. The court in Aroeste laid out the specific steps required to make this claim correctly.
One important note: if you claim non-resident status under a treaty but fail to report that treaty position to the IRS on time, you face a separate penalty under IRC Section 6712(a) of $1,000 for each failure to timely file. Claiming treaty status correctly and reporting it on time are both required.
What is the risk on the other side?
Claiming treaty-based non-resident status may also legally end your U.S. tax residency. Under IRC Section 7701(b)(6), this shift may cause you to cease to be a lawful permanent resident of the United States. That change may trigger the U.S. expatriation tax rules under IRC Section 877A(g)(3), which could classify you as a covered expatriate. The Aroeste court did not address these consequences because they were not part of that case, but they are real and potentially serious.
What does covered expatriate status mean for your family?
Covered expatriate status does not only affect you. If your family members or friends in the United States later receive gifts or an inheritance from you, they may owe U.S. tax on those transfers under the covered gift and covered bequest rules. This may affect children, spouses, and anyone else who would receive something from you.
Do you need an attorney before making this decision?
The answer depends on which country you live in, which treaty applies, the value of your assets, and your long-term plans. Getting it wrong may trigger exit taxes, affect your family’s inheritance, and have consequences that cannot easily be undone. This post explains the framework but is not a substitute for legal advice specific to your situation.
If you are an attorney, read this post instead.