The U.S. tax and foreign bank account reporting laws regarding foreign assets are burdensome and complex. Sometimes, only hiring expensive and competent U.S. international tax advisers can help USCs and LPRs residing overseas avoid these penalties. Even that is not always a guaranty that foot-faults of the law will not occur.
Indeed, the IRS is eventually expecting to implement automatic $10,000 penalties for individuals who fail to file timely IRS Form 5471. They already do issue automatic $10,000 penalties for corporations who neglect to timely file such forms.
FATCA and its application this year will only intensify these issues.
Only Congress along with the President can modify the law. The IRS nor the Justice Department can modify it.
The law as it currently reads, in my opinion (after some 22+ years of U.S. international tax practice) is almost always highly over-burdensome for the “ordinary” individual USC/LPR living outside the U.S. Without a modification of the law, its enforcement is left in the hands of the IRS and Tax Division of the Justice Department. Those who advise taxpayers vis-a-vis these government officials see in practice the disparate treatment that can befall various individuals, depending upon the approach taken by the particular government official.
Importantly, as the law has grown so complex over the years and expansive, it is not a fair or reasonable burden to expect the IRS can even administer it effectively and consistently. FATCA and its implementation this year, will only increase this complexity and inability to administer the law consistently and fairly.
Hopefully, Congress will take serious (which they have not to date) the plight of these individuals. The author has made a serious proposal on the topic, that was submitted to the U.S. Treasury, Joint Committee of Taxation and Senate Finance Committee:
U.S. Citizenship Based Taxation – Proposals for Reform
FBAR Penalties for USCs and LPRs Residing Overseas – Can the Taxpayer have no knowledge of the law and still be liable for the willfulness penalty? See government memorandum.
FBAR Penalties for USCs and LPRs Residing Overseas.
Can the Taxpayer have no knowledge of the law and still be liable for the willfulness penalty? The government says yes, in its memorandum of law filed in the Zwerner case.
The importance of the Zwerner case to USCs and LPRs living overseas, cannot be overestimated in my view. It’s a case where the USC, Mr. Zwerner, was cooperative with the IRS during their examination. This is a fact that both the government and the taxpayer acknowledged during the trial to enforce the collection and determination of the government of the 200% FBAR penalties.
Most troubling about this case, is the allegation that the IRS agent handling the case caused Mr. Zwerner to file and prepare a letter that expressly was an admission of his liability under Title 31. As part of the “undisputed facts”, the IRS agent actually drafted the letter for Mr. Zwerner. See the Motion of Mr. Zwerner in reply to the government’s Motion for Summary Judgment. In that case, Mr. Zwerner testified that the IRS agent had misled him.
Presumably, this letter would have been highly convincing evidence to the jury who heard the FBAR penalty case.
There is a cautionary tale in this case for USCs and LPRs residing overseas who have not filed FBARs. Communications to the government, how they are managed, what is said and what approach is taken, should be carefully considered in each case.
Next, another perplexing aspect of this case is that the government continues to persist in its argument that a mere preponderance of the evidence is the proof standard required. That will be left for another post and another discussion.
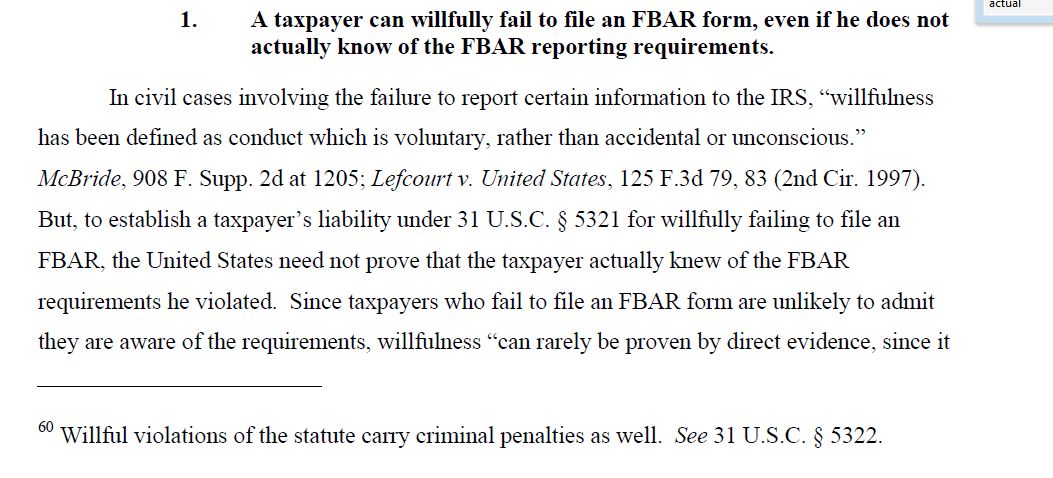
Finally, maybe the most troubling for USCs and LPRs who live outside the U.S., is the government’s assertion that an individual can be liable for the willfulness penalty, for “willfully failing to file a FBAR” – ” . . . even if the person does not actually know of the FBAR reporting requirements.” See, page 4 of the government’s motion for Summary Judgment in the Zwerner case. This is a position they have argued consistently in at least three different cases.
This leaves USCs and LPRs living overseas wondering, will the U.S. government assess willfulness penalties against me for having income and accounts in my home country during all of the years I have lived in “Country X” (particularly since I may have had no knowledge of the FBAR reporting requirements)? Under what circumstances am I at risk for such a claim by the government?
Another later post will explain how the government can collect the FBAR assessed penalties under the law and the problematic issues for them in collecting the amounts in a foreign country.
Mr. Zwerner did not disclose his account for many decades and had both untaxed and pre-taxed income in that account. He kept this Swiss account secret from the government and even his own lawyer of 40 years. He only had told his wife. He also answered “no” to his CPA regarding having any foreign accounts. These were all bad facts for him in his case.
He always lived in the U.S., born and raised, but also had international business operations from the glass industry in which he was a leader.
The apparent success of the government, raises the question of whether such “success” at trial will backfire with how USCs and LPRs residing overseas will handle their U.S. tax and FBAR affairs. How will USCs and LPRs residing overseas respond and understand the impact of the Zwerner decision?
Will it be a significant victory (or a Pyrrhic Victory), considering the impact it may have on USCs and LPRs residing overseas?
First, the taxpayer did come forward and disclose the unreported foreign accounts, and received a letter from the IRS CI issued a letter on February 17, 2009, stating that ” . . . based upon the information provided a criminal investigation will not be initiated at this time. . . ” Nevertheless, the government pursued 50% civil willfulness penalty assessments for multiple years (4 years). The Tax Division of the Justice Department pursued this case through trial, incurring the time and costs of government resources, arguing Mr. Zwerner owed a total of $3,630,119.29 (on an account with a maximum value during the years at issue of apparently no more than US$1.69M) in their Motion for Summary Judgement.
See Paragraph 57 of the government’s Motion for Summary Judgement:
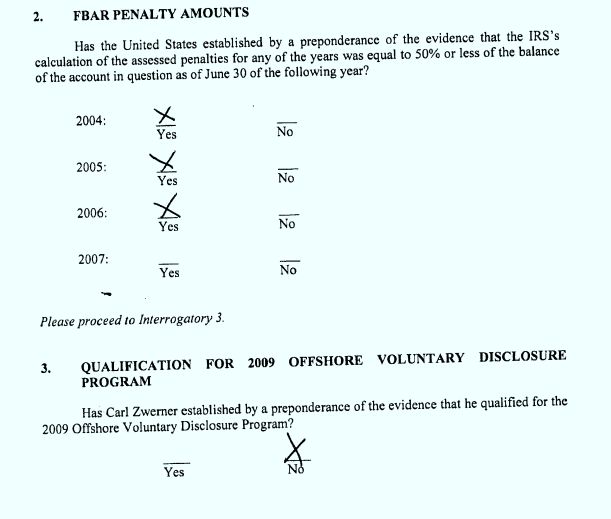
The jury verdict found that based upon a “preponderance” of the evidence, the taxpayer did not qualify for the 2009 offshore voluntary disclosure program. Importantly, this OVD program was not announced until after Mr. Zwerner had taken steps to disclose and report his foreign accounts under a specific letter his lawyer had received by IRS CI. It appears that Mr. Zwerner was following the rules of the program that existed at the time he came forward.
Second, why was Mr. Zwerner not criminally prosecuted for tax evasion? Was it because he had a letter from the IRS CI that they would not criminally prosecute him? Was it because the government wanted to assess multiple FBAR penalties, in lieu of a criminal prosecution against an 87 year old man? Did the government want to demonstrate they would extract more financial pain from a civil action, prosecuted under a “preponderance of the evidence” standard, instead of a criminal action that would be harder to convict under a “beyond a reasonable doubt” standard?
Third, why has the government insisted on pursuing a civil penalty that was more than the entire asset value of the account(s)? Is the government’s view that the more onerous the penalties, the greater likelihood of compliance for others with unreported accounts? Is there an incentive on the part of the government to collect large FBAR penalties and forgo the costs and time of a criminal case, potential sentencing and prison time?
Fourth, why did the government reach a settlement with Mr. Zwerner, just days after what was apparently a huge victory for the government? Does the government think these FBAR penalties will be overturned or found to be unconstitutional by an Appeals Court? This is probably the most interesting legal question, because if the law is ultimately found to be unconstitutional, it would change the dynamic and approach of taxpayers and the government.
Fifth, will the government pursue a similar strategy (e.g., multiple year 50% willfulness penalties) against USCs and LPRs who reside outside the U.S.? Will this be their approach instead of considering any type of criminal prosecution to extract more financial pain from a civil action, prosecuted under a “preponderance of the evidence” standard, instead of a criminal action that would be harder to convict under a “beyond a reasonable doubt” standard?
Sixth, will the government not pursue USCs and LPRs living overseas who do not report their accounts? Will they selectively enforce the law (e.g., treating U.S. resident individuals different from non-U.S. resident USCs and LPRs)?
Unfortunately, the message for many USCs and LPRs residing overseas who have not filed U.S. income tax returns or FBARs for many years or for many decades, is a very mixed message. If the government will pursue a 200% FBAR penalty against an 87-year-old man, who was a philanthropic leader and ultimately fully disclosed his account through what he believed as the OVD program that existed at the time he participated; why will they not similarly pursue such FBAR penalties against USCs and LPRs living outside the U.S.?
For these reasons, the Zwerner decision may well be a Pyrrhic Victory for the government, IF USCs and LPRs overseas consider such an approach excessive and unreasonable, to the point, they feel more comfortable in receding into the shadows and not filing FBARs. Hopefully, this will not be the effect and end result; but again, it appears the focus of the government has neglected to consider the unique circumstances of millions of USCs and LPRs residing outside the U.S.
Zwerner is yet another important chapter of a multi-prong approach of the U.S. government in identifying assets located outside the U.S.
The question remains: “What will be the takeaway to the ordinary USC and LPR population residing overseas?” Will they think that by filing FBARs, they will simply run the risk of the government assessing multiple year 50% willfulness penalties? Will they feel even greater fear of trying to come into compliance under the U.S. tax and FBAR laws – and try to comply at all costs? Or instead, will they take steps to stay in the shadows and not report (a Pyrrhic Victory for the government)?
Why the Zwerner FBAR Case is Probably a Pyrrhic Victory for the Government – for USCs and LPRs Living Outside the U.S. (Part I)
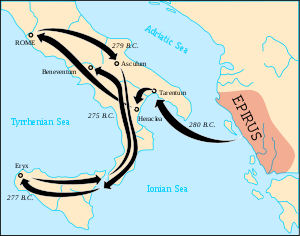
King Pyrrhus of Epirus, sustained staggering losses in defeating the Romans in Southern Italy in the years 280-275BC; so says the origin of the phrase “Pyrrhic Victory”.
The government was on its face, very “successful” in the Zwerner case in convincing a jury they should render a verdict for 3 years of FBAR 50% willfulness penalties (150% of the account balance in total). The government tried to assert 4 years of willfulness penalties, which would have been 200% of the account balance; all under a civil penalty provision in the statute, that looks like a criminal penalty on its face and via its outcome.
The key facts of Zwerner are these:
He was 87 years old when the FBAR civil claims were litigated;
He was living in the U.S. and had studied at Robinson College of Business at George State University – and was a major philanthropist to GSU, where he pledged $5M to build a Business and Law Complex Auditorium in 2007 and previously funded the Carl R. Zwerner Chair in Family Owned Business;
He had apparently had a Swiss bank account opened in the 1960s (prior to the adoption of the BSA law that created FBAR reporting – which was passed in 1970), that he had not reported on his U.S. income tax return;
The accounts were in the names of two different foundations Mr. Zwerner created;
He had hired legal counsel to assist him with professional advice prior to the IRS publishing their initial “offshore voluntary disclosure” program/initiative;
He apparently filled out the tax organized provided by his accountant, every year, and answered “no” to questions about having an interest in foreign financial accounts;
His legal counsel had apparently contacted the IRS Criminal Investigation Division (“CI”) about his voluntary disclosure on February 10, 2009, without providing his name;
The CI then issued a letter on February 17, 2009, stating that ” . . . based upon the information provided a criminal investigation will not be initiated at this time. . . ” (see letter from IRS with this date reflected as Exhibit 4 in the ) – ;
The IRS did not announce the first offshore voluntary disclosure program until afterwards on March 26, 2009; and
Mr. Zwerner then filed amended tax returns for the years 2004, 2005 and 2006 along with late filed FBARs.
A highly regarded criminal tax law firm in Beverly Hills, California, Hochman, Salkin et al, provided the following conclusion in their analysis of the Zwerner case:
This is a significant win for the government in their efforts to encourage certain US persons having undisclosed interests in foreign financial accounts to come into compliance with the applicable filing and reporting requirements . . .
Along the same lines, the Department of Justice issued a press release on May 28, 2014, with the following highlights:
JURY FINDS MIAMI MAN OWES CIVIL PENALTIES FOR FAILING TO REPORT SWISS BANK ACCOUNT
WASHINGTON – Today, a jury in Miami found Carl R. Zwerner responsible for civil penalties for willfully failing to file required Reports of Foreign Bank and Financial Accounts (FBARs) for tax years 2004 through 2006 with respect to a secret Swiss bank account he controlled. According to evidence introduced at trial, the balance of the bank account during each of the years at issue exceeded $1.4 million, and the jury found Zwerner should be liable for penalties for 2004 through 2006. Zwerner faces a maximum 50 percent penalty of the balance in his unreported bank account for each of the three years . . .
“As this jury verdict shows, the cost of not coming forward and fully disclosing a secret offshore bank account to the IRS can be quite high,” said Assistant Attorney General Kathryn Keneally for the Justice Department’s Tax Division. “Those who still think they can hide their assets offshore need to rethink their strategy.” . . .
The evidence at trial showed that Zwerner opened an account in Switzerland in the 1960s, which he maintained in the name of two different foundations he created. Zwerner was able to use the proceeds of the account whenever he wanted and used it for personal expenses, including European vacations . . .
Herein lies some key inconsistencies in the approach of the government. Will it be a significant victory, considering the impact it may have on USCs and LPRs residing overseas?
What will be the affect to USCs and LPRs residing overseas? A follow-up post will discuss.
IRS Commissioner’s Comments – Is He Listening to USCs and LPRs Living Around the World!?
The IRS Commissioner’s comments earlier this week may signal an important change in policy and approach to USCs and LPRs residing overseas? See, his full remarks set out in the paper presented at the OECD international tax conference:
– OECD – INTERNATIONAL TAX CONFERENCE WASHINGTON, D.C., JUNE 3, 2014
***
This tax-expatriation.com website is largely dedicated to USCs and LPRs who reside outside the U.S. Those who are not living in the U.S.
In some of the more extreme cases, these USCs and LPRs are (i) renouncing (or proving prior relinquishment) of their U.S. citizenship, or (ii) formally abandoning their LPR or terminating the status by application of the tax law, respectively. See, The List is Out – and Its 1,001 Former U.S. Citizens for the 1st Quarter 2014
There are a multitude of reasons for taking this step, but a common theme for many individuals (especially with limited financial resources) arises from (1) the costs in time and resources – e.g., time required to collect financial information from banks in their country of residence, which cannot easily be converted for U.S. tax law purposes – professional fees to U.S. tax advisers for filing annual tax returns and information returns such as FBARs, and (2) the very high penalties assessed under the law for not filing such forms and information. See, USCs and LPRs Living Outside the U.S. – Key Tax and BSA Forms.
All of these complications for USCs and LPRs living outside the U.S., is a most compelling reason for the IRS Commissioner to provide a more sensible approach to how the government focuses their attention on USCs and LPRs residing overseas. How will they be treated?
How will the long-arm of the U.S. law that extends around the world be administered by IRS revenue agents?
Will the new policy announcements, which are apparently forthcoming, provide a genuine balance of allowing the IRS to enforce the law in a balanced and fair-minded approach with USCs and LPRs residing overseas? Will there be a clear distinction between those who are in good faith attempting to comply with the law (even if they have made numerous “technical foot faults” in how the law applies) versus those USCs and LPRs who have taken steps to hide assets and evade U.S. taxes?
It seems that only a fair-minded approach by the IRS and the Justice Department, will lead to better U.S. tax and FBAR compliance worldwide of USCs and LPRs residing overseas. This should be true, even in light of the vast treasure trove of FATCA foreign financial data which the IRS will begin collecting throughout the world for this calendar year 2014. See, The Importance of a Certificate of Loss of Nationality (“CLN”) and FATCA – Foreign Account Tax Compliance Act.
One common notion, is that if a USC or long-term LPR has not filed foreign bank account reports (“FBARs”) pursuant to Title 31, they will not be able to make the certification as required by the statute – Section 877(a)(2)(C), which causes an individual to be a “covered expatriate” if:
(C) such individual fails to certify under penalty of perjury that he has met the requirements of this title for the 5 preceding taxable years or fails to submit such evidence of such compliance as the Secretary may require.
Importantly, the statutory reference to “this title” is a reference only to “Title 26, Internal Revenue Code,” i.e. the federal tax laws. It is not a reference to any other “Title” of the federal laws. The federal statutory laws are organized by “Titles“; e.g., Title 8 is “Aliens and Nationality” (i.e., immigration law) and Title 7 is “Agriculture”, etc.
Specifically, Section 877(a)(2)(C) of the tax law, does not also require the individual to be able to certify his or her compliance with any other title for the preceding 5 years, such as Title 31 Money and Finance: Treasury.
Title 31 is the law that creates the FBAR filing requirements and is known as the “Money and Finance: Treasury.”
To put this into a concrete example, assume a USC living in Canada has filed complete and accurate U.S. federal income tax returns for the years 2008 through 2013; but never filed any FBARs regarding the Canadian corporate accounts over which the individual has had signature authority. Maybe this individual’s Canadian accounts also exceeded US$10,000 in at some point through the year? Nevertheless, if he or she renounces their U.S. citizenship in 2014, they should nevertheless, be able to avoid “covered expatriate” status by complying with Section 877(a)(2)(C), even though they failed to comply with Title 31 requirements.
How is the offshore voluntary disclosure program really working? Not well for USCs and LPRs living overseas.
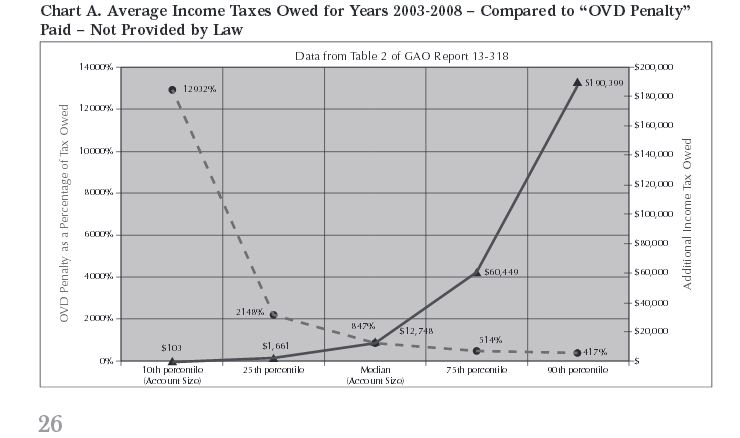
The authors have taken the taxpayer information that was finally made, at least partially public, via the following GAO report, to identify the amount of actual estimated taxes collected: Offshore Tax Evasion: IRS Has Collected Billions of Dollars, but May be Missing Continued Evasion (GAO-13-318): March 2013, (referred to as “GAO Report”). Table 3 provides that the total “offshore penalty” collected was $2.81 Billion and “total collected” out of a total US$4.4 Billion collected. Accordingly, the “offshore penalty” represented 64% of all sums collected under the program out of the 10,543 taxpayers analyzed.
Fortunately, some revenue agents handling OVD cases in the IRS are now getting a better understanding that USCs and LPRs who live outside the U.S., are typically in a very different category than U.S. resident taxpayers who have taken steps to hide their foreign assets. Many of these individuals should be opting out of the OVD program, depending upon the facts of their case.
This report was highlighted earlier in the year in Jack Townsend’s blog as follows:
In a comment, a reader directed me and other readers to a recent article that is quite good, so I decided to elevate the article to a separate blog entry. The article is Patrick W.Martin & Michelle Ferreira, The 2013 GAO Report of the IRS Offshore Voluntary Disclosure Program (1/10/14). The web version is here, and the pdf is here. The authors’ bios are here and here.
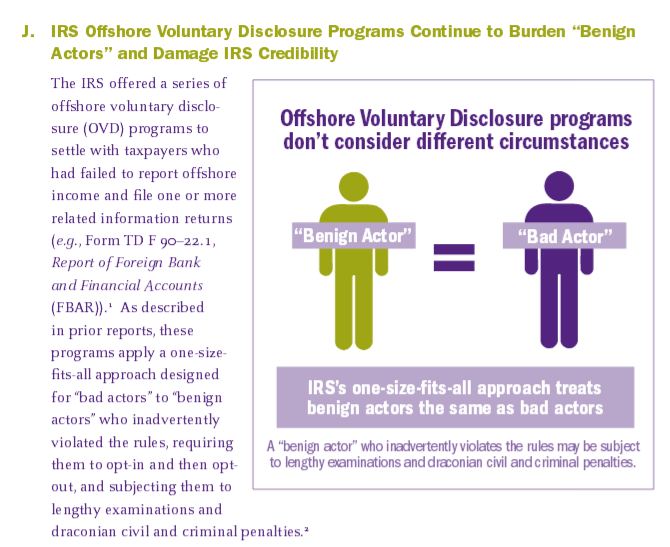
As the authors note, “the GAO Report indicates [that] taxpayers with little or no criminal or civil fraud exposure were punished proportionately in higher amounts than those who participated and had true criminal tax exposure.” The authors break these categories into Bad Actors and other actors, referred to as Benign Actors. That Bad Actors would be treated better than Benign Actors is a counter-intuitive result.”
“One key question that the GAO Report raises is why would so many taxpayers enter into the Offshore Voluntary Disclosure Program if they were not at least as liable for income taxes or penalties under the law? The authors think the answer to this question can be simply answered. Neither taxpayers nor many of their tax advisers understand how tax penalties actually apply under the law, particularly because some penalties are not in the Internal Revenue Code. Instead of understanding what the requirements are under the law, taxpayers simply relied upon the IRS to inadequately explain how penalties could apply in and outside of the program. Based upon only the Frequently Asked Questions (which were published subsequent to the program’s announcement), taxpayers and their advisers had to make swift and uneducated determinations as to whether a taxpayer should participate in the Offshore Program at all and many feared all would be criminally prosecuted, as the IRS continuously led them to believe.”
This is occurring while the Senate investigations of undisclosed foreign accounts has now started to focus on USCs living overseas.
A large portion of the Senate committee report is dedicated to U.S. citizens who live outside the U.S. and are not compliant with U.S. tax laws. The . . . chart from the report highlights this focus as to the approximately 6,000 U.S. citizen accounts at Credit Suisse who were/do not live in the U.S:
?????????????????Please click here to view the above in Chinese.?
This announcement is now talked about among many tax return preparers as if it creates some sort of special rights or benefits to a particular type of U.S. citizen residing overseas. The IRS announcement is neither the law, nor purports to be the law. It also does not modify the statute of limitations period or otherwise bar the IRS from commencing an audit against a USC residing overseas who has never filed U.S. income tax returns. See, When the U.S. Tax Law has no Statute of Limitations against the IRS; i.e., for the U.S. citizen and LPR residing outside the U.S. (Posted on March 24, 2014)
The “new filing compliance procedures” is simply a statement of what has always been the practice of the IRS. U.S. income tax returns that are filed are examined under whatever procedure the IRS chooses as part of its audit and review practices. Income tax returns with modest assets, modest income or little to no U.S. income tax liability garner less attention and resources of the IRS than those with lots of assets, lots of income, etc. See, IRS summary of IRS audits.
Some of the key concepts in the 2012 announcement are set out below:
Compliance risk determination:
The IRS will determine the level of compliance risk presented by the submission based on certain information provided on the returns filed, and based on certain additional information that will be required as part of the submission. Low risk will be predicated on simple returns with little or no U.S. tax due. Absent high risk factors, if the submitted returns and application show less than $1,500 in tax due in each of the years, they will be treated as low risk. In general, the risk level will rise as the income and assets of the taxpayer rise, if there are indications of sophisticated tax planning or avoidance, or if there is material economic activity in the United States.
* * *
How taxpayers will be able to take advantage of the new procedure:
Taxpayers wishing to use the new procedure will be required to submit: (1) delinquent tax returns, with appropriate related information returns, for the past three years, (2) delinquent FBARs for the past six years, and (3) any additional information regarding compliance risk factors required by future instructions. Payment of any federal tax and interest due must accompany the submission. More information about the application process including where submissions should be sent, will be provided prior to the effective date.
Any taxpayer claiming reasonable cause for failure to file tax returns, information returns, or FBARs will be required to submit a dated statement, signed under penalties of perjury, explaining why there is reasonable cause for previous failures to file. See IRS Fact Sheet FS-2011-13 (December 2011) for examples of reasonable cause.
Does any of the above protect the USC residing outside the U.S. from an audit for any year a U.S. federal income tax return was not filed? The short answer is – NO!
Does any of the above statements in the IRS announcement mean that a USC residing overseas could not be subject to late payment or late filing penalties for not previously filing U.S. tax returns. The short answer is – NO!
Does any of the above statements in the IRS announcement mean that a USC residing overseas can never be subject to penalties for not filing information returns regarding their non-U.S. international assets and “specified foreign financial assets”? The short answer is – NO! See, USCs and LPRs residing outside the U.S. – and IRS Form 8938
Why then, did the IRS issue such an announcement? Was it an attempt to present a softer message than the IRS announcement in 2011 (IRS Fact Sheet FS-2011-13 – which enumerates various penalty concepts such as –2. Penalties imposed for failure to file income tax returns or to pay tax; 3. Possible additional penalties that may apply in particular cases; 6. Possible penalties for failure to file FBAR; etc.)?
This is another mixed message from the IRS, which is nothing more than how tax returns have been processed by the IRS over the decades; i.e., a taxpayer files a late tax return and it gets processed by the IRS (and the IRS may elect to audit any particular return, late filed or otherwise).
reflects the frustration of some Canadian academic leaders. The article’s tone is set with its first paragraph:
For the first time in Canadian history, our federal government is preparing to provide a foreign government with sensitive personal financial information about hundreds of thousands of Canadians. It is doing so to stave off threatened economic sanctions, and is getting nothing in return.
It seems to me the United States government is faced with a real dilemma regarding the foreign frustration with U.S. tax policy. Do they correctly enforce the law as written? Doing so, will clearly bring a host of tax penalties to be levied against dual national citizens living throughout the world. Canada and Mexico are the two countries most affected. Most of these penalties and tax assessments will, for all practical affects, be unenforceable in the international context.
Most of those dual citizens who will be affected, will be subject to a host of U.S. tax penalties, mostly related to failure to file information returns (e.g., FBARs, IRS Forms 8938, 5471, 3520, etc.) which carry a minimum of US$10,000 fine per violation. On the other hand, if the IRS and Justice Department does not enforce the tax and “FBAR” law against all U.S. citizen taxpayers, including “benign” taxpayers, what will be the response of taxpayers who are not “benign” and have actively engaged in tax evasion and tax fraud?
This is a dilemma that the very law has created for U.S. tax administrators.
**Arthur Cockfield is a Professor with Queen’s University Faculty of Law. Allison Christians is the Heward Stikeman Chair in the Law of Taxation at McGill University Faculty of Law. This article draws from their submissions on FATCA to the Department of Finance, which are posted on the Internet.