International Tax · Citizenship Renunciation · LPR Abandonment
International Tax Shareholder
Immigration Forms, I-407; I-485, Application to Register Permanent Residence or Adjust Status & Tax Forms, 1040, 1040NR, 8833, 5471, 8854, 8621, 3520, 8864, 8858 and FinCEN forms 114, etc. etc. (Part I of III)
The U.S. tax law is complex, including when an individual (i) becomes and (ii) ceases to be, a U.S. income tax resident (USITR). USITR is not a technical term used under the tax law. The U.S. tax and information reporting requirements are very different depending the status of an individual. Anyone who is not a United States citizen, is either a –
“Resident alien“, or a
“Nonresident alien” as the tax law defines both of these categories.
You can’t be both.
“Resident aliens” are generally also “United States persons” (both technical terms in the federal tax law).
“Non-resident aliens” as defined are necessarily not “United States persons.”
Being one versus the other has huge U.S. tax and reporting consequences.
An individual who is a “lawful permanent resident” as referenced in the tax law (Section 7701(b)(6)) cross-references the U.S. immigration law. The first requirement of that statutory tax rule in § 7701(b)(6)(A)) is that “(A) such individual has the status of having been lawfully accorded the privilege of residing permanently in the United States as an immigrant in accordance with the immigration laws [such status not having changed]. . .[emphasis added]” This means the tax definition is dependent upon the immigration laws, which are found in Title 8, Immigration and Nationality Act. Importantly, the last part of that sentence (i.e., [such status not having changed] is a requirement in the immigration law (Title 8), but does not appear in the tax definition.
The term “lawful permanent resident” cannot be found in Title 8 as a noun or object (i.e., the individual). Instead, the immigration law defines the status of a person in 8 U.S. Code § 1101(a) as follows:- “. . . (20) The term “lawfully admitted for permanent residence” means the status of having been lawfully accorded the privilege of residing permanently in the United States as an immigrant in accordance with the immigration laws, such status not having changed.“
This analysis is fundamental to be able to determine whether an individual who holds a “green card” in their pocket even has the status of being “lawfully admitted for permanent residence. . . such status not having changed.” It’s a fundamental legal question under immigration law that must be answered first, to then be able to answer the tax question.
Each form an individual files or does not file (e.g., IRS tax form 1040 v. 1040NR; 8833, 5471, 8854, 8621, 3520, 8864, 8858 and FinCEN forms 114; and immigration forms, e.g., I-485, I-407, etc.) can have a potential impact on the tax residency status of an individual.
The immigration law and when forms, such as Form I-485, Application to Register Permanent Residence or Adjust Status are submitted to the U.S. federal government can have an impact on this determination. The government can use it against the individual as they did unsuccessfully in Aroeste (see below – Pages 9 and 11 of 17); asserting that Mr. Aroeste waived the treaty by not submitting certain forms.
The tax residency analysis for those who have kept their “green card” in their pocket, can be even more complex as was analyzed by the Court. There are additional provisions of the law that must be considered including old Treasury Regulations that pre-date many provisions of various U.S. income tax treaties.
For instance, each of the following federal tax statutory rules, which will be considered in more detail in later posts (II and III):
Additional posts will review the impact of these provisions in the law and how various immigration forms (including I-485 and I-407, Record of Abandonment of Lawful Permanent Resident Status) and tax forms (including 1040 v. 1040NR; 8833, 5471, 8854, 8621, 3520, 8864, 8858) and FinCEN form 114, can impact the determination of whether someone who has a “green card” in their pocket is or is not a United States person.
What Questions Need to be Asked if You Live (with a “green card”) in one of the 67 Countries – with a U.S. Income Tax Treaty?
Depending upon the factual circumstances of each individual, they may be able to benefit from the international tax treaty law articulated by the U.S. Federal District Court in Aroeste v United States – Order (Nov 2023). Future posts will explore the legal relevance of some of the following questions to consider:
Has the individual filed any U.S. federal income tax returns since leaving the United States?
Was a professional tax return preparer hired or consulted about the filing of a federal income tax return (e.g., a certified public accountant, an enrolled agent, a full time tax return preparer, ta tax attorney, etc.)?
Has the individual been filing IRS Form 1040 Resident Tax Returns in the same way Mr. Aroeste was filing – based upon the advice (that turned out to be erroneous -although given in good faith) from their U.S. tax return preparer?
What steps if any have been taken to notify the U.S. federal government (irrespective of the agency) regarding their physical residency outside the United States?
This information is intended to provide general information about tax expatriation legal concepts under U.S. law to help readers better understand often very complex issues within the U.S. international tax field for citizens and lawful permanent residents. General legal information is not the same as legal advice, that is, the concrete application of law to a specific case with unique and particular facts.
Legal advice also should include strategic planning and advice to a particular case. A legal adviser should be able to assist an individual in taking important decisions and steps, related to the specific goals of the individual, while understanding the legal and tax consequences of each step. There are a range of consequences that the “U.S. tax expatriation” laws impose upon different types of transactions, transfers, reorganization of assets, etc. None of these items are discussed in this Tax-Expatriation.com This is not legal advice.
Countries From Which Viewers Read Posts – Tax-Expatriation.com – First Week of 2024 (Which Ones are Tax Treaty Countries?) – Applying the “Escape Hatch”
The whole idea of the “escape hatch” for tax treaties is an excellent way of explaining how and when tax treaty law applies in different circumstances. Importantly, the U.S. federal government cannot deny an individual (or presumably a company either) from properly applying the law of a tax treaty – even if they “gave [an] untimely notice of his treaty position “. See further comments at the end of this post and the District Court’s opinion here – Aroeste v United States – Order (Nov 2023). Meanwhile, see below the 22 countries from where global readers viewed Tax-Expatriation.comduring the first full week of 2024.
Below is the list of 22 countries (including the United States) from where readers hailed, who read Tax-Expatriation.comduring the first week of 2024. All, but Brazil, Croatia, Nigeria, the United Arab Emirates, Colombia, Kenya and Bermuda have income tax treaties with the United States.
This means that all other individuals are connected with the following 14 countries that have tax treaties with the United States:
Mexico
India
Canada
United Kingdom
Switzerland
Australia
China
Spain
Turkey
Germany
Japan
Romania
Portugal
Netherlands
Further, all individuals who might have never formally abandoned their lawful permanent residency (“green card”), maybe never filed specific IRS tax forms, and yet reside in one of these fourteen (14) treaty countries could be eligible for the application and the specific benefits of international income tax treaty law. This, along the lines of the decision in Aroeste v United States (Nov. 2023). In addition, there could be other tax treaty benefits applicable to those individuals in these fourteen countries depending upon where are their assets, what type of income they have, where does the income come from, and where do they reside.
The tax treaty rights discussed here are established by law, as elucidated by the Federal District Court in Aroeste v United States (Nov. 2023). The Court determined that the IRS cannot simply assert an individual’s ineligibility for treaty law provisions based solely on the failure to file specific IRS forms within the government-defined “timely” period. The Court emphasized that there is no automatic waiver of treaty benefits as a matter of law, while acknowledging: “. . . Aroeste gave untimely notice of his treaty position. . .” For specific excerpts from the opinion, please refer to the highlighted portions below. To access the complete opinion, please consult Aroeste v United States – Order (Nov 2023).
* * * * * * * * *
B. Whether Aroeste Did Not Waive the Benefits of the Treaty Applicable to Residents of Mexico and Notified the Secretary of Commencement of Such Treatment.
To establish Mexican residency under the Treaty, and thus avoid the reporting requirements of “United States persons,” Aroeste must have filed a timely income tax return as a non-resident (Form 1040NR) with a Form 8833, Treaty-Based Return Position Case 3:22-cv-00682-AJB-KSC Document 90 Filed 11/20/23 PageID.2722 Page 8 of 17 9 22-cv-00682-AJB-KSC Disclosure Under Section 6114 or 7701(b). Indeed, Aroeste did not submit Form 8833 to notify the IRS of his desired treaty position for the years 2012 and 2013 until October 12, 2016, when he submitted an amended tax return for both years at issue. (Id.) The Government asserts that because Aroeste did not timely submit these forms, he cannot establish that he notified the IRS of his desire to be treated solely as a resident of Mexico and not waive the benefits of the Treaty. (Id. at 4.) The Government relies upon United States v. Little, 828 Fed. App’x 34 (2d Cir. 2020) (“Little II”), a criminal appeal in which the court held a lawful permanent resident of a foreign country was a “‘resident alien’ or ‘person subject to the jurisdiction of the United States’ with an obligation to file an FBAR.” Id. at 38 (quoting 31 C.F.R. § 1010.350(a), (b)(2)).
In response, Aroeste asserts that while he agrees with the Government that I.R.C. § 6114 requires disclosure of a treaty position, he disagrees as to the consequences for a taxpayer’s failure to timely file the disclosure. (Doc. No. 75-1 at 6.) While the Government asserts the failure to timely file Forms 1040NR and 8833 deprives individuals of the Treaty benefits provided, Aroeste argues instead that I.R.C. § 6712 provides explicit consequences for failure to comply with § 6114. Specifically, § 6712 states that “[i]f a taxpayer fails to meet the requirements of section 6114, there is hereby imposed a penalty equal to $1,000 . . . on each such failure.” I.R.C. § 6712(a). Based on the foregoing, Aroeste argues the taxpayer does not lose the benefits or application of the treaty law.1 (Doc. No. 75-1 at 6.) In United States v. Little, 12-cr-647 (PKC), 2017 WL 1743837, at *5 (S.D. N.Y. 1 Aroeste further asserts that published agency guidance, letter rulings, and technical advice support his position. (Doc. No. 75-1 at 7.) For example, in 2007, an IRS agent sought advice from IRS Counsel asking, “Do we have legal authority to deny a tax treaty because Form 8833 is not attached or the treaty is claimed on the wrong Form (1040EZ or 1040)?” Legal Advice Issued to Program Managers During 2007 Document Number 2007-01188, IRS. IRS Counsel responded, “No, you cannot deny treaty benefits if the taxpayer is entitled to them. You may impose a penalty of $1,000 under section 6712 of the Code on an individual who is obligated to file and does not.” Id. As to this, the Court finds it has no precedential value under I.R.C. § 6110(k)(3), which states that “a written determination may not be used or cited as precedent.” See Amtel, Inc. v. United States, 31 Fed. Cl. 598, 602 (1994) (“The [Internal Revenue] Code specifically precludes [plaintiff] and the court from using or citing a technical advice memorandum as precedent.”) Case 3:22-cv-00682-AJB-KSC Document 90 Filed 11/20/23 PageID.2723 Page 9 of 17 10 22-cv-00682-AJB-KSC May 3, 2017) (“Little I”), a criminal case for the plaintiff’s willful failure to file tax returns, the court stated the plaintiff’s same argument “that the failure to take a Treaty position can result only in a financial penalty also lacks merit. 26 U.S.C. § 6712(c) expressly states that ‘[t]he penalty imposed by this section shall be in addition to any other penalty imposed by law.’” (emphasis added).
I have been consulted over the years by other taxpayers which are cited now as published decisions by the government and the Federal District Court (Southern District of California). These cases are referenced and cited in my own most recent case of Aroeste v United States (Nov. 2023).
However, in Little I, the plaintiff never attempted to take a treaty position. Next, in Shnier v. United States, 151 Fed. Cl. 1, 21 (2020), the court denied the plaintiffs’ claims for relief based on tax treaties because they failed to disclose a treaty based position on their tax returns pursuant to I.R.C. § 6114 “and did not attempt to cure this omission in their briefing[.]” Although the plaintiffs in Shnier were naturalized U.S. citizens who attempted to recover their income taxes under I.R.C § 1297, the court’s brief discussion of I.R.C. § 6114 in relation to a treaty-based position is instructive that an untimely notice of a treaty position does not bar the individual from taking such position. Moreover, in Pekar v. C.I.R., 113 T.C. 158 (1999), the court noted that a taxpayer who fails to disclose a treaty-based position as required by § 6114 is subject to the $1,000 penalty, but stated “there is no indication that this failure estops a taxpayer from taking such a position.” Id. at 161 n.5.2 The Court agrees with Aroeste.
Although Aroeste gave untimely notice of his treaty position, the Court finds this does not waive the benefits of the Treaty as asserted by the Government. Rather, I.R.C. § 6712 provides the consequences for failure to comply with I.R.C. § 6114, namely a penalty of $1,000 for each failure to meet § 6114’s requirements of disclosing a treaty position.
* * * * * * * * *
For individuals living in any of these 14 tax treaty countries (or any of the total 67 income tax treaty countries), the key takeaway is that, based on their specific circumstances, they might be eligible to leverage the international tax treaty principles outlined in the Aroeste v United States case (Nov. 2023). The forthcoming post will pose questions for consideration by the potentially millions of individuals affected by these rules of law.
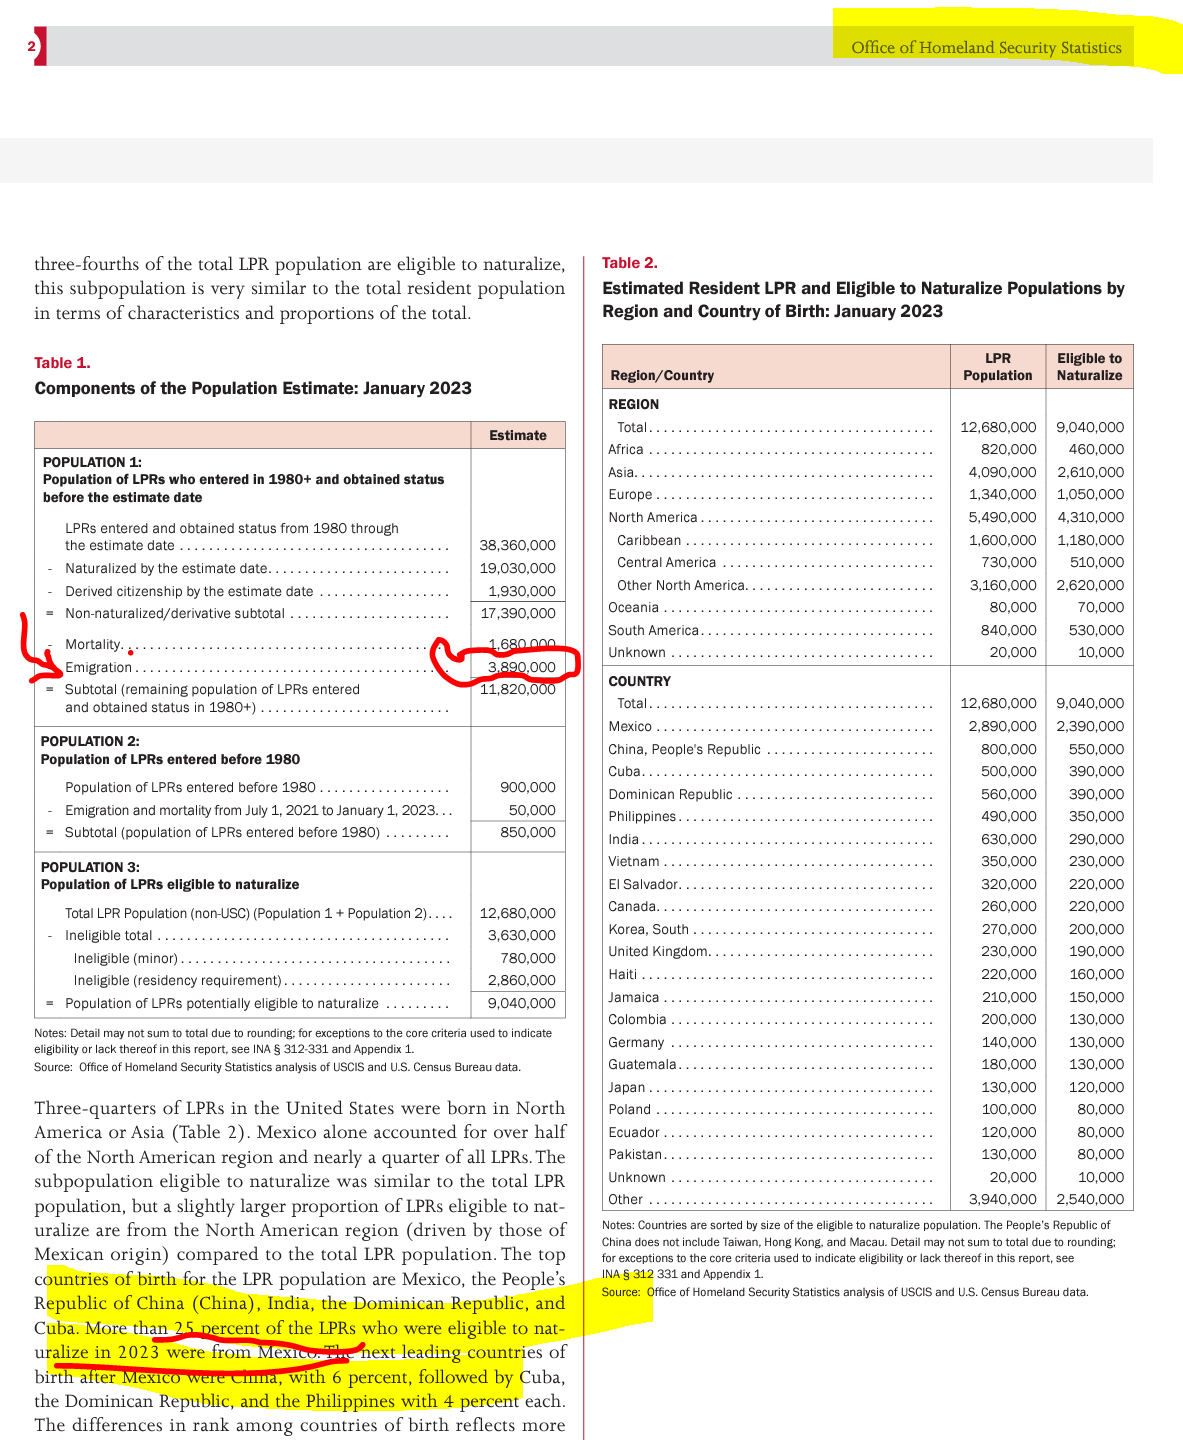
DHS Report: 3.89M Emigrated LPRs — Who Falls Under the Tax Treaty Escape Hatch?
Clear U.S. tax and legal relief now exists for a significant portion of the 3.89 million Lawful Permanent Residents (LPRs) who never formally abandoned their U.S. immigration status. This relief stems from two sources in the law:
(i) Tax treaty laws that apply to individuals residing in one of the 67 income tax treaty countries with the United States, recently including Chile.
(ii) Legal principles, recently confirmed by the Federal Court in Aroeste v. United States, that establish that individuals can apply tax treaty laws (when applicable) even if they missed certain filing deadlines set by the Internal Revenue Service. The Court termed this provision an “escape hatch,” allowing individuals, depending on specific circumstances, to be considered non-residents of the United States (not “United States persons”). This can be true under the relevant treaty, even if they never formally abandoned their LPR status.
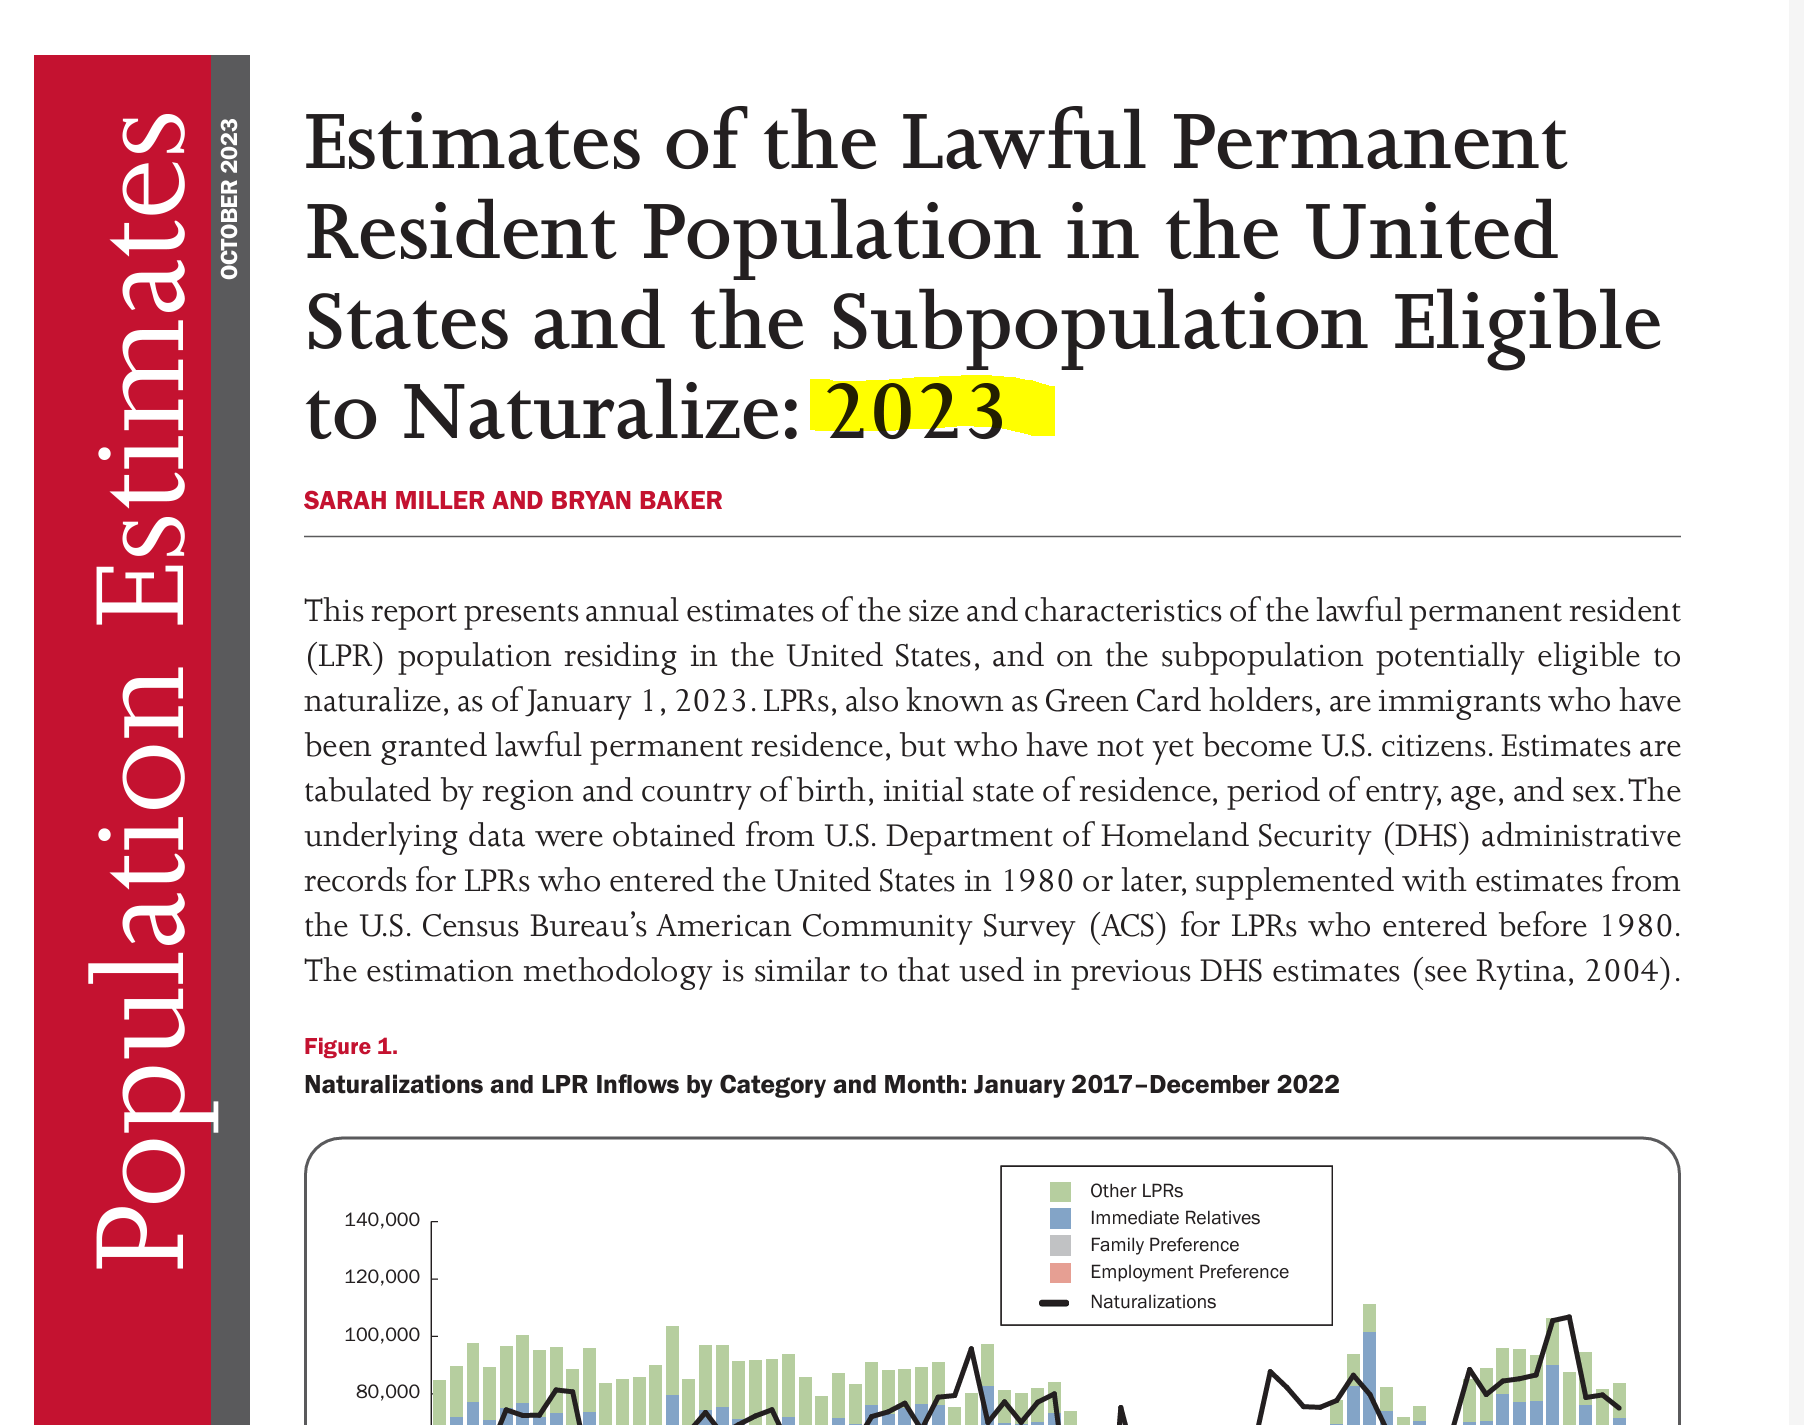
The 2023 DHS report estimates that nearly 4 million individuals have emigrated from and left the United States and are now living somewhere around the world. Notably, Mexico constitutes the largest share at about 25% of the total LPR population who have left the United States.
The DHS report allows the reader to extrapolate that around 1 million individuals, similar to Mr. Aroeste, are living in Mexico and did not formally abandon their LPR status by filing Form I-407, Record of Abandonment of Lawful Permanent Resident.
Aroeste v. United States is the third case I’ve litigated, examining whether individuals with a “green card” residing outside the United States in a tax treaty country are considered U.S. income tax residents. The previous two cases (involving Mexican and German citizens) didn’t progress to the oral argument stage; as the government conceded both before trial. See, IRS Chief Counsel Concedes Tax Treaty Residency Position for LPR German Taxpayer in Tax Court
A FOIA response yielded surprising information; the government records indicate that only 46,364 Forms I-407 were filed from 2013 to 2015.
(Source: Federal Government Response to FOIA Request: Office of Performance and Quality (OPQ), Performance Analysis and External Reporting (PAER), JJ)
SOURCE: Federal Government Response to FOIA Request: Office of Performance and Quality (OPQ), Performance Analysis and External Reporting (PAER), JJ
What can we glean from the DHS report and the LPR – I-407 information obtained through the FOIA response? There is a substantial gap in the millions; millions of individuals who have physically left the U.S. to reside elsewhere globally, compared to the relatively smaller number of tens of thousands who have officially filed Form I-407, Record of Abandonment of Lawful Permanent Resident.
Conclusion
Importantly, now under the legal principles established in Aroeste v. United States, individuals residing in one of the 67 countries covered by an income tax treaty have specific legal relief from the worldwide reporting of income to the United States government.
Mérida – the Place to be in February (19th and 20th)
The implications of the Aroeste v United States – Order (Nov 2023) particularly for millions of taxpayers globally and “U.S.” taxpayers affected by pertinent tax treaty provisions, will be a focal point of discussion at the upcoming international tax conference in February.
The University of San Diego School of Law – Chamberlain International Tax Institute will take place on February 19th and 20th, 2024, at the International Convention Center in Mérida, Yucatán, México. You can register for the conference – HERE –
Among the courses offered, there will be a detailed examination of- Aroeste v. the United States: Limits on Government Authority Re: Tax Treaty Law ++– along with other international tax topics and sessions featuring much Moore:
United States Supreme Court – Tax Decisions & Moore
International Tax Reporting: New Reporting of International Partnerships – K-2s & K-3s
United States-based Cross-Border Real Estate Investments (Advanced)
U.S. Investor Visa Options and Limitations
California, Texas & Florida Probate Proceedings of Cross-Border Estates
Federal District Court Rules in Favor of Mexican Citizen – Aroeste vs. United States (LPR) – Tax Treaty Applies: Government’s Motion for Summary Judgment is Denied
Last week (Nov. 20, 2023), Judge Battaglia in the Southern District of California (San Diego) ruled in favor of our client Mr. Alberto Aroeste regarding the application of the U.S.-Mexico Tax Treaty. The DOJ, Tax Division arguments on behalf of the Internal Revenue Service in the case (and their Motion for Summary Judgment – MSJ) were largely rejected by the Court.
A thorough read of the Order from the Court is recommended to understand the substantial legal findings and legal analysis made by the Court relevant to those who possess a “green card” referred to as “lawfully admitted for permanent residence” in Title 8, § 1101(a)(13) [Immigration and Nationality Act]. Key to this case, Title 26, § 7701(b)(6) [Federal Tax Code] then rather contorts the concept by saying an individual is a “lawful permanent resident” in accordance with immigration laws; but then goes on to put conditions on who apparently is a “lawful permanent resident” for federal tax purposes. While immigration law requires the individual be ” . . . accorded the privilege of residing permanently in the United States as an immigrant in accordance with the immigration laws, such status not having changed”; the tax definition seems to ignore that status (i.e., has it changed and is the personal no longer accorded the privilege of residing permanently in the U.S.?).
The Board of Immigration Appeals (the “Board”), has long recognized that an alien’s status may change by operation of law, such that an alien may abandon his LPR status without a finding of removability (or, formerly, deportability or excludability) after a formal adjudicatory process. See United States v. Yakou, 428 F.3d 241, 247 (D.C. Cir. 2005); at 247-51 (discussing case law regarding abandonment and holding that an alien may abandon LPR status without formal administrative action); see also Matter of Quijencio, 15 I. & N. Dec. 95 (B.I.A. 1974); Matter of Kane, 15 I. & N. Dec. 258 (B.I.A. 1975); Matter of Muller, 16 I. & N. Dec. 637 (B.I.A. 1978); Matter of Abdoulin, 17 I. & N. Dec. 458, 460 (B.I.A. 1980); Matter of Huang, 19 I. & N. Dec. 749 (B.I.A. 1988).
The Court did not need to get into the nuances of immigration law to rule against the government in this case.
Some of the substantial takeaways from the decision are:
Waiver of the Tax Treaty: The government cannot assert an individual waived the treaty law because she initially filed the wrong IRS forms (1040) instead of the non-resident form (1040NR) and IRS Form 8833.
The Court agrees with Aroeste. Although Aroeste gave untimely notice of his treaty position, the Court finds this does not waive the benefits of the Treaty as asserted by the Government. Rather, I.R.C. § 6712 provides the consequences for failure to comply with I.R.C. § 6114, namely a penalty of $1,000 for each failure to meet § 6114’s requirements of disclosing a treaty position.
Aroeste v United States – Order 20 Nov 2023 (p. 17)
Expatriation Tax form – IRS Form 8854: Validity and its Failure to Comply with the Administrative Procedure Act (“APA”)
C. Whether Aroeste Was Required to File Form 8854 The Government next argues that even if the IRS had accepted Aroeste’s amended returns, neither amended return would have properly notified the IRS of a commencement of treaty benefits because both failed to attach Form 8854, as required by IRS Notice 2009-85. (Doc. No. 76-1 at 4–5.) The Government concedes Aroeste attached Form 8833 to both amended forms. (Id.) Aroeste responds that Notice 2009-85 is not binding authority as it fails to comply with the Administrative Procedures Act (“APA”). (Doc. No. 78-1 at 8 (citing Green Valley Investors, LLC v. Comm’r of Internal Revenue, 159 T.C. No. 5, at *4 (Nov. 9, 2022)) (under the APA, agencies must follow a three-step procedure for “notice-and-comment” rulemaking, but this requirement does
not apply to “interpretive rules, general statements of policy, or rules of agency organization, procedure, or practice.”).) The Court agrees. In Mann Construction, Inc. v. United States, 27 F.4th 1138 (6th Cir. 2022), the court found that Notice 2007-83 failed to comply with the APA’s notice-and-comment procedure. Similarly here, because Notice 2009-85 has not been subject to a notice-and-comment procedure, it does not comply with the APA and thus is not binding. As such, Aroeste was not required to file Form 8854 with his amended returns.
Aroeste v United States – Order 20 Nov 2023 (p. 11)
Tax Treaty Law Applies – Article 4 Regarding Tax Residency
Various detailed analysis and discussions from the Court –
Aroeste v United States – Order 20 Nov 2023 (p. 11-14)
The Preamble to the FBAR Regulations is Not the Law –
. . . the Government points to the preamble to the 31 C.F.R. Part 1010 regulations, providing that “[a] legal permanent resident who elects under a tax treaty to be treated as a non-resident for tax purposes must still file the FBAR.” Amendment to the Bank Secrecy Act Regulations—Reports of Foreign Financial Accounts, 76 Fed. Reg. 10234-01 (Feb. 24, 2011). The Court finds this unavailing. The Government’s argument does not refute the plain language of the FBAR regulations, which explicitly invoke provisions of Title 26, including the provision that requires consideration of an individual’s status under an applicable tax treaty for the purpose of determining whether an individual is a “United States person” subject to FBAR filing. Specifically, Title 31 C.F.R. § 1010.350, which governs reporting of FBARs, subsection (b)(2) states that a “resident of the United States is an individual who is a resident alien under 26 U.S.C. 7701(b) and the regulations thereunder . . . .” The Government fails to cite to any case law or statue indicating otherwise, and the Court finds none. As such, because the Court finds the Treaty applicable to Aroeste, then the residence provisions of the Treaty, or the “tie breaker rules” dictates whether Aroeste may be treated as a nonresident alien.
Aroeste v United States – Order 20 Nov 2023 (p. 14)
This is the third court case (the other two were in U.S. Tax Court) I have had over the last several years where the IRS tried to assess substantial penalties and taxes against LPRs who resided substantially outside the United States. The other two cases were conceded by the IRS prior to going to trial. One case had over US$40M at stake as assessed by the IRS. This case, in federal district court, was pushed all the way to this favorable (to Mr. Aroeste and those around the world in similar circumstances) outcome by the government. We were successful with all of these non-U.S. citizen cases (two brothers from Mexico and an individual from Germany).
“LPR Tax Limbo” – Formal Abandonment of LPR (Form I-407) – BIG GAP with Actual Emigration of LPRs
Millions of lawful permanent residents (LPRs) who have left the U.S. and not “formally abandoned” their LPR status (by filing Form I-407, Record of Abandonment of Lawful Permanent Resident) typically remain in some kind of “LPR U.S. tax limbo.” How many individuals worldwide are in this LPR U.S. tax limbo?
Why are these numbers important for the tax-expatriation analysis? See, a recent post, Why Most LPRs Residing Overseas Haven’t a Clue about the Labyrinth of U.S. Taxation and Bank and Financial Reporting of Worldwide Income and Assets (Part I). Indeed, most individuals probably do not think they are a U.S. federal income tax resident when they leave the U.S. to reside overseas back to their home country. Why would they? There is no tax training manual provided to LPRs who leave the U.S. and no tax advisories – reflected on the card itself (unlike the last page of the U.S. passport, paragraph D). More precisely, most are probably not giving much, if any thought, to the complex U.S. federal tax residency rules and their extraterritorial application.
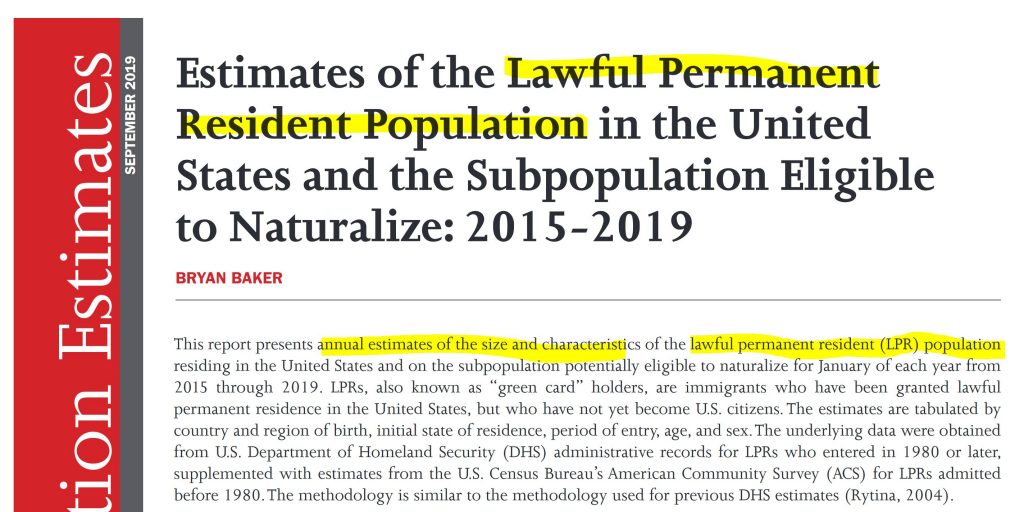
The “big gap” referred to above can be identified from the the Office of Immigration Statistics (OIS) report titled: Estimates of the Lawful Permanent Resident Population in the United States and the Subpopulation Eligible to Naturalize: 2015-2019. According to the report, more than 1 million individuals become LPRs each year. Between naturalization, mortality and emigration the report shows that the LPR population, year over year, has remained stable. In 2019 the total number of LPRs per this report was 13.6 million, up from just 13.0 million in 2015.
The “gap” is the difference between the numbers of LPRs who have left-emigrated the U.S. (some 3+ million) compared to something like an annual average of 15-19 thousand who have filed Form I-407. The gap is in the millions of persons who are in LPR U.S. tax limbo.
Mexico
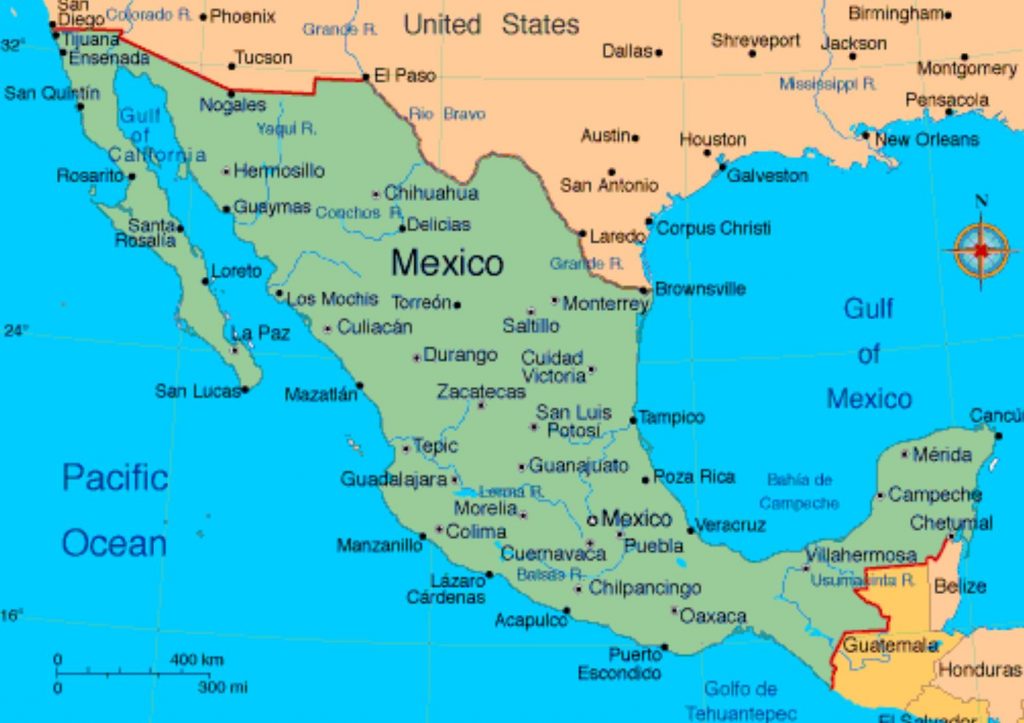
The report is also worth reading if you want to understand the demographics of the LPR population. Mexico has about 2.5 million (which is by far the greatest number) of the total 13+ million LPR population.
As the report points out there is no reliable direct measurements of LPR emigration. They do not exist. This lack of information is what drove me to file a FOIA request with the government to request information about the number USCIS Forms I-407 that are filed with the government. See, also quarterly statistics of the USCIS – Form I-407, Record of Abandonment of Lawful Permanent Resident Status (partial information for years 2016-2019).
The information I obtained in the FOIA response was surprising, since the government had records showing only 46,364 Forms I-407 were filed in the years 2013 through 2015, as follows:
SOURCE: Federal Government Response to FOIA Request: Office of Performance and Quality (OPQ), Performance Analysis and External Reporting (PAER), JJ
This represents an average of only 15,455 individuals who formally abandoned their LPR status. Contrasted with more than 3.6 million estimated to have emigrated in 2019 per the DHS report leaves a massive gap of well over 3 million persons who held a “green card” and have left. They are now in LPR U.S. tax limbo.
What about the tax consequences? How many of these LPRs who left the U.S. know, understand or have any idea whatsoever of the federal tax filing obligations regarding their status?
What is the takeaway from the DHS report and LPR – I-407 information provided to me by the FOIA response? There is a discrepancy in the millions of people. Millions of individuals who actually leave or have left the U.S. to reside somewhere else around the world; compared to only some tens of thousands of individuals who have formally filed Form I-407, Record of Abandonment of Lawful Permanent Resident.
What can these individuals do to get out of the LPR U.S. tax limbo?
New Treasury Regulations Can Effect Some Long-Term Residents (“Green Card” Holders)
There have been numerous posts about how Lawful Permanent Residents (“LPRs”) who have not formally abandoned their green card might have adverse U.S. tax consequences as part of the U.S. “expatriation tax.”
The U.S. Treasury issued new Regulations that can impact LPRs who have previously filed U.S. 1040NR tax returns under an applicable income tax treaty. On December 13, 2016, the these final regulations require foreign-owned, single-member U.S. limited liability companies (“SM-LLCs”) that are treated as disregarded entities for U.S. tax purposes to file an information return to report certain transactions. These Treasury Regulations, 26 CFR § 1.6038A-1(c) require these foreign-owned SM LLCs to be treated as if they are a separate domestic “C” corporation specifically for reporting purposes.
Treasury Regulations, 26 CFR § 1.6038A-1(c) require foreign-owned SM LLCs to be treated as if they are a domestic “C” corporation for reporting purposes (Form 5472)
An individual who is a LPR can fall into this category in certain circumstances; namely where they cease to be a “U.S. person” under IRC Section 7701(b)(6). See, IRS Form 5472 directly here –
Part II: Who is a “long-term” lawful permanent resident (“LPR”) and why does it matter?
A post in August 2014 explained the basic rule of who is a “long-term resident” as that technical term is defined for tax purposes in IRC Section 877 (e)(2). There is much confusion about how the tax law defines a “lawful permanent resident” (“LPR”) versus how immigration law defines what is almost the same concept. The statutes are different and have definitions in two separate federal codes (Title 26, the federal tax provisions and Title 8, the immigration law provisions).
This follow-up comment is to highlight some key concepts about why it matters if you become a “long-term” resident as that term is defined in the tax law.
A LPR can reside for substantially shorter periods in the U.S. (shorter than the apparent 7 or 8 years identified in the statute), and still be a “long-term resident” per IRC Section 877 (e)(2) depending upon the facts of any particicular case.
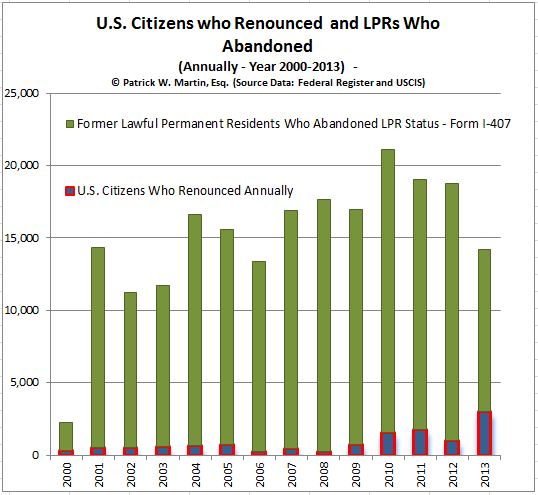
There are far more LPRs who abandon their status (formally) than U.S. citizens who formally take the oath of renunciation. See the table above reflecting those who have formally renounced U.S. citizenship versus those who have formally abandoned their LPR status.
Plenty of LPRs informally abandon their LPR status for immigration purposes by moving and living permanently outside the U.S.
There are plenty of timing issues for LPRs surrounding how and when they have “abandoned” their LPR status for purposes of IRC Section 877 (e)(2). See –
Survey of the Law of Expatriation from 2002: Department of Justice Analysis (Not a Tax Discussion)
Most discussions regarding renunciation/relinquishment of U.S. citizenship are highly focused towards the U.S. federal tax consequences. Today, the focus is on a 2002 report prepared by the DOJ for the Solicitor General, who supervises and conducts government litigation in the United States Supreme Court.
You have asked us for a general survey of the laws governing loss of citizenship, a process known as “expatriation” (also known within the specific context of naturalized citizens as “denaturalization”). See, e.g.,Perkins v. Elg, 307 U.S. 325, 334 (1939) (“Expatriation is the voluntary renunciation or abandonment of nationality and allegiance.”). Part I of this memorandum provides a general description of the expatriation process. Part II notes the relative difficulty of expatriating a person on the grounds that he has either obtained naturalization in, or declared allegiance to, a foreign state, absent evidence of a specific intention to relinquish U.S. citizenship apart from the act of naturalization or declaration itself. Part III analyzes the expatriation of a person who serves in a foreign armed force
engaged in hostilities against the United States.1
*
1 Editor’s Note: The original footnote 1 has been removed in order to preserve the confidentiality of internal government deliberations.
* * *
*
. . . In 1868, Congress declared that “the right of expatriation is a natural and inherent right of all people, indispensable to the enjoyment of the rights of life, liberty, and the pursuit of happiness.” Act of July 27, 1868, ch. 249, pmbl., 15 Stat. 223, 223; see also 8 U.S.C. § 1481 note (2000) (quoting Rev. Stat. § 1999 (2d. ed. 1878), 18 Stat. pt. 1, at 350 (repl. vol.)) (same).
*
That declaration further stated that “any declaration, instruction, opinion, order, or decision of any officers of this government which denies, restricts, impairs, or questions the right of expatriation, is hereby declared inconsistent with the fundamental principles of this government.” 15 Stat. at 224. Similarly, the Burlingame Treaty of 1868 between the United States and China recognized “the inherent and inalienable right of man to change his home and allegiance, and also the mutual advantage of . . . free migration and emigration . . . for purposes of curiosity, of trade, or as permanent resident s.” U.S.-China, art. 5, July 28, 1868, 16 Stat. 739, 740. Congress provided specific legislative authority for nullifying citizenship when, in 1907, it enacted the predecessor of the modern federal expatriation statute.
* * *
*
II. Foreign Naturalization or Declaration of Foreign Allegiance
*
Under federal law, a U.S. citizen can lose his nationality if he voluntarily “obtain[s] naturalization in a foreign state… after having attained the age of eighteen years.” 8 U.S.C. § 1481(a)(1). Likewise, a citizen of the United States could be expatriated if he voluntarily “tak[es] an oath or mak[es] an affirmation or other formal declaration of allegiance to a foreign state or a political subdivision thereof, after having attained the age of eighteen years.” Id. § 1481(a)(2). In either case, however, no loss of citizenship may result unless the citizen acts “with the intention of relinquishing United States nationality.” Id. § 1481(a).
*
The most common obstacle to expatriation in cases involving foreign naturalization or declaration of foreign allegiance is sufficient proof of a specific intention to renounce U.S. citizenship. Intent need not be proved with direct evidence, to be sure. It can be demonstrated circumstantially through conduct. Thus, in some cases, such as service in a hostile foreign military at war with the United States, the act of expatriation itself may even constitute “highly persuasive evidence…of a purpose to abandon citizenship.” Terrazas , 444 U.S. at 261 (quotations omitted).
*
* * *
Dual nationality, the Supreme Court has explained, is “a status long recognized
in the law.” Kawakita, 343 U.S. at 723. See also id. at 734 (“Dual nationality . . . is
the unavoidable consequence of the conflicting laws of different countries. One
who becomes a citizen of this country by reason of birth retains it, even though by
the law of another country he is also a citizen of it.”) (citation omitted); Savorgnan, 338 U.S. at 500 (although “[t]he United States has long recognized the general undesirability of dual allegiances[,] . . . [t]emporary or limited duality of citizenship has arisen inevitably from differences in the laws of the respective nations as to when naturalization and expatriation shall become effective . . .



 ar case. A legal adviser should be able to assist an individual in taking important decisions and steps, related to the specific goals of the individual, while understanding the legal and tax consequences of each step. There are a range of consequences that the “U.S. tax expatriation” laws impose upon different types of transactions, transfers, reorganization of assets, etc. None of these items are discussed in this









 how immigration law defines what is almost the same concept. The statutes are different and have definitions in two separate federal codes (Title 26, the federal tax provisions and Title 8, the immigration law provisions).


