International Tax · Citizenship Renunciation · LPR Abandonment
International Tax Shareholder
Green Card Holders (Abandonment) – so Many More than U.S. Citizens who Renounce: The Topsnik Problem(s)!
I have previously written (pre-Aroeste v. United States) about the thorny issues that LPRs face when spending substantial time outside the United States. See an earlier post titled:
I highlighted some key concepts about why it matters if you become a “long-term” resident as that term is defined in the tax law and now the case law in Aroeste makes these risks clear as confirmed in the landmark case.
A LPR can reside for substantially shorter periods in the U.S. (shorter than the apparent 7 or 8 years identified in the statute), and still be a “long-term resident” per IRC Section 877 (e)(2) depending upon the facts of any particular case.
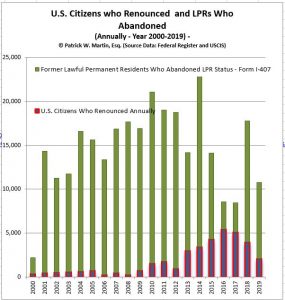
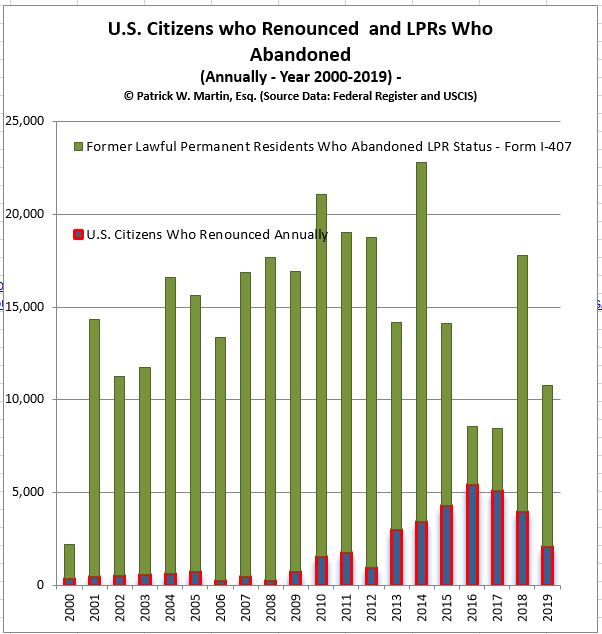
There are far more LPRs who abandon their status (formally) than U.S. citizens who formally take the oath of renunciation. See the table above reflecting those who have formally renounced U.S. citizenship versus those who have formally abandoned their LPR status.
Plenty of LPRs informally abandon their LPR status for immigration purposes by moving and living permanently outside the U.S.
There are plenty of timing issues for LPRs surrounding how and when they have “abandoned” their LPR status for purposes of IRC Section 877 (e)(2). See –
* More Green Card Holders Abandon Status Than Citizens Renounce Citizenship
A frequently overlooked fact is that:
Formal Abandonment of LPR Status Is More Common Than Citizenship Renunciation
Each year, substantially more lawful permanent residents formally abandon their green cards than U.S. citizens formally renounce citizenship. The focus in the press and media is typically U.S. citizens who formally renounce. Here is my most recently compiled graph, the total number of U.S. citizens renouncing is typically in the thousands (few) each year. It has trended downward post-COVID.
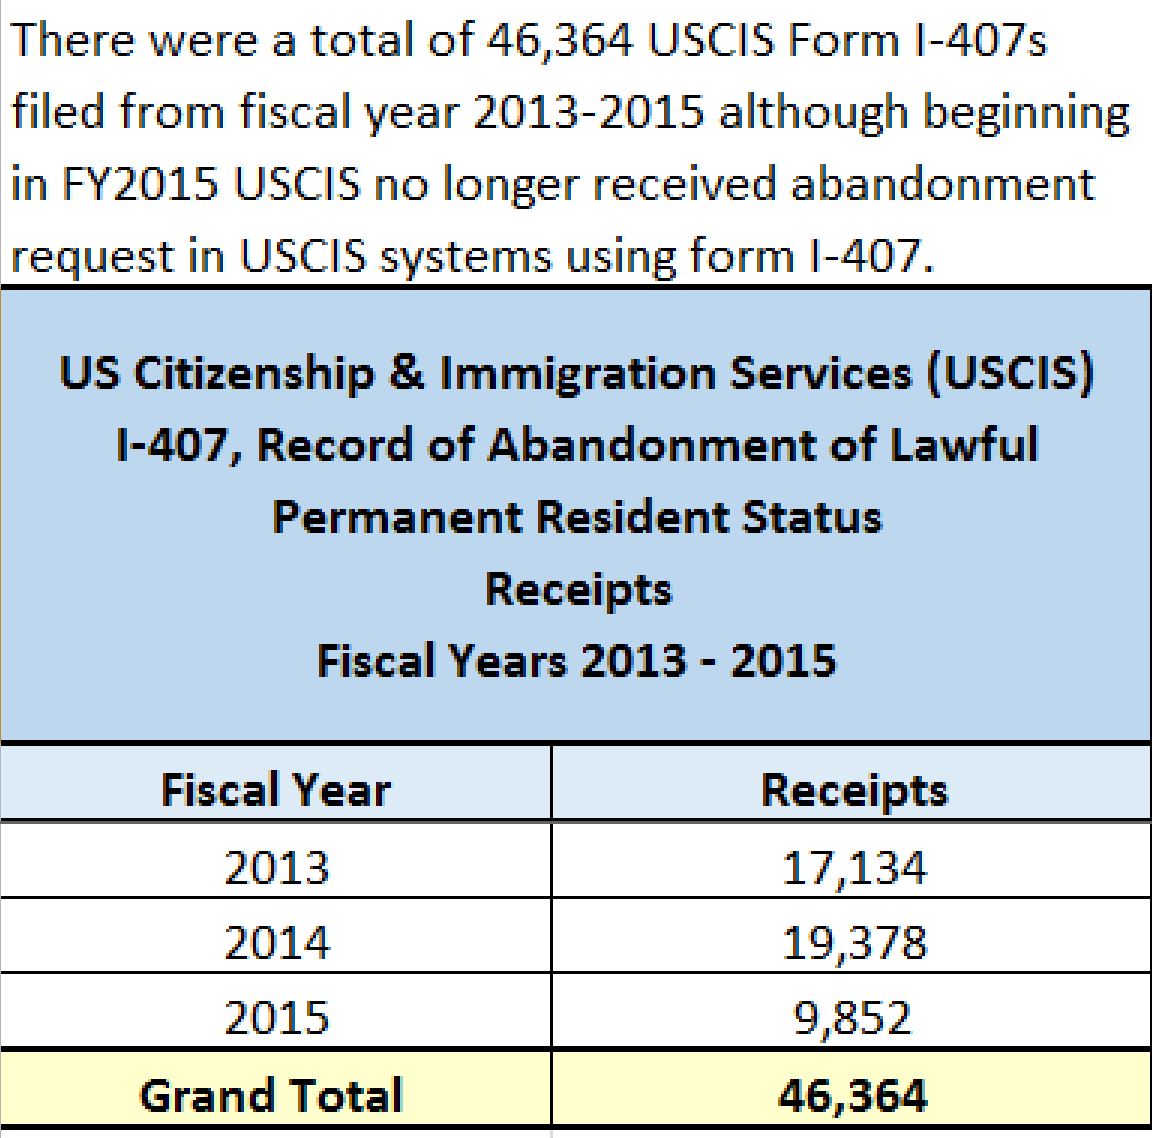
However, with LPRs, formal recognition of abandonment by filing Form I-407 (not including informal abandonments which are multiple times greater) is multiple times greater.
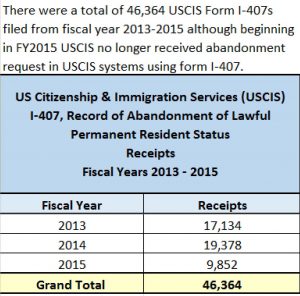
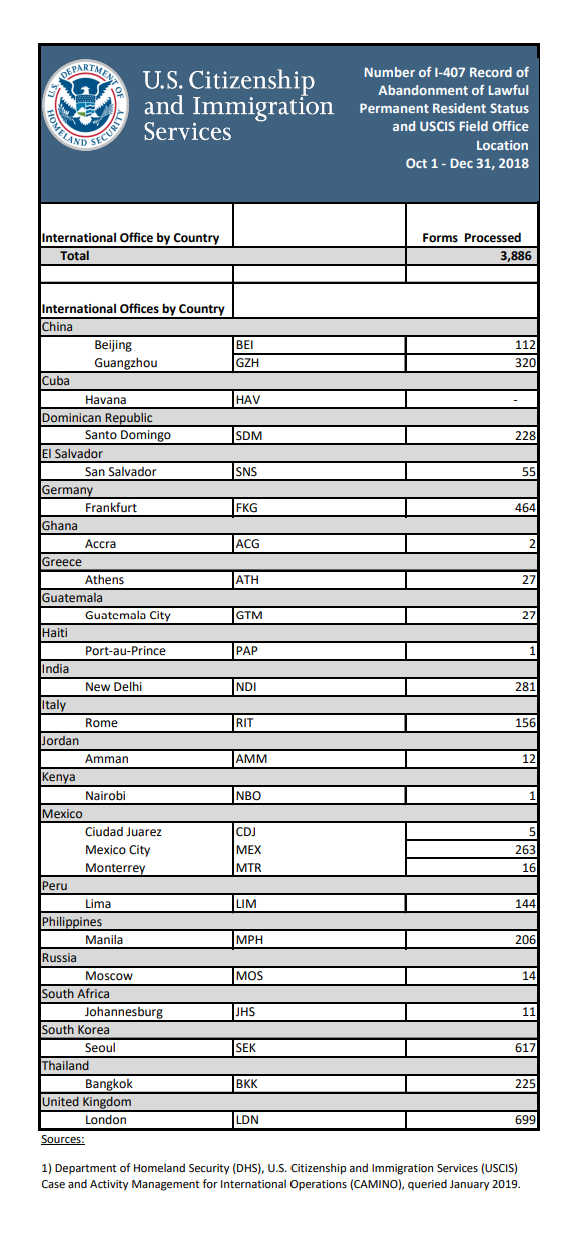
The graph I created several years ago, shows that formal LPR abandonments are mlutiple times greater than citizenship renunciation. I made a FOIA request with the government to request information about the number USCIS Forms I-407 that are filed with the government. See, also quarterly statistics of the USCIS – Form I-407, Record of Abandonment of Lawful Permanent Resident Status (partial information for years 2016-2019).
I have made a new FOIA request for more recent records, since this data is no longer public after the year 2019 year.
The statistics reflected above demonstrate that:
Formal green card abandonment significantly exceeds formal citizenship renunciations.
The population potentially affected by the expatriation rules is therefore much larger than many individuals around the world appreciate.
Lack of Control Over the Timing of Termination
One of the greatest risks for green card holders is that they often do not control the legal date on which their LPR status terminates, especially if they reside in a tax treaty country, per the analysis in the landmark case:
If abandonment is later determined by tax treaty law, effectively an CPB officer, the Executive Office for Immigration Review (EOIR) immigration court, the Board of Immigration Appeals (BIA)or a even a Federal District Court:
The taxpayer may not control the effective date of termination – “expatriation”.
If they are a “covered expatriate” or not.
The tax consequences may arise unexpectedly.
The timing can directly impact whether the tax expatriation rules apply and all of the potential consequences.
These timing issues become important when the IRS challenges tax positions taken on tax returns filed (or filed late) as was the case in Topsnik v. Commissioner (143 T.C. 240 (2014) – “Topsnik I”) and the subsequent case of Topsnik v. Commissioner (146 T.C. No. 1, 2016) – “Topsnik II”). In Topsnik II, Judge Kerrigan agreed with the IRS and ” . . . determined that P [taxpayer] was a “covered expatriate” who expatriated in 2010 and must recognize gain on the deemed sale of his installment obligation on the day before his expatriation under I.R.C. sec. 877A.” The U.S. Tax Court cited IRS Notice 2009-85 and explained it was not legally binding as follows:
We are not bound by Notice 2009-85, supra, see Compaq Computer Corp. v. Commissioner, 113 T.C. 363, 372 (1999), but it is an official statement of the Commissioner’s position and we may let it persuade us, see Nationalist Movement v. Commissioner, 102 T.C. 558, 583 (1994), aff’d, 37 F.3d 216 (5th Cir.1994).
The Tax Court went on to conclude these facts caused the court to conclude and uphold the IRS assessment of the “exit tax” on the German citizen Mr. Topsnik as a “covered expatriate” quoted as follows:
Notice 2009-85, sec. 8, 2009-45 I.R.B. at 611, explains that for purposes of certifying tax compliance for the five years before expatriation pursuant to section 877(a)(2)(C):
All U.S. citizens who relinquish their U.S. citizenship and all long-term residents who cease to be lawful permanent residents of the United States (within the meaning of section 7701(b)(6)) must file Form 8854 in order to certify, under penalties of perjury, that they have been in compliance with all federal tax laws during the five years preceding the year of expatriation. Individuals who fail to make such certification will be treated as covered expatriates within the meaning of section 877A(g) * * *
For the year of his expatriation petitioner failed to complete and file a Form 8854 certifying under penalties of perjury that he has complied with all of his U.S. Federal tax obligations for the five taxable years preceding the taxable year that includes his expatriation date. Respondent [IRS] has provided evidence that petitioner did not file all of his U.S. income tax returns before expatriatingand was not in payment compliance for taxes owed for the five years before expatriation in taxable year 2010. Thus petitioner could not have certified under penalties of perjury on a Form 8854 that he had been in tax compliance for the five years before expatriation. Consequently, because petitioner failed to certify tax compliance for the five years before expatriation, he is a “covered expatriate” as defined by section 877A(g)(1)(A).
Importantly, the court in Aroeste concluded IRS Form 8854 was not required to be filed (even though the DOJ attorney argued it was required – as set forth in the instructions to the form) as explained below:
C. Whether Aroeste Was Required to File Form 8854
The Government next argues that even if the IRS had accepted Aroeste’s amended
returns, neither amended return would have properly notified the IRS of a commencement of treaty benefits because both failed to attach Form 8854, as required by IRS Notice 2009- 85.(Doc. No. 76-1 at 4–5.) The Government concedes Aroeste attached Form 8833 to both
amended forms. (Id.)
Aroeste responds that Notice 2009-85 is not binding authority as it fails to comply
with the Administrative Procedures Act (“APA”). (Doc. No. 78-1 at 8 (citing Green Valley
Investors, LLC v. Comm’r of Internal Revenue, 159 T.C. No. 5, at *4 (Nov. 9, 2022)) (under
the APA, agencies must follow a three-step procedure for “notice-and-comment”
rulemaking, but this requirement does not apply to “interpretive rules, general statements
of policy, or rules of agency organization, procedure, or practice.”).) The Court agrees. In
Mann Construction, Inc. v. United States, 27 F.4th 1138 (6th Cir. 2022), the court found
that Notice 2007-83 failed to comply with the APA’s notice-and-comment procedure.
Similarly here, because Notice 2009-85 has not been subject to a notice-and-comment procedure, it does not comply with the APA and thus is not binding. As such, Aroeste was not required to file Form 8854 with his amended returns.
Both the Green Valley Investors LLC case and Mann Construction were 2022 cases, some 6 years after Topsnik II.
My law firm, Chamberlain Hrdlicka, successfully represented the taxpayers in Green Valley and of course in Aroeste.
Practical Lessons for Green Card Holders
The combined lessons from Aroeste, Topsnik I, and Topsnik II are significant.
Before Obtaining a Green Card
Individuals should understand:
The long-term resident rules and their U.S. tax obligations and reporting obligations;
The expatriation tax provisions and how they generally apply;
The “covered expatriate” tax regime and what steps to take;
The impact of income tax treaties with countries in the United States.
Before Formally Reporting the Abandonment (or Informally Abandoning) a Green Card
Individuals should carefully evaluate:
The date expatriation may occur;
Whether Form I-407 should be filed;
Tax compliance under U.S. tax laws (and what that means), including for the preceding five years to abandonment;
What notifications should be provided and when (not necessarily formal tax form filings);
Potential exit tax exposure – depending upon total assets, liabilities, type of assets and anticipated future income and gains;
Treaty residency positions and the particular facts of each case;
Reporting obligations, and which ones are mandatory or not – including IRS Forms 8833 and 8854.
Most Important Takeaway?
A green card holder does not necessarily need to spend seven or eight years physically living in the United States before becoming subject to the long-term resident and expatriation tax rules. The interaction of immigration law, tax law, treaty provisions, and reporting requirements can produce unexpected results. The recent landmark decision in Aroeste that I handled, confirms that these issues are not merely theoretical—they are increasingly becoming the subject of significant litigation and judicial scrutiny.
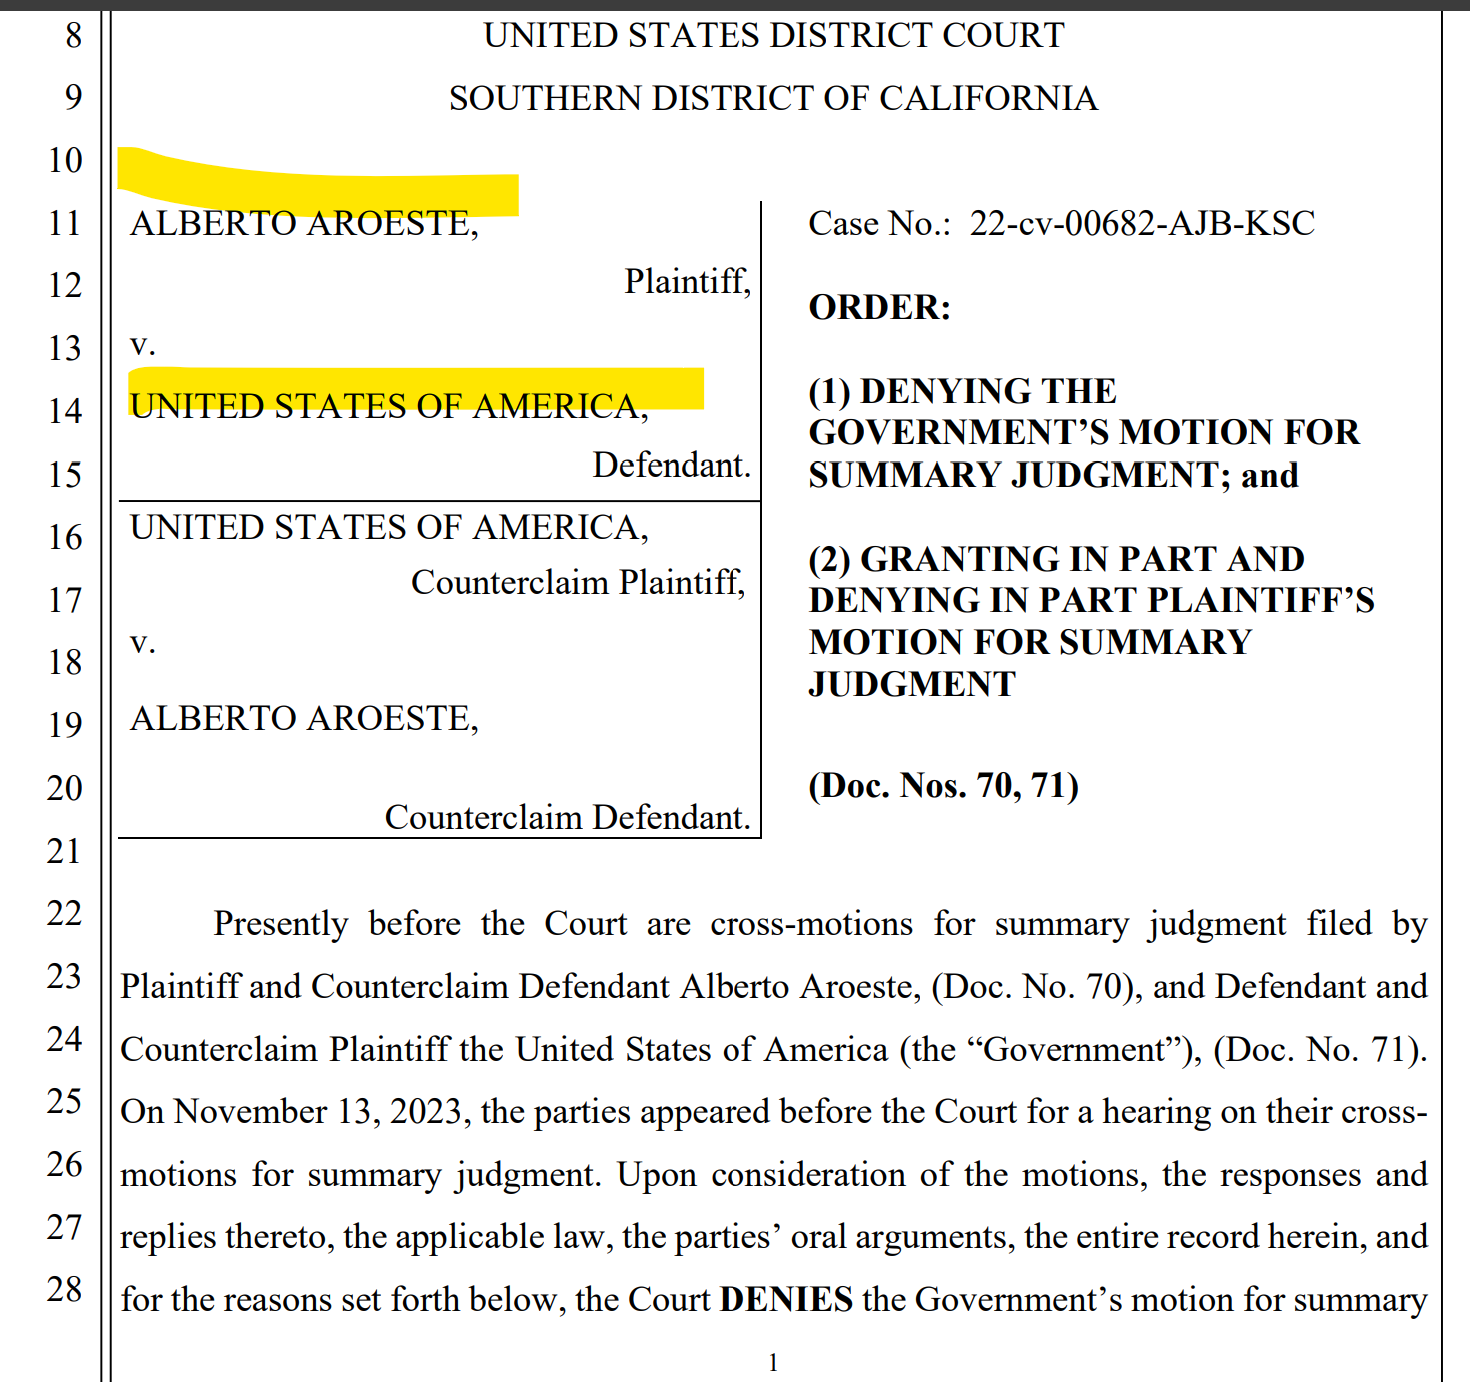
Many individuals have no idea that, under the legal principles confirmed in the federal district court case I litigated — Aroeste v United States, 22-cv-00682-AJB-KSC (20 Nov. 2023) – they may already be treated as “covered expatriates” as a matter of law.
Along Comes Section 2801 – and 2025 Final Regulations – The “Forever Taint” to Family and Friends (Paying the Taxman)
Aroeste – Landmark Decision Confirms the Law – Tax Treaty Law Applies – Taxpayers Do Not Waive Benefits per Gov’t
These writings all addressed the same underlying legal and policy expectations that courts would eventually be required to confront — issues now directly addressed in Aroeste. The Aroestedecision is also consistent with positions I successfully advanced in three separate U.S. Tax Court cases involving green card holders, none of which resulted in published opinions because the government ultimately conceded to my arguments and my clients prevailed prior to trial.
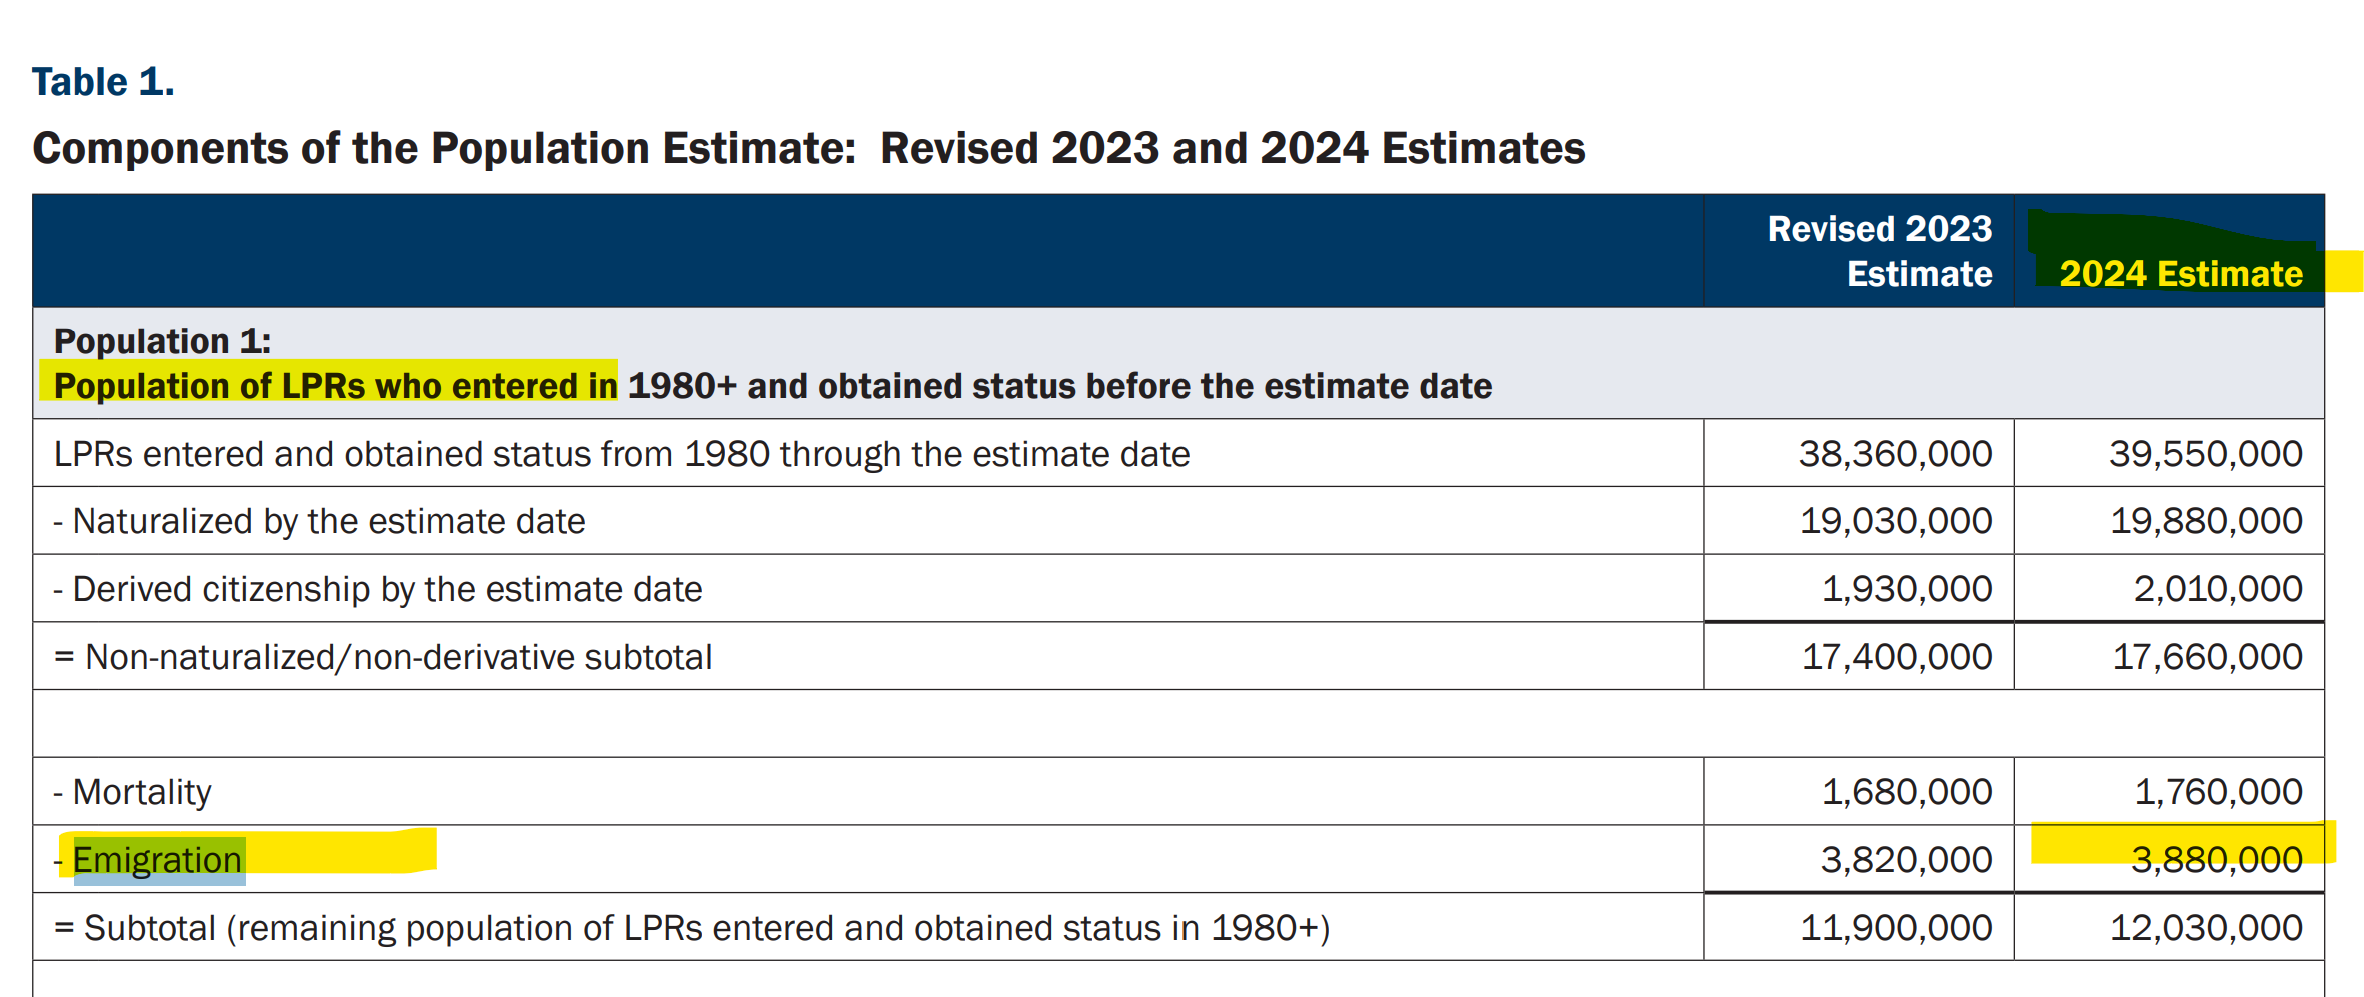
This case law has great impact on green card holders who are living principally outside of the U.S. There are 3.88 million individuals who are living outside the U.S. – per the 2024 report by the U.S. federal government. Many of them live in a treaty country. Many of these individuals might be considering their immigration law consequences (particularly after the latest announcement from the USCIS – impact these immigration consequences: U.S. Citizenship and Immigration Services Will Grant ‘Adjustment of Status’ Only in Extraordinary Circumstances (May 2026) Few have considered the tax law implications.
Most important Questions for “Green Card” Holders (“lawful permanent residents”): Part I of VI
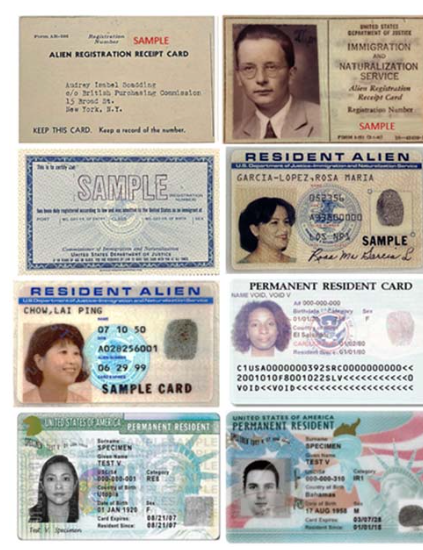
Those individuals who have green cards and live in and outside of the United States, should understand the tax and legal implications to them.
There are millions of individuals in this category. i.e., those who have “emigrated” with an “e” from the United States. There are 3.88 million of these green card holders, as of 2024 according to the U.S. federal government’s latest report. The statistics are striking – that so many individuals reside outside the U.S.
These nearly 4 million individuals who do not reside principally in the U.S. are similar to the fact pattern of Mr. Aroeste residing in Mexico City. See the case where yours truly, Patrick W. Martin, was lead counsel in that landmark case – and the analysis of the District Court in Aroeste v. United States. The government lost.
Today’s post is a series of simple and key questions for those with green cards, to help them better hone in on the legal issues and U.S. tax risks that may be applicable to them:
Am I still a U.S. taxpayer?
What does it mean to be a U.S. taxpayer, when there are technical tax terms such as “United States person” and an individual who is a “lawful permanent resident” (not defined in the immigration law)?
I have a green card but I’ve lived outside the U.S. for years — do I still have to file U.S. tax returns?
The date on my physical green card has expired – does that mean I am no longer a a “lawful permanent resident” for tax purposes?
Does it matter whether my green card is expired, taken back at the airport, or just sitting in a drawer overseas?
Is there a difference between “giving up” my green card and just letting it lapse?
Aroeste v. United States — what does it mean for me? –
Why are all of the above questions so important to me – since I previously obtained a “green card”?
Subsequent posts will address additional key questions that can have a significant legal consequence to individuals who had or have a green card and spend substantial time outside of the United States. For a preview, look at Oops.. .Did I Expatriate and Never Know It – International Tax Journal 2014
Part I of Part II: The Gold Card – “It’s like the green card, but better and more sophisticated.”
Will the “gold card” sell to ultra high net worth investors around the world who want U.S. citizenship (“USC”)? What are the tax costs of USC? * About the Author: Patrick W. Martin
President Trump again announced on April 3, aboard Air Force One his plan:
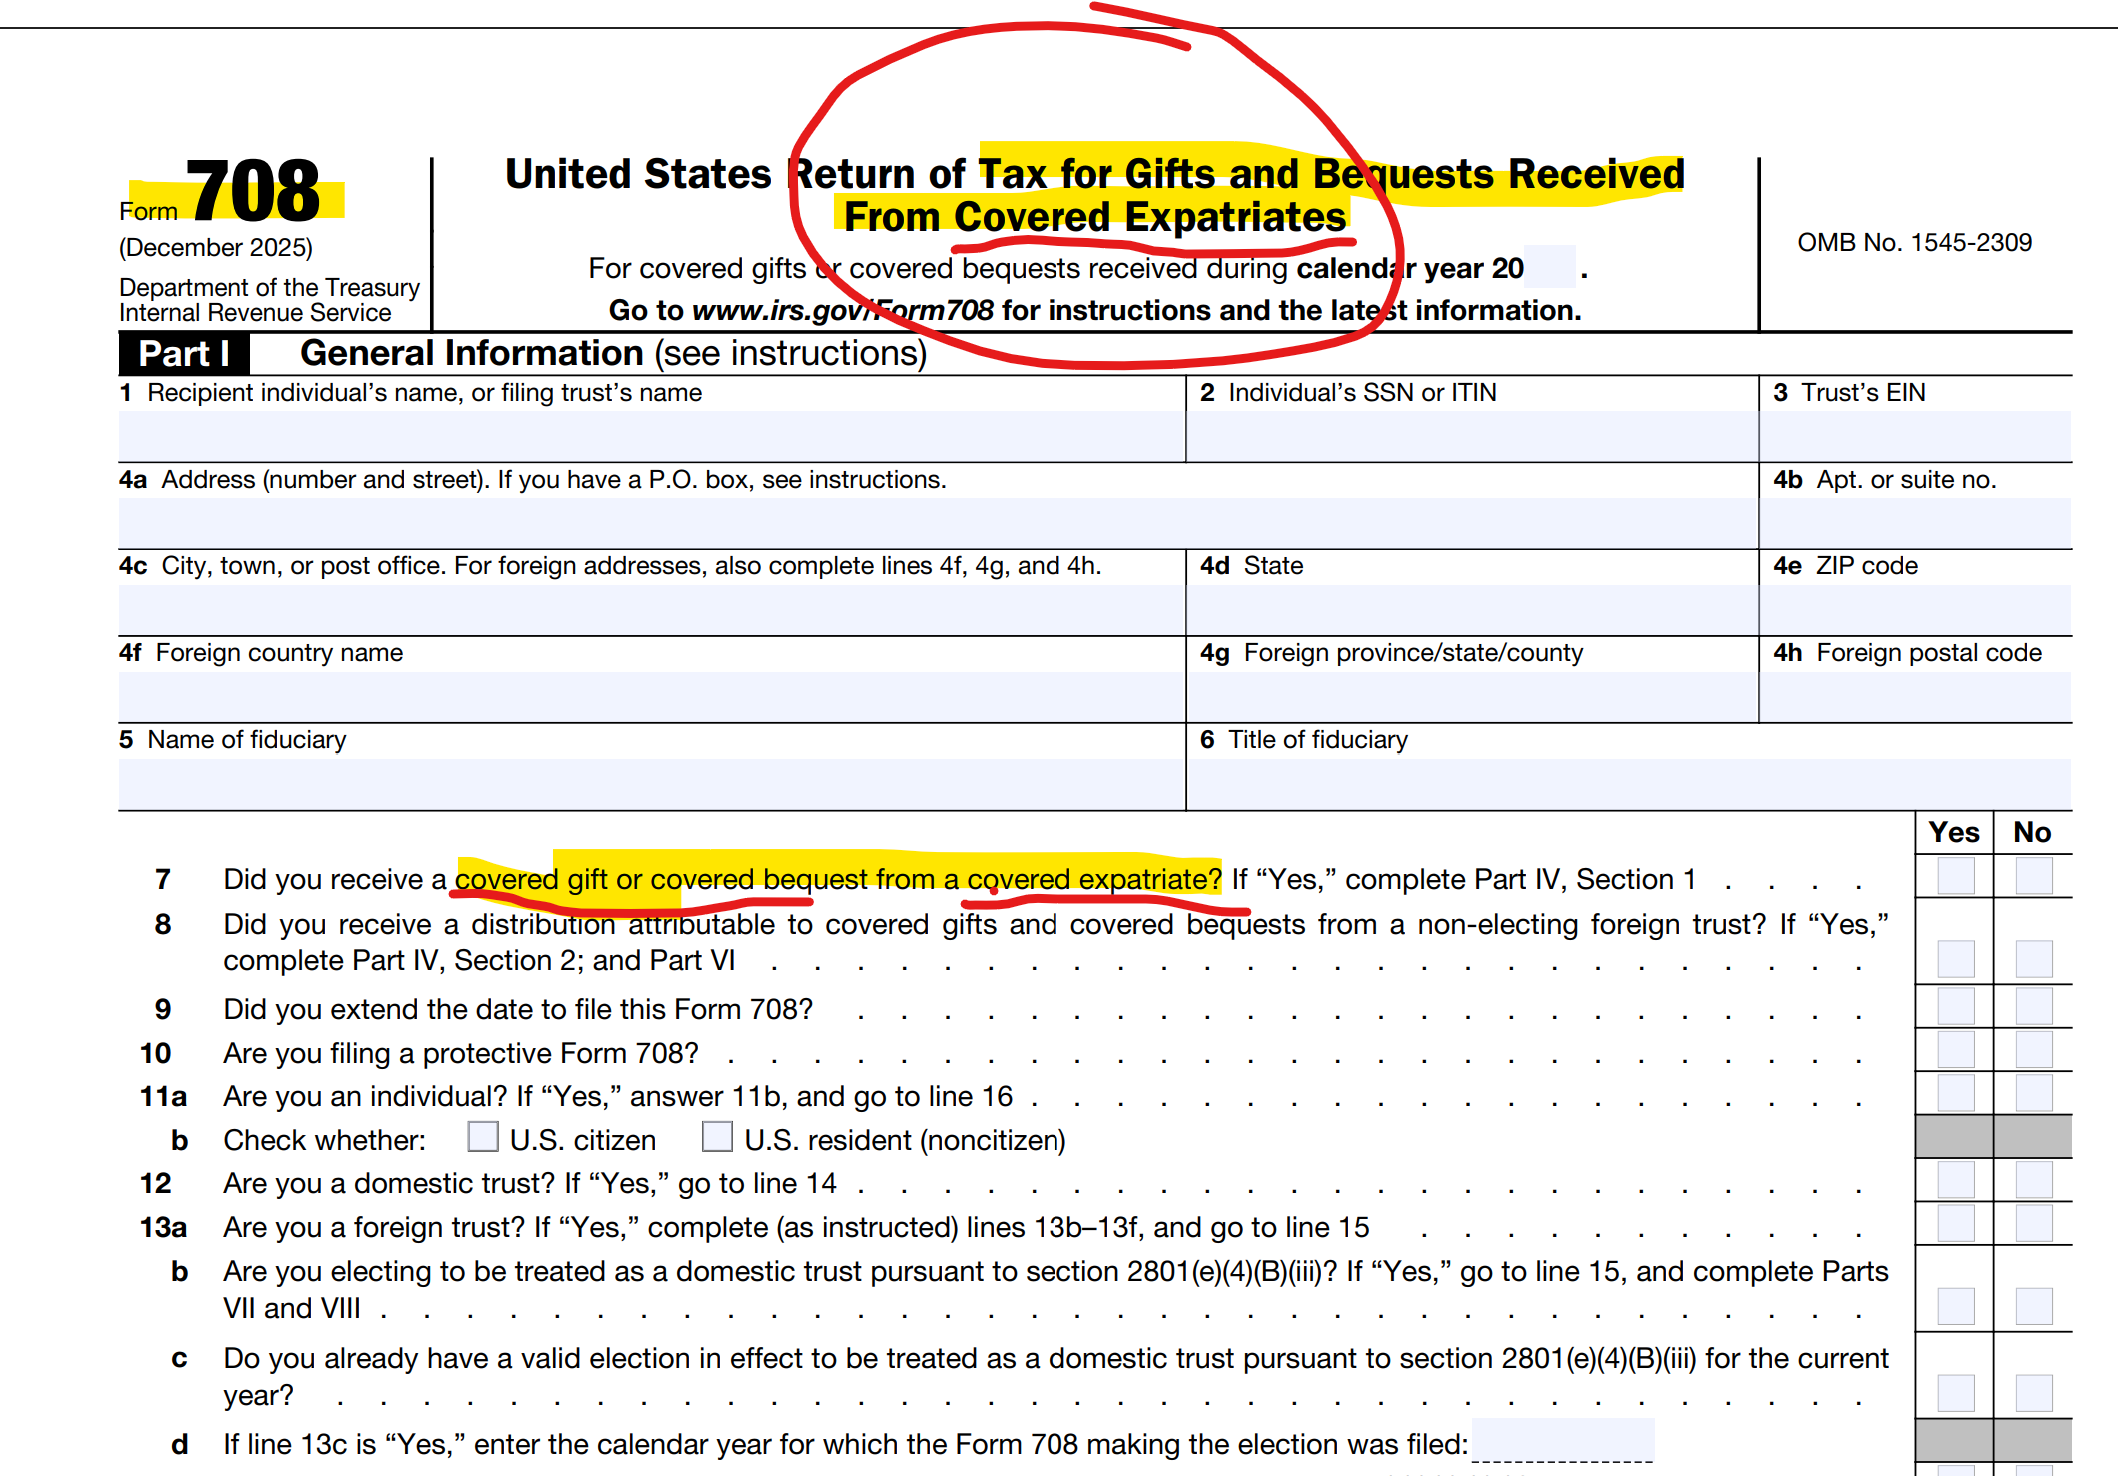
Whether the U.S. adopts a new “Gold Card” “For $5 million [that] we will allow the most successful job-creating people from all over the world to buy a path to U.S. citizenship,” is up to the U.S. government.
Congress can amend Title 8 and include a new “Gold Card” option.
Current law provides the EB-5 visa as one path towards a “green card” that ultimately can lead to U.S. citizenship through naturalization.
President Trump presented at his March 4th speech to a joint session of Congress, explaining the concept: “It’s like the green card, but better and more sophisticated. And these people will have to pay tax in our country.”
Sounds like a panacea to help the U.S. federal deficit problem? If 100,000 of these “Gold Cards” were sold for $5M each, and these funds were paid directly over to the federal government, that would raise $500 billion dollars. If 1 million were sold, that would be $5 trillion dollars to use to pay down the deficit (running annually at far greater than $1 trillion dollars since 2019).
To put that into perspective, the EB-5 visa that also leads to a “green card” that can further lead to U.S. citizenship through naturalization has an annual visa limit of about 10,000. See, USCIS’s article – (16 Aug 2024) – Annual Limit Reached in the EB-5 Unreserved Category There have been multiple years where the annual visa limit was not met. Prior to 2015, the 10,000 visa limit was never met and in several years there were less than 500 EB-5 visas issued annually.
There have been less than 150,000 EB-5 visas issued over the last 35 years since its adoption in 1990. Is it realistic to be able to “sell” even ten thousand $5M gold visas annually, when the “green EB-5 visa” costs $800,000 and has had less than 150,000 issued in nearly 35 years?
Equity Investment for EB-5 visa – $800,000 (Does NOT go to the Government)
The total required equity investment amount for an EB-5 visa in the qualifying project, is only $800,000 (if in a “TEA”). See, EB-5 Immigrant Investor Program, as published by the U.S. Citizenship and Immigration Services (USCIS). See, USCIS’s Chapter 2 – Immigrant Petition Eligibility Requirements. It used to be only $500,000 (1/10th of $5M). A TEA is a targeted employment area (“TEA”) that meets specific requirements under the law. If the capital investment is not in a TEA, the required minimal capital investment amount is $1,050,000 that increases in January 1, 2027 and each 5 years thereafter. Still about 1/5th the cost of a “gold visa”.
U.S. Estate and Gift Tax Consequences for U.S. Citizens and those with a Green Card (“Gold Card”?)
Finally, maybe the biggest impact on who wants an investor visa that leads to U.S. citizenship depends largely upon the U.S. income tax and U.S. estate and gift tax consequences. There are many tax implications. See, my case Aroeste v United States – Order Nov 2023, that was appealed to the 9th Circuit by the Office of Solicitor General (DOJ). U.S. District Court ruled in favor of green card holder.
How Many Lawful Permanent Residents does the U.S. Receive (Per Year: 1820-2022)
There is an idea that only recently has permanent resident US immigration status into the United States grown substantially. The peak years were in the early 1990s as to absolute numbers. However, the greatest number of permanent residents as a relative percentage of the population was in the early 1900s; by far. See the chart below that I created from DHS immigration statistics data.
There were more LPRs admitted, in absolute terms in 1905 (1,026,499) than in 2022 (1,018,349).
[arm_restrict_content plan=”2,” type=”show”]
In percentage terms the total number of LPRs in 1905 compared to the total population was more than four times (4X) greater than in 2022 when it was (about 3/10th of 1 percent or 0.306%; versus a total population of 333 million) . In 1905 the total population was about 84 million, with newly admitted LPRs representing 1.225 percent of the entire resident population (1.225%; is greater than 4X the 2022 relative percentage).
The “Mark to Market” Tax that did NOT Exist in 1820, 1913, 1966 (Not Until 1996)
The US tax expatriation laws now impose a “mark to market” tax on so-called “long-term residents” who become “covered expatriates.” Such a concept in the tax law never existed in the early part of the 20th century, and indeed only became law in 1996. See an earlier post, The Foreign Investors Tax Act of 1966 (“FITA”) – The Origin of US Tax Expatriation law
This so-called Mark to Market tax is based upon a legal fiction, as if the individuals sold their worldwide assets on the “expatriation date.” It applies, even though there’s no current sale of assets, no disposition, transfer, change of ownership, change of title, or other “realization” event. The term “realization” is very significant in US tax law, including as recently discussed by the United States Supreme Court. See below and Moore v. the United States (2024) .
Below is a table of LPRs who were admitted to that status, per year, over the last 200+ years starting in 1820:
Are you or any of your family members one of these millions (more than 88 million) of LPR individuals represented in the above graph over the last 200+ years?
What Questions Need to be Asked if You Live (with a “green card”) in one of the 67 Countries – with a U.S. Income Tax Treaty?
Depending upon the factual circumstances of each individual, they may be able to benefit from the international tax treaty law articulated by the U.S. Federal District Court in Aroeste v United States – Order (Nov 2023). Future posts will explore the legal relevance of some of the following questions to consider:
Has the individual filed any U.S. federal income tax returns since leaving the United States?
Was a professional tax return preparer hired or consulted about the filing of a federal income tax return (e.g., a certified public accountant, an enrolled agent, a full time tax return preparer, ta tax attorney, etc.)?
Has the individual been filing IRS Form 1040 Resident Tax Returns in the same way Mr. Aroeste was filing – based upon the advice (that turned out to be erroneous -although given in good faith) from their U.S. tax return preparer?
What steps if any have been taken to notify the U.S. federal government (irrespective of the agency) regarding their physical residency outside the United States?
This information is intended to provide general information about tax expatriation legal concepts under U.S. law to help readers better understand often very complex issues within the U.S. international tax field for citizens and lawful permanent residents. General legal information is not the same as legal advice, that is, the concrete application of law to a specific case with unique and particular facts.
Legal advice also should include strategic planning and advice to a particular case. A legal adviser should be able to assist an individual in taking important decisions and steps, related to the specific goals of the individual, while understanding the legal and tax consequences of each step. There are a range of consequences that the “U.S. tax expatriation” laws impose upon different types of transactions, transfers, reorganization of assets, etc. None of these items are discussed in this Tax-Expatriation.com This is not legal advice.
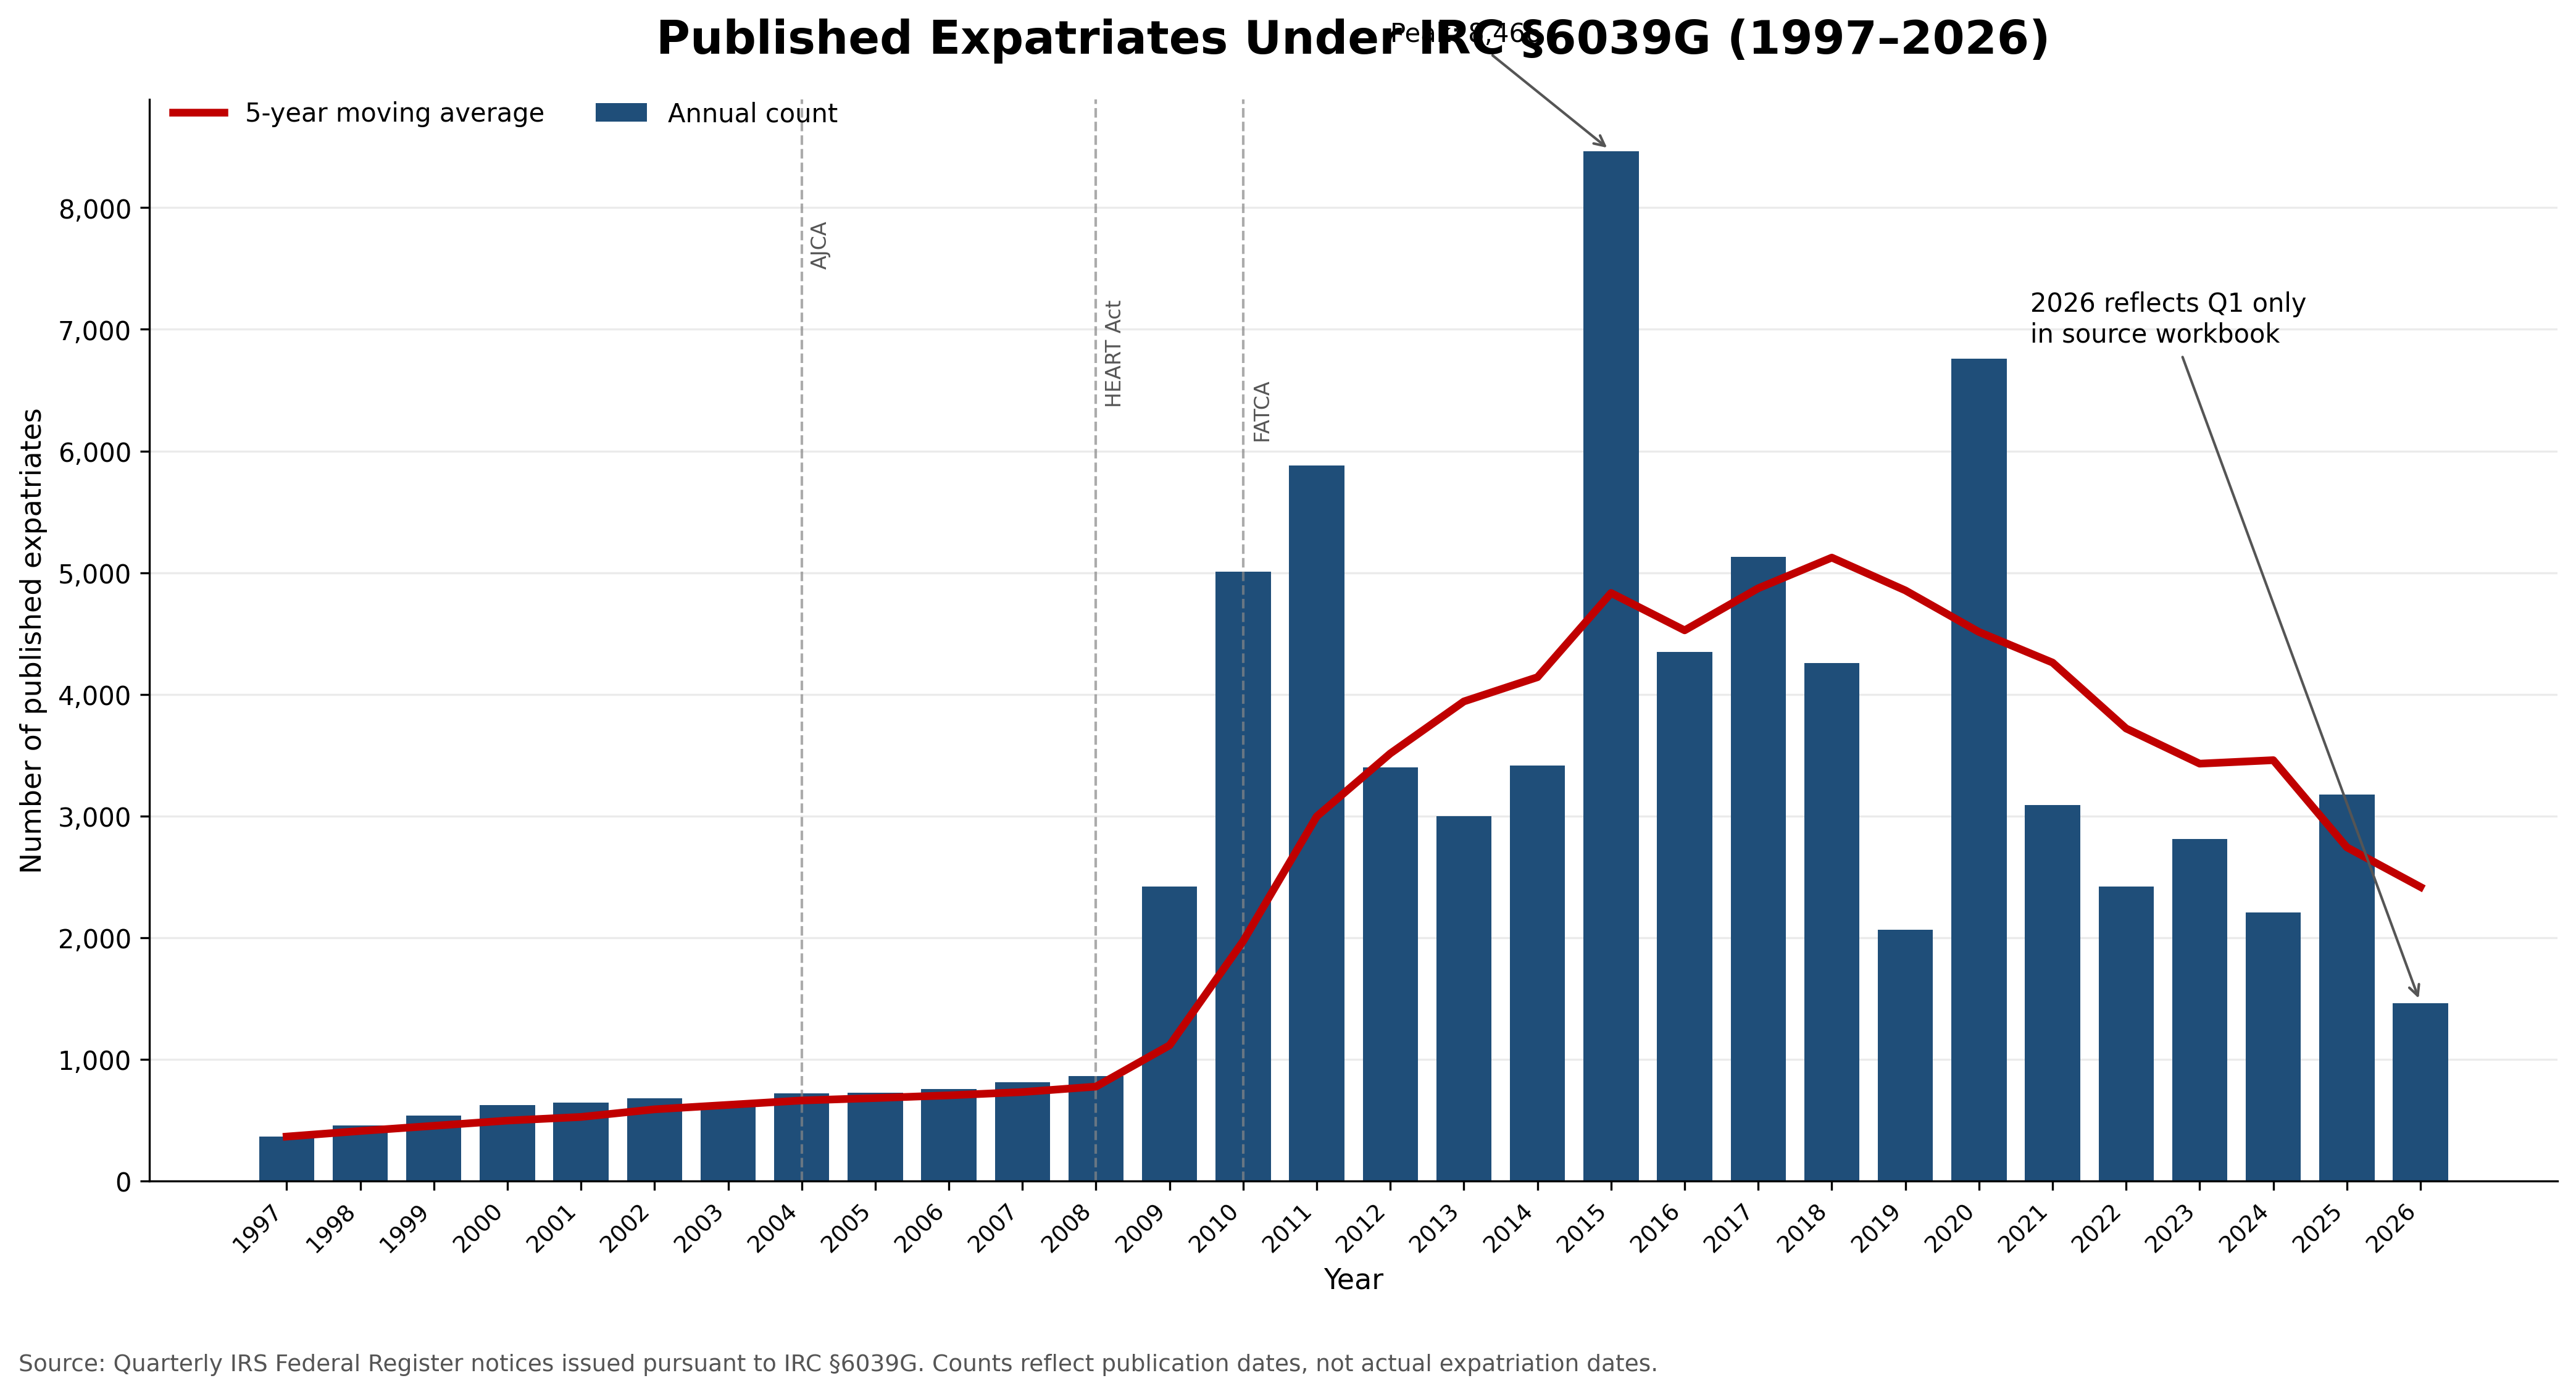
 formally renounce citizenship. The focus in the press and media is typically U.S. citizens who formally renounce. Here is my most recently compiled graph, the total number of U.S. citizens renouncing is typically in the thousands (few) each year. It has trended downward post-COVID.
 hy This Matters
 Many individuals have no idea that, under the legal principles confirmed in the federal district court case I litigated —





 ar case. A legal adviser should be able to assist an individual in taking important decisions and steps, related to the specific goals of the individual, while understanding the legal and tax consequences of each step. There are a range of consequences that the “U.S. tax expatriation” laws impose upon different types of transactions, transfers, reorganization of assets, etc. None of these items are discussed in this