International Tax Frauds are Flourishing Now with More Taxpayer Financial Information Required Under the Law
The U.S. federal law requires “U.S. persons” as that technical term is defined through complex Title 31 regulations, to provide and report extensive financial account information about the U.S. person. The report is referred to as the “FBAR” –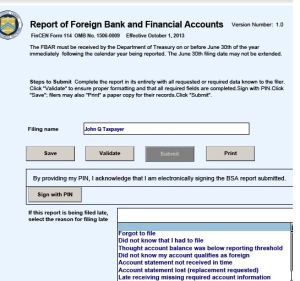 foreign bank account report. An explanation of how it works is set out here, in an earlier post, *Nuances of FBAR – Foreign Bank Account Report Filings – for USCs and LPRs living outside the U.S.
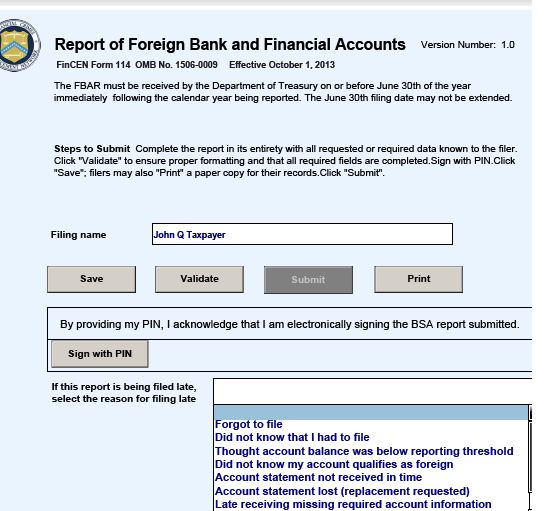
The current electronic form is referenced here:
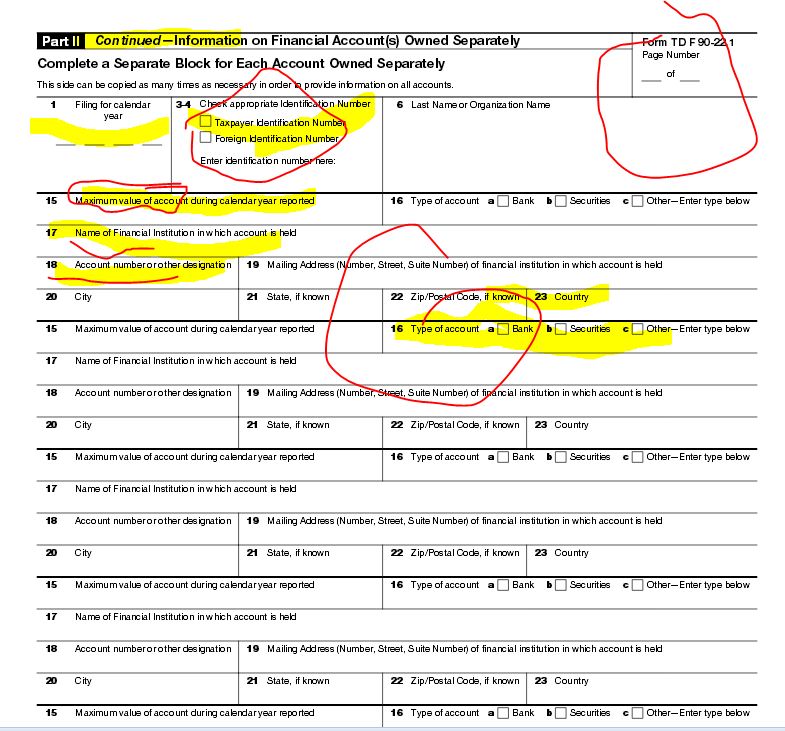
The FBAR information includes not only the taxpayer name and bank, but also the account number and the highest account balance. Plus, failing to comply with the law of the FBAR can have devastating affects to individuals, as was the case to Mr. Zwerner. See, Why the Zwerner FBAR Case is Probably a Pyrrhic Victory for the Government – for USCs and LPRs Living Outside the U.S. (Part II).
The combination of (1) extensive financial information required under the law to be provided, and (2) aggressive enforcement by the government with potentially financially devastating penalties to the individuals, has provided a toxic mix for criminals who are alarming individuals in thinking they will be prosecuted by he U.S. federal government unless the financial information is provided immediately.
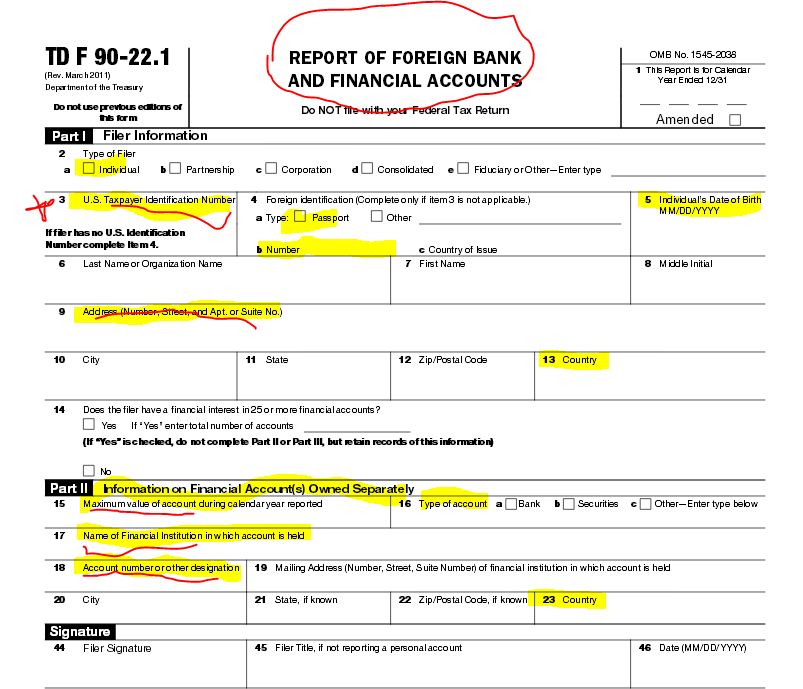
The information provided is a “crook’s dream”! Imagine if organized crime groups can access the information of an 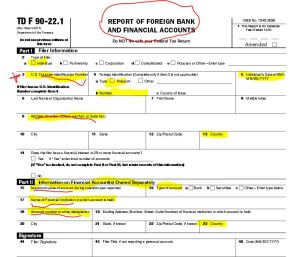 individual’s account, account number (possibly with multiple banks and multiple accounts throughout the world), their address, their identifying numbers, etc.
The old paper form was replaced last year by an electronic form (114). Specifically, filing of the FBAR form is not with the IRS, but rather with FinCEN. This form includes passport numbers, bank account addresses, account information, taxpayer identification numbers, along with extensive personal and financial information. See old form and some highlights here:
It must now be filed electronically on Form 114, Report of Foreign Bank and Financial Accounts through the BSA E-Filing System website. The electronic form supersedes TD F 90-22.1 (the FBAR form that was used in prior years).
This treasure trove of information in the wrong hands, can wreak havoc on individuals and their personal finances. Plus, there is not a legal remedy against the U.S. federal for an individual who has their financial information stolen under the guise of tax and bank finance legal compliance.
A follow-up post will show examples of recent scams received around the world., which appear very legitimate on their face. I have recently been asked by multiple persons residing overseas if the FBAR request for information is legitimate. Details to follow in a follow-on post.
Individuals need to be cautious in many ways when handling their financial and tax affairs. For instance, see, Take Caution when Completing a “Tax Organizer” Provided by Your Tax Return Preparer.
The Risks to USCs and LPRs – Filing Late U.S. Income Tax Returns via the so-called “Streamlined” process
I previously posted a note about the so-called “Streamlined” process the IRS [which are now gone and removed from the IRS website] had announced in June 2012, Why the so-called “Streamlined” Process is “Much Ado About Nothing” – Legally Speaking. I explained that legally speaking, there is no legal protection to the taxpayer provided by this administrative procedure.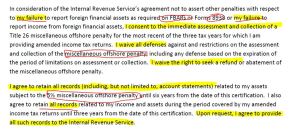
The new “streamlined” procedure from June 2014 does not provide any additional legal protection or finality. To be blunt, the government has used the FBAR as a “trap” for the taxpayer. See, Why the Zwerner FBAR Case is Probably a Pyrrhic Victory for the Government – for USCs and LPRs Living Outside the U.S. (Part II).
If the individual did not check the right box on Schedule B, Part III, therefore the government may well argue they were “willfully blind” of the requirements of filing FBARs, even if they did not know of the filing requirements. The FBAR regulations are extremely complex and I am confident few tax experts anywhere in the world could take a basic exam of what is a “financial interest in” and “signature authority over” such accounts according to these regulations and get more than about 75% (a “C” or maybe “D” grade) of these questions rights. See, Take Caution when Completing a “Tax Organizer” Provided by Your Tax Return Preparer.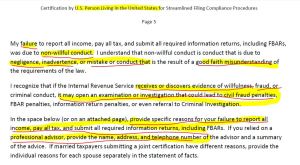
The problem with this streamlined process is there is no protection from penalties for failure to file tax returns, failure to file information returns, failure to file FBAR forms; nor from IRS audits of prior years (when the statute of limitations is still open), etc. In short, the IRS (or the Justice Department) can always fully pursue a USC or LPR who has not properly filed U.S. income tax returns, information returns on foreign assets or FBARs for prior years, as provided under the law.
In the meantime, the government will never be required to refund the so-called “5% miscellaneous offshore penalty” (which of course is not a penalty under the law in the first place), pursuant to the very terms of the Certification. The taxpayer waives ” . . . all defenses against and restrictions on the assessment and collection of the [5%] miscellaneous offshore penalty.” It is a one way street.
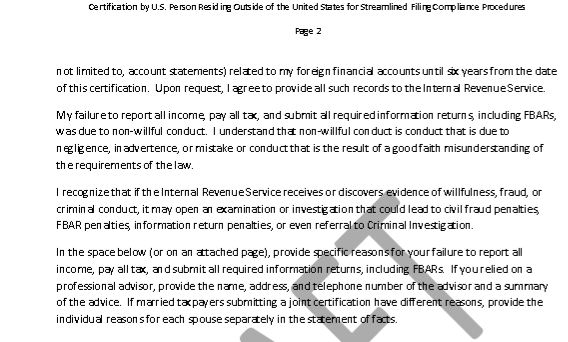
In addition, the individual is now subjecting themselves to potential greater liability in the event the government ever wants to challenge the certification made under penalties of perjury. Indeed, the certification is not drafted in the words of the taxpayer, but rather the U.S. federal government. Many practitioners have been analyzing and parsing the meaning of “negligence” and “inadvertence” and “mistake” that is a “good faith misunderstanding” of the requirements of the law. It’s entirely unclear how these terms will be interpreted by the government in any particular case. Certainly the vast majority of these cases that are entered into this system will not be challenged; if for no other reason the limited resources of the IRS.
However, there are so many ways they can be challenged against any particular taxpayer. What if a taxpayer threw away the monthly bank statements for the year 2012 regarding a foreign account? Will that be a breach of the Certification? Will all bets be off against the taxpayer? The terms of the certification seem to provide such a result.
I suspect we will see cases where the government will go after (selectively) some taxpayers who enter into the streamlined process. They cases they will select are the ones they think the taxpayer should have gone in under the OVDP. That will be the determination of the government, not the individual taxpayer; and hence can put the taxpayer in further jeopardy.
Finally, the most troubling issue of this program for U.S. residents, is they are agreeing to pay something that does not exist under the law and may have no correlation with any income taxes owing; i.e., the so-called “5% miscellaneous offshore penalty.” Why should a “good faith” taxpayer be paying any portion of their principal to the government, if they made an inadvertent mistake of what are typically very complex provisions in the tax law?
A basic example can demonstrate the injustice of this approach. Taxpayer Pierre, moves from France to the U.S. some 10 years ago. He was an accounting major in France and practiced as an accountant before becoming a business and property manager. His English is horrible and he relies upon a tax return preparer at “J&Q Blockhead Return Preparers” who only speaks English. His return preparer has never asked good questions, about if he has any non-U.S. assets, as he meets with him for 60 minutes each year after taking his W-2 and 1099 forms to the office as requested.
Pierre inherited from his non-U.S. citizen parents accounts in Switzerland and France with a value of US$3M and some real estate outside Paris worth approximately US$2.5M that generates rents monthly. His return preparer always sent his returns with the “No” boxes checked on Schedule B, Part III and never filed FBARs or IRS Form 8938. See, USCs and LPRs residing outside the U.S. – and IRS Form 8938. Pierre was told by his French tax advisers, who are very sophisticated, that the U.S. should not levy tax on his European assets; but rather he should only pay tax in France and Switzerland on these assets. Assume the taxes withheld at source in Europe are greater than the U.S. income tax that would be generated on this income; hence he can fully credit (with the U.S. foreign tax credit) the U.S. federal income tax, except about $700.
Pierre reads the news release on a French news website of the new “streamlined” program announced by the IRS in June 2014. He asks his return preparer about it – who has no idea what he is talking about.
What is Pierre to do? Why should Pierre pay approximately US$325,000 (5% of US$6.5M) to participate in this program when he owes less than US$1,000 of federal income tax?
When Pierre discusses this press release with the manager at “J&Q Blockhead Return Preparers”; the manager says all customers are given a (1) a package of documents and a pamphlet that says “Do you have any foreign assets?” on page 37, paragraph 3; and (2) a free coffee mug with “J&Q Blockhead Return Preparers” prominently displayed. The manager at “J&Q Blockhead Return Preparers” tells Pierre – “you are not going to pin this one on me!”
How is the payment of US$325,000 that is not contemplated under Title 26, a correct result under the law?
If Pierre does not go into the streamlined program and files amended tax returns, will the IRS and Justice Department try to “Zwerner” him (assess multiple year 50% willfulness penalties – arguing he was “willfully blind”)? What if they start an audit and investigation and ask the return preparers at “J&Q Blockhead Return Preparers” about the case with the response being “We tell all our customers they have to report their foreign assets and have it in writing. See our pamphlets and website.”
That is the risk Pierre will have to take; (1) comply with the law under Title 26 as amended returns are contemplated and risk the government will pursue him for 50% willfulness penalties (as the failure to file IRS Form 8938 – should be only for 3 years at $10,000 per year) or (2) be forced into a “streamlined” procedure that will make him pay a large portion of his family inheritance from Europe to the U.S. since he did not file IRS Form 8938 or FBARs.
Read the Q&A format here.
Take Caution when Completing a “Tax Organizer” Provided by Your Tax Return Preparer
Take Caution when Completing a “Tax Organizer” Provided by Your Tax Return Preparer
This admonition might sound a bit silly, considering we are talking about a “Tax Organizer”; which is often (but not always) provided by the tax return preparer to their clients simply to collect and organize information. It’s a communication between the taxpayer and the tax return preparer.
Tax Organizers come in all shapes, flavors and colors and have no real legal significance in and of themselves. They ask a range of questions and request  various information from their taxpayer clients. They are meant to help taxpayers coordinate their information to provide the better organized information to the office of the tax return preparer in finalizing and preparing the tax return.
The AICPA has a sample Tax Organizer that is 95 pages in length. Most taxpayers quickly lose patience with detailed Tax Organizers and feel they are doing the work the tax return preparer is supposed to do in the first place. Some taxpayers simply do not complete these Tax Organizers, or do so summarily, with only partial information provided.
In years past, Tax Organizers often did not ask any questions or information about foreign bank accounts or foreign financial accounts. There are still plenty of Tax Organizers that are being used, which do not expressly raise this question.
The first set of questions in the image at the beginning of the post, is from a Tax Organizer that asks a series of questions regarding foreign accounts. This becomes important due to the law of Title 31 regarding foreign accounts. Of course, for the USC and LPR residing outside the U.S., their accounts in their home country of residence are necessarily “foreign accounts” as defined under the law, even if they are in the country where the person resides (which does not sound “foreign”). See, *Nuances of FBAR – Foreign Bank Account Report Filings – for USCs and LPRs living outside the U.S.
The admonition in this post is because the government has made Tax Organizers a very big deal in cases where they have asserted the 50% civil willfulness penalty (including for multiple years in Zwerner). The government argued vociferously that since the taxpayers checked the box “No” on the Tax Organizer regarding foreign accounts, in both the Williams (very bad facts – due to admitted tax criminal conduct) and the Zwerner cases, this indicated the taxpayers had either “constructive knowledge” or were “willfully blind” as to the requirements they had under the law to file FBARs.
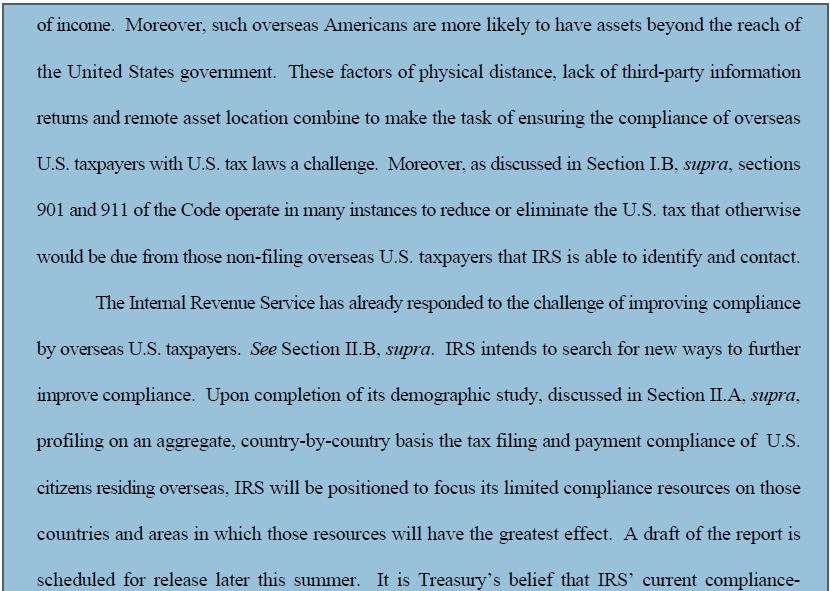
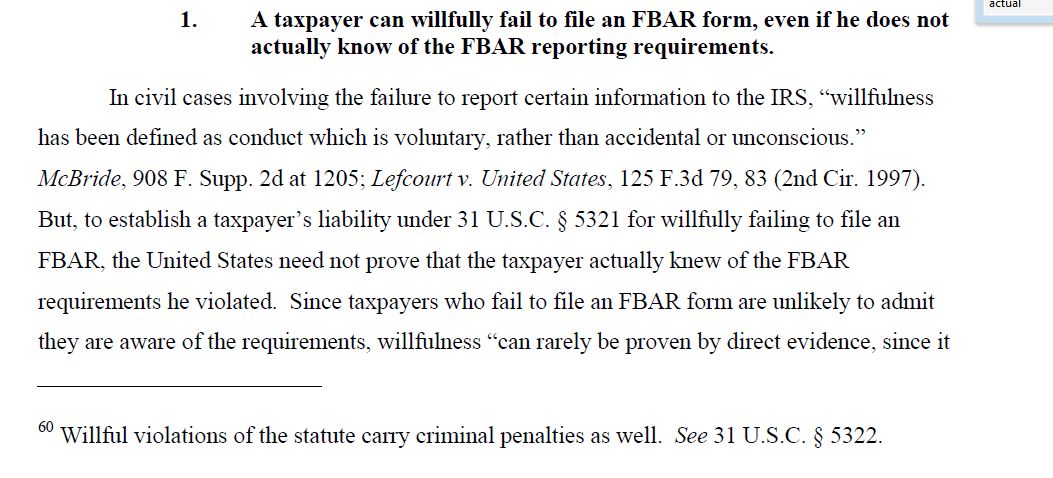
See, FBAR Penalties for USCs and LPRs Residing Overseas – Can the Taxpayer have no knowledge of the law and still be liable for the willfulness penalty? See government memorandum.
Of course, filling out an incomplete Tax Organizer with your tax return preparer is not a crime; unless the individual knows the information is false and will be provided to the IRS by their accountant. For a summary of the crime of filing a “false document”, see What could be the focal point of IRS Criminal Investigations of Former U.S. Citizens and Lawful Permanent Residents?
The “takeaway” from these two cases and how Tax Organizers are used by accountants, is that the individual is probably better off simply not using at all any Tax Organizer. This way, how it was completed (or not) cannot be construed and used against the individual as somehow showing willfulness under the FBAR penalty.
Part I: What is “Willful” and what is “Non-Willful” for USCs and LPRs Residing Overseas Who Have Not Filed U.S. Tax Returns or FBARs?
Part I: What is “Willful” and what is “Non-Willful” for USCs and LPRs Residing Overseas Who Have Not Filed U.S. Tax Returns or FBARs?
This will be one of the most important questions to understand for any USC or LPR residing outside the U.S. who has not been filing U.S. income tax returns or FBARs. See, Nuances of FBAR – Foreign Bank Account Report Filings – for USCs and LPRs living outside the U.S.
The willfulness question is important, when the USC or LPR decides what steps they need to take regarding the filing of U.S. income tax returns.
A LPR residing predominantly in a country with a US. income tax treaty (of which there are 68) may be in the best position to “clean up” their U.S. tax filing and return positions. Specifically their facts might allow them to file as a non-resident under the “tie-breaker provisions” – typically Article 4); and indeed such filings might be applicable for several prior years.
See, Countries with U.S. Income Tax Treaties & Lawful Permanent Residents (“Oops – Did I Expatriate”?) for a comprehensive list of each income tax treaty and country.
The issue of “expatriation” becomes front and center for the LPR who notifies the IRS that he or she is not a resident of the U.S, pursuant to an applicable income tax treaty and files the treaty position accordingly.
Specifically, the statutory language of IRC Section 7701(b)(6) has three tests for when the individual is no longer a LPR for federal tax purposes:
- The individual is treated as a resident of a foreign country under the provisions of a tax treaty;
- The individual does not waive the benefits of the treaty, and
- Notifies the Secretary of the commencement of such treatment.
See, LPR status can be abandoned for tax purposes (since 2008 tax law changes) by merely leaving and moving outside the U.S. in some cases.
If the LPR has had that status for the requisite number of 8 years or more, to be treated as a “long term resident”, he or she would generally be subject to the “exit tax” of Sections 877 and 877A (plus a tax to any future U.S. persons who receive gifts or inheritances from such former LPR). See, The “Hidden Tax” of Expatriation – Section 2801 and its “Forever Taint.”
If the LPR has not been “non-willful” (double negative intended) by not filing U.S. income tax returns, interesting legal questions are raised as to the consequences to the LPR.
In addition, the IRS “streamlined” procedure announced on June 18th, 2014, has specific requirements obligating the taxpayer to certify “non-willful” behavior.
Various consequences of signing these certifications under penalty of perjury, will be discussed in later posts.
Read the Q&A format here.
Webinar: “New and Improved” June 2014 IRS Offshore Voluntary Disclosure Program – Version 3.0: Including “Streamlined” Rules that are a Game Changer Thursday, July 17, 2014, 12 noon – 1:30 p.m. (PST)
The State Bar of California – Taxation Section
Webinar: “New and Improved” June 2014 IRS Offshore Voluntary Disclosure Program – Version 3.0: Including “Streamlined” Rules that are a Game Changer
Thursday, July 17, 2014, 12 noon – 1:30 p.m. (PST)
Speakers:
• Patrick W. Martin of (Procopio et al San Diego – ), who is the tax team leader of the firm’s tax practice and specializes in international tax matters, with a strong focus on international tax compliance
• Mark E. Matthews of (Caplan & Drysdale in DC – ) focuses his practice on criminal tax enforcement, broad-based civil tax compliance and was Chief of the IRS Criminal Investigation Division, the agency’s investigative and law enforcement arm.
This program offers 1.5 hours participatory MCLE credit, 1.5 legal specialization credit in the area of Taxation Law and .5 hour credit in Legal Ethics. You must register in advance in order to participate.
Just days ago (June 2014), the IRS significantly revamped the “offshore voluntary disclosure program” (“OVDP”) that has existed since 2009. The new terms of the OVDP have now completely changed the “rules of the road” about how and when taxpayers can or should participate in such program. In addition, the so-called “streamlined” process has been changed in virtually all respects.
Learn – when should a taxpayer be considering the 2014 OVDP? When should a taxpayer not participate in the 2014 OVDP? When is an individual eligible? Learn important differences under the 2014 OVDP for those who reside in the U.S. versus U.S. citizens and lawful permanent residents who reside outside the U.S.
Understand the legal ramifications for those who sign certifications under penalties of perjury.
Understand the legal risks for financial, tax and legal advisers.
These changes create numerous legal risks for the unwary and for the financial, tax and legal advisers.
Find out how you can best assist your clients and minimize their legal risks, while simultaneously complying with the labyrinth of rules imposed by the Internal Revenue Service, including modifications to their own terms. This Webinar is appropriate for tax lawyers, non-tax lawyers (such as trusts and estate lawyers and business lawyers), certified public accountants, bankers, trust officers, trustees, enrolled agents and others who have clients who have assets located outside the U.S.
A detailed highlight of the new rules of circular 230 and their application in light of these changes to the OVDP will be discussed, along with other important ethical considerations and practice pointers.
Understand the legal ramifications of U.S. taxpayers who sign certifications under penalties of perjury, specifically including those required by the OVDP. How will United States citizens and lawful permanent residents (“LPR”) who are residing outside the United States view these rules? What are the pitfalls of the revisions in this program? How does the recent jury verdict in the willfulness FBAR 50% penalty case (with 150% penalty found by the jury) in Zwerner affect decisions of taxpayers and their advisers?
This webinar is taught by experienced tax lawyers, all former employees of the IRS, including a former Chief of the IRS Criminal Investigation Division, including experts who specialize in international tax related matters and advising those with worldwide assets; multi-national families and U.S. citizens and LPRs residing outside the U.S.
Extensive written materials will be provided that analyze the law, consider various legal implications of the 2014 OVDP. The course will specifically focus on current trends and developments of the IRS and Tax Division/Justice Department and current civil and criminal cases moving forward.
Plus, understand the basics of FATCA (the Foreign Account Tax Compliance Act) now in effect for 2014 and how this affects this arena of practice and international tax compliance. Specifically understand the role of FATCA under the new IRS modifications to the OVDP and why it is more important than ever.
Finally, some key income tax concepts of residency and international information reporting requirements under Title 26 and Title 31 will be briefly analyzed in the context of the 2014 OVDP.
Moderator: Eric D. Swenson of (Procopio et al San Diego – http://www.procopio.com/attorneys/eric-d-swenson) is a tax attorney with multiple years at Chief Counsel in the IRS and handles complex tax controversy and defense cases against the IRS and State taxing authorities.
Speakers:
• Patrick W. Martin of (Procopio et al San Diego – http://www.procopio.com/attorneys/patrick-w–martin), who is the tax team leader of the firm’s tax practice and specializes in international tax matters, with a strong focus on international tax compliance
• Mark E. Matthews of (Caplan & Drysdale in DC – http://www.capdale.com/mmatthews) focuses his practice on criminal tax enforcement, broad-based civil tax compliance and was Chief of the IRS Criminal Investigation Division, the agency’s investigative and law enforcement arm.
To register, see Webinar: “New and Improved” June 2014 IRS Offshore Voluntary Disclosure Program – Version 3.0 or go to http://www.calbar.org/online-cle and select Taxation or Webinars.
U.S. Enforcement/Collection of Taxes Overseas against USCs and LPRs – Legal Limitations
Maybe its a natural response for USCs and LPRs living overseas to ask: “What is the chance I will get audited by the IRS?” Sometimes, those individuals who either have less good faith (or are simply ignorant about how U.S. tax law functions) will also ask: “How will the U.S. government ever know of my assets or income in my home country?”
A follow-up question is how does the U.S. federal government enforce tax obligations overseas? This question often comes, of course, from individuals who reside in different countries outside the U.S. and typically have most (if not all) of their assets located in their country of residence.
A USC or LPR residing in Costa Rica, for instance, might have almost all of his business assets in Costa Rica and maybe financial investment assets in nearby regions such as Panama. Similarly, a Chinese born dual national USC may have companies and business assets in both mainland China and Hong Kong. If neither of these individuals have assets in the U.S., how can the U.S. federal government enforce tax liens, levies and the like against these individuals?
These questions are getting asked more and more now that FATCA has gone into force and financial information around the world is being collected regarding USC accounts in virtually all countries and financial institutions. See, FATCA Driven – New IRS Forms W-8BEN versus W-8BEN-E versus W-9 (etc. etc.) for USCs and LPRs Overseas – It’s All About Information and More Information
An excellent layman’s term summary of FATCA can be located on HSBC’s website here.
This overseas asset and income information will eventually be delivered, pursuant to the FATCA rules, to the U.S. Internal Revenue Service (IRS – revenue authority).
Hence, the collection of information under FATCA will be extensive. This, at least in part, answers the question of: “How will they ever know of my assets or income in my home country?” Admittedly, the complete answer to this question is far more complicated, when one considers the intricacies of FATCA and its regulations and other guidance from the IRS/Treasury.
However, that is a different question, than how that financial and income information will be used by the IRS to (a) make tax assessments, (b) assess and collect foreign bank account report (FBAR) penalties (See, Section 16 of the IRM), and (c) generally enforce and collect such tax assessments and penalties against USCs and LPRs residing outside the U.S.
1. INFORMATION – The collection of asset and financial information under FATCA has a very “long arm” around the world. Indeed, the image of the Uncle Sam octopus published in the June 28, 2014 article in the The Economist entitled Taxing America’s diaspora: FATCA’s flaws captures well the idea of the reach of FATCA.
2. INFORMATION VS COLLECTION – However, enforcing tax assessments and penalties and collecting against assets located outside the U.S. is a very different legal question, without such a “long arm”; simply because the reach and jurisdiction of U.S. law is necessarily limited and regularly in conflict with local laws of different countries.
To say it another way, Uncle Sam can indeed enforce the collection of financial and asset information under FATCA, due to the economic costs and ramifications to financial institutions and their investors if they did not comply with the automatic information exchange. However, Uncle Same cannot simply enforce the collection of U.S. taxes and penalties through the worldwide financial institutional network, the same way it can in the U.S.
The U.S. has broad lien, levy and seizure powers under U.S. tax law. The IRS can simply seize assets from U.S. bank accounts without going to a judge or court for final (or jeopardy) tax assessments provided they comply with various provisions of the law. This is not a typical concept in the law for other creditors (other than the IRS) who must generally first take steps through the courts to get some type of judicial action (e.g., a court order) before simply seizing and taking assets from an individual.
The IRS’s broad lien and levy powers against assets, however, has significant limitations overseas. See the 1998 Treasury Report – Sometimes Old is as Good as New – 1998 Treasury Department Report on Citizens and LPRs, I hav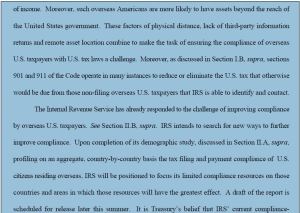 e worked with IRS Revenue Officers who specialize in international collection matters who argue and assert they can merely exercise this lien and levy power overseas against foreign financial institutions. However, this is where the power of the IRS comes to a screeching halt (or at least a major slowdown); when the collection of overseas assets is at stake.
The IRS is not without remedies to collect foreign assets, but it is not a simple process; if it can be done at all in any particular circumstance.
The IRS has no specific enforcement provisions negotiated in international treaties that will necessarily enable them to enforce and collect U.S. income taxes overseas with foreign government assistance. The cornerstone 9th Circuit case of Her Majesty held in 1979 that the Canadian tax authorities could not enforce a tax judgment against U.S. taxpayers within the U.S. –
The basic facts were these, as reported in the case:
British Columbia then served a “Notice of Intention to Enforce Payment” on the defendants in the United States, and filed a certificate of assessment in the Vancouver Registry of the Supreme Court of British Columbia. This certificate was for $195,929.50 (a penalty and interest were included), and under the laws of British Columbia its filing gave it the same effect as a judgment of the court. British Columbia then instituted the present action in the United States. It was dismissed because the court below concluded that the Oregon courts would follow the “revenue rule.” Stated simply, the revenue rule merely provides that the courts of one jurisdiction do not recognize the revenue laws of another jurisdiction.1
The U.S. 9th Circuit Court went on to say:
Although the Supreme Court has never had occasion to address the question of whether the revenue rule would prevent a foreign country from enforcing its tax judgment in the courts of the United States, the indications are strong that the Court would reach the same result as we reach in the present case. Both the majority and the dissenting opinion in Banco Nacional de Cuba v. Sabbatino, 376 U.S. 398, 84 S.Ct. 923, 11 L.Ed.2d 804 (1964), discussed the rule in a spirit which indicates a continued recognition of the revenue rule in the international sphere.10
This Majesty case specifically cited a Canadian Supreme Court case (Harden) which also applied the revenue rule in not enforcing a tax judgement in the U.S. courts for taxes against a Canadian resident:
Reciprocity would itself be a sufficient basis for denying British Columbia’s claim. The courts of British Columbia, relying upon the revenue rule, have refused to recognize the judgment of a United States court for taxes. United States v. Harden, 1963 Canada Law Reports 366 (Sup.Ct. of Canada, 1963, Affirming Court of Appeal for British Columbia).12
CONCLUSION: The revenue rule has been with us for centuries and as such has become firmly embedded in the law. There were sound reasons which supported its original adoption, and there remain sound reasons supporting its continued validity. When and if the rule is changed, it is a more proper function of the policy-making branches of our government to make such a change.
As a result of these cases and the Revenue Rule, the U.S. and Canada modified their income tax treaty to (at least in theory) allow for the international enforcement of taxes. The U.S. now has five income treaties with “mutual assistance” provisions: Canada, Sweden, France, Denmark, and the Netherlands (with a clause in the newly negotiated, but yet to go into force, Swiss treaty).
The U.S. tax and international tax world has changed dramatically since 1979 and the 9th Circuit case of Her Majesty particularly with the advent of FATCA. Nevertheless, there are serious legal limitations imposed on t he IRS in collecting assets for U.S. tax liabilities and penalties owed by USCs and LPRs residing overseas. Indeed, this is surely one of the principle reasons the IRS revised OVDP terms in June 2014 impose a 0% penalty against USCs and LPRs who participate in the so-called “streamlined process”. See, More on the New 2014 “Streamlined” Process for USCs and LPRs Residing Overseas.
The follow-on post will discuss the very limited provisions that have been recently negotiated with these five different countries and explain in more detail the limits on the U.S. federal government on the collection of taxes. It will also discuss the important differences of civil U.S. international tax enforcement/collection versus criminal tax enforcement; which are two very different beasts.
Finally, a dedicated post on the topic will discuss the steps the U.S. federal government is taking through the Department of Homeland Security and a database of information (TECS) to track and monitor people and their assets. The government describes TECS as follows: “The Treasury Enforcement Communications System (TECS) is a database maintained by the Department of Homeland Security (DHS), and it is used extensively by the law enforcement community. It contains information about individuals and businesses suspected of, or involved in, violations of federal law.”
Supreme Court’s Decision in Cook vs. Tait and Notification Requirement of Section 7701(a)(50)
The U.S. Supreme Court upheld as Constitutional the concept of citizenship based taxation in 1924 in Cook v. Tait. In that case, the U.S. citizen resided permanently and was domiciled in Mexico City with his Mexican citizen wife.
In those years, the Revenue Act of 1921 imposed a top income tax rate of 8%. The IRS made a demand against Mr. Cook to pay his tax. Mr. Cook paid it and sued for refund of the US$1,193 paid. That amount represents about  US$16,893 in 2014 inflation adjusted dollars. Neither amounts are significant in current actions taken by the IRS.
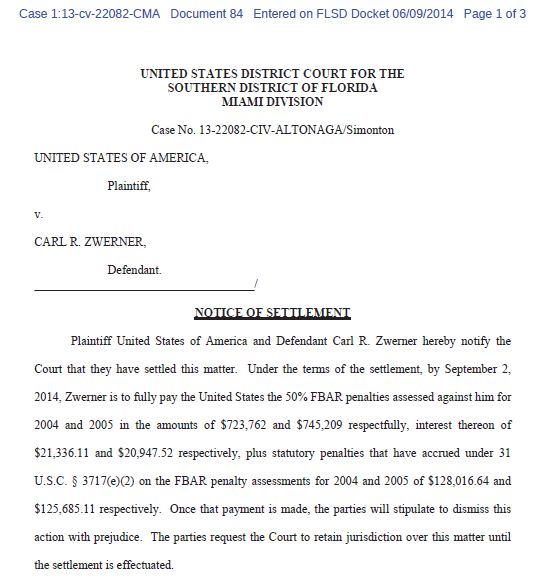
As a point of reference, Mr. Zwerner was alleged to owe US$3,630,119 (on an account with a maximum value during the years at issue of apparently no more than US$1.69M) and ultimately paid about US$ 1.75M (more than he even had in his account?) per the Notice of Settlement filed with the Court referenced here:
Even in 1922 dollars when Mr. Cook was living in Mexico City, the payment by Zwerner of about US$ 1.75M in current dollars, would represent about $123,581 in those dollars. See, Why the Zwerner FBAR Case is Probably a Pyrrhic Victory for the Government – for USCs and LPRs Living Outside the U.S. (Part II)
There was no Foreign Account Tax Compliance Act (“FATCA”) in the days of Cook in Mexico City, so it would be interesting to know how and why the audit and tax assessment collection was commenced. This was long before e-mails and internet, and there was a very different system of international travel. Communication and technology in 2014 is quite different from technology nearly 100 years ago when the first transcontinental (not transnational) telephone call was made in 1915 a few years before the tax issue arose in the case of Mr. Cook.
Now to the key point of this post. The Supreme Court in Cook vs. Tait framed the question before the Court as follows:
- The question in the case . . . as expressed by plaintiff [Mr. Cook], whether Congress has power to impose a tax upon income received by a native citizen of the United States who, at the time the income was received, was permanently resident and domiciled in the city of Mexico, the income being from real and personal property located in Mexico.
Can the United States impose worldwide taxation on U.S. citizens who permanently live overseas and who only have income from property or services outside the U.S.? Of course, the Supreme Court, said, that such a citizenship based rule was Constitutional. The rationale of the Court was explained in the opinion as follows, specific to the rights of citizenship:
- . . . the scope and extent of the sovereign power of the United States as a nation and its relations to its citizens and their relation to it.’ And that power in its scope and extent, it was decided, is based on the presumption that government by its very nature benefits the citizen and his property wherever found, and that opposition to it holds on to citizenship while it ‘belittles and destroys its advantages and blessings by denying the possession by government of an essential power required to make citizenship completely beneficial.’ In other words, the principle was declared that the government, by its very nature, benefits the citizen and his property wherever found, and therefore has the power to make the benefit complete. Or, to express it another way, the basis of the power to tax was not and cannot be made dependent upon the situs of the property in all cases, it being in or out of the United States, nor was not and cannot be made dependent upon the domicile of the citizen, that being in or out of the United States, but upon his relation as citizen to the United States and the relation of the latter to him as citizen. [emphasis added]
The Supreme Court emphasizes at several points that it is because of the benefits of citizenship and the rights conferred to the citizen of the United States, that the United States government has the Constitutional power to impose worldwide taxation.
What is the difference, if someone is NOT a U.S. citizen? How can the U.S. federal government impose worldwide taxation on property outside the U..S. when the individual is not a citizen, has no right to even enter the United States and generally has no benefits or protections afforded to a U.S. citizen? Indeed, a recent interpretation of the U.S. government in a Justice Department memo spells out the rights of certain U.S. citizens. See New York Times recent article, Court Releases Large Parts of Memo Approving Killing of American in Yemen Targeting Anwar al-Awlaki Was Legal, Justice Department Said
Back on topic, the rationale in Cook v. Tait did not extend to someone who was not a citizen. For example, the Internal Revenue in the 1920s was of course not attempting to impose taxation on Mr. Cook’s Mexican national wife who lived exclusively in Mexico.
Herein, is a most interesting problematic and possibly (maybe – probably?) unconstitutional aspect of current law under the provisions off IRC Section 7701(a)(5)(if the loss of nationality is retroactive to a date long ago in the past but the tax code/IRS is not recognizing that past date as the expatriation date.
See, Why Section 7701(a)(50) is so important for those who “relinquished” citizenship years ago (without a CLN)
If someone has lost all rights to U.S. citizenship years or decades ago, how can the U.S. federal government continue to impose worldwide income taxation for all of the intervening years?
How can the tax law impose a “Constitutional fiction” that a person continues to be “. . . treated as a United States citizen . . . ” simply because they did not file a paper notification with the U.S. federal government. See, Section 7701(a)(50) was adopted and has a very clear timing rule about when a person “. . . cease[s] to be treated as a United States citizen. . . ” It is not the same as for immigration law purposes. It’s a fiction in the tax law as to when one ““. . . cease[s] to be . . . a United States citizen. . . ”
The statute says ” . . . An individual shall not cease to be treated as a United States citizen before the date on which the individual’s citizenship is treated as relinquished under section 877A (g)(4). . .”
How can the U.S. federal government continue to impose U.S. worldwide income taxation on former U.S. citizens because of the provisions under Section 7701(a)(50) and 877A (g)(4)?
The U.S. Supreme Court in Cook vs. Tait found the U.S. citizenship based taxation system as Constitutional since ” . . . government by its very nature benefits the citizen and his property wherever found . . .” and because of “ . . . his relation as citizen to the United States and the relation of the latter to him as citizen. . . . ” [emphasis added]
A person who is not a citizen, obviously does not receive these benefits from the government as does a United States citizen.
In practice, the only body that can determine whether a law is Constitutional or not, is the U.S. Supreme Court. It’s not likely that this question will reach the Supreme Court any time soon; if ever. Meanwhile, the IRS generally has the duty to enforce the law as currently written.
More on the New 2014 “Streamlined” Process for USCs and LPRs Residing Overseas
The June 2014 changes by the IRS in its offshore voluntary disclosure (“OVD”) program are significant and worthy of discussion for USCs and LPRs residing overseas.
I will dedicate several blogs to this topic over the next few weeks. See, these posts on the topic for additional background: See, “IRS Makes Changes to Offshore Programs; Revisions Ease Burden and Help More Taxpayers Come into Compliance” – How Will These Changes Affect USCs and LPRs Living Outside the U.S.?
See, New 2014 “Streamlined” Process for USCs and LPRs Residing Overseas – The Thorny “Certification Requirement”
See,earlier post –Why the so-called “Streamlined” Process is “Much Ado About Nothing” – Legally Speaking,
This post is dedicated to some background, about the legal framework of the OVD and what the IRS calls “streamlined” filing.
First, it is worth reiterating, that the tax law, Title 26, is not the source of the terms of either the OVD or Streamlined. For some basic background of the statutory regime and Title 26 (along with Title 31, et. seq), see, Why the FBAR (late filed or never filed) is not a requirement for the Certification Requirement of Section 877(a)(2)(C) – (5 Years of Tax Compliance)
In addition, the Bank Secrecy Law, title 31, is not the source of the terms of either the OVD or Streamlined.
Rather, the Internal Revenue Service (the agency responsible for enforcing Title 26) has created its own terms and conditions as part of both the OVD and the “Streamlined” process. See,the “FAQs” that are published by the IRS: Offshore Voluntary Disclosure Program Frequently Asked Questions and Answers: Effective for OVDP Submissions Made On or After July 1, 2014
The terms of these FAQs are not law. The IRS can change them at anytime and without notice to anyone. Indeed the IRS has changed and modified them on numerous occasions since the initial OVD program in 2009.
Second, it is crucial to understand the basic framework of the law from Title 26 that all USCs living overseas are subject to; and the various consequences of the law. Plus, many LPRs living overseas are subject to Title 26 (but not all of them – depending upon a number of factors). The U.S. tax law is complex and there are numerous compliance requirements with onerous penalties that can be assessed. For instance, see, “PFICs” – What is a PFIC – and their Complications for USCs and LPRs Living Outside the U.S.
Also, see, US Citizenship Based Taxation. In addition, see, What could be the focal point of IRS Criminal Investigations of Former U.S. Citizens and Lawful Permanent Residents?
In that post, I summarize the principle criminal statutory rules in Title 26 – which are set out below:
1. Criminal Offenses under Title 26 (Federal Tax Law)
a. Tax Evasion (IRC Section 7201)
b. Filing a False Return or Other Document – Perjury (IRC Section 7206(1) )
- (i) Aiding or assisting in the perpetration of a false or fraudulent document (26 U.S.C. § 7206(2))
- (ii) Removal or concealment with intent to defraud, commonly related to untaxed liquor (26 U.S.C. § 7206(4))
- (iii) Compromises and closing agreements involving fraud or concealment (26 U.S.C. § 7206(5))
c. Failure to File Return, Supply Information, or Pay Tax – (IRC § 7203 – Misdemeanor – up to 12 months imprisonment)
d. Fraudulent Returns, Statements, or Other Documents (IRC § 7207)
e. “Structuring” Transactions to Evade Cash Reporting (IRC § 6050I)
In addition to these tax specific crimes, other key crimes commonly used by IRS CI agents in tax cases, particularly international cases, include:
2. Tax Related Criminal Offenses under Titles 18 and 31 (Not Tax Law Specific)
a. Conspiracy (Section 371 of Title 18)
- (i) Elements of the Offense
- (ii) Penalties and Statute of Limitations
b. False Statements (Title 18 U.S.C. § 1001)
- (i) Penalties and Statute of Limitations
c. Perjury
d. Mail fraud
e. Principals and those Who Aid and Abet (Title 18)
f. Accessory After the Fact
You may be asking – “If the terms and conditions of OVD and Streamlined are not the law – why should I consider either in my circumstances?”
The OVD is a bargain between the IRS/Justice Department and taxpayers. In short, if you participate by its terms, you will not (at least “should not”) be criminally prosecuted. The OVD program is in my view a program worthy of consideration for those who have committed any of the above tax and tax related crimes; and this will depend entirely upon the facts of each case. How, when and if these laws have been violated, can only be analyzed and considered for each particular case, based upon the detailed factual circumstances of each individual.
For those individuals, who have not committed any of the above tax related crimes, the OVD program is probably not a good option for such USC or LPR residing overseas. See an earlier article I published titled – The 2013 GAO Report of the IRS Offshore Voluntary Disclosure Program, International Tax Journal, CCH Wolters Kluwer, January-February 2014. PDF version here.
There is one caveat to this issue, which arises from the willfulness FBAR penalty. The government has argued (at least in one case) that multiple year 50% willfulness penalties can apply, even if the individual had no knowledge of the law – See, FBAR Penalties for USCs and LPRs Residing Overseas – Can the Taxpayer have no knowledge of the law and still be liable for the willfulness penalty? See government memorandum.
Clearly, the facts of the Zwerner case need to be considered carefully in how and why the government argued their position. It seems, maybe the biggest fact used against the taxpayer was that he had “touched the money”; i.e., drawn and spent some of the funds over the years?
Next, if there is little risk of a 50% willfulness penalty and there is no criminal liability, the so-called “Streamlined” process is an option. However, again, the terms of the “Streamlined” are not terms set forth in Title 26; they are made up by the IRS. They also do not bind the IRS. I strongly recommend reading the post, –Why the so-called “Streamlined” Process is “Much Ado About Nothing” – Legally Speaking, which provides the following about the process (before modified in its current form – which continues to be applicable today):
Does any of the above [referring to Streamlined] protect the USC residing outside the U.S. from an audit for any year a U.S. federal income tax return was not filed? The short answer is – NO!
Does any of the above statements in the IRS announcement mean that a USC residing overseas could not be subject to late payment or late filing penalties for not previously filing U.S. tax returns. The short answer is – NO!
Does any provision in the IRS announcement mean the FBAR penalties could not apply for failure to file. The short answer is – NO! See, When does the Statute of Limitations Run Against the U.S. Government Regarding FBAR Filings?
Does any of the above statements in the IRS announcement mean that a USC residing overseas can never be subject to penalties for not filing information returns regarding their non-U.S. international assets and “specified foreign financial assets”? The short answer is – NO! See, USCs and LPRs residing outside the U.S. – and IRS Form 8938
Importantly, there is nothing in the law (e.g., Title 26 or elsewhere) that would obligate any USC or LPR residing overseas to participate in either OVD or the “streamlined” process. Both have different consequences, potential benefits, and certainly legal risks.
Finally, the last option, that is actually subject to the law, i.e., Title 26, is filing tax returns through normal channels. Most all U.S. taxpayer file tax returns through this normal procedure.
As always is the case, but particularly for those who have not filed tax returns or FBARs, the facts of each particular case need to be considered, to determine the legal risks, benefits and consequences of any of these three approaches.
New 2014 “Streamlined” Process for USCs and LPRs Residing Overseas – The Thorny “Certification Requirement”
“Be careful what you wish for . . . “, so goes the saying. Yesterday’s post discusses the breaking news of the IRS announcement of revisions to how individuals who have not filed tax returns can “come into compliance”. See, “IRS Makes Changes to Offshore Programs; Revisions Ease Burden and Help More Taxpayers Come into Compliance” – How Will These Changes Affect USCs and LPRs Living Outside the U.S.?
I have argued for years that the IRS has neglected to identify the unique circumstances of USCs and LPRs residing outside the U.S.; and how the OVD programs in particular threw both resident and non-resident U.S. taxpayers into the same big bucket.
There is much to be said about the new “Streamlined” procedure just announced. Particular focus has been made for USCs and LPRs living outside the U.S., and the IRS rules specific to these individuals are set forth in – U.S. Taxpayers Residing Outside the United States.
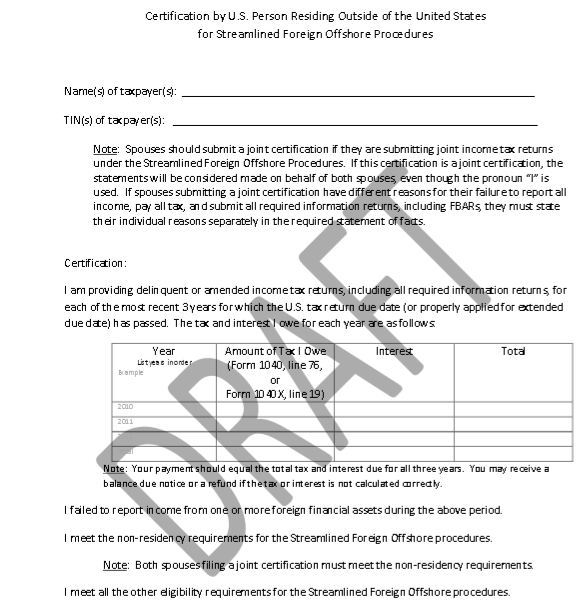
Importantly, a certification must be signed by the taxpayer, subject to the penalties of perjury under U.S. law. The sample IRS certification document, Certification by U.S. Person Residing Outside of the U.S., is set forth in part in this blog –
Signing such a Certification carries with it specific legal rights and obligations to the person who signs and certifies to its accuracy. See, a discussion of what constitutes perjury under the tax code – Filing a False Return or Other Document – Perjury (IRC Section 7206(1) ). See, What could be the focal point of IRS Criminal Investigations of Former U.S. Citizens and Lawful Permanent Residents?
The summary of the steps regarding certification are explained in the IRS website, and include most importantly the following requirement: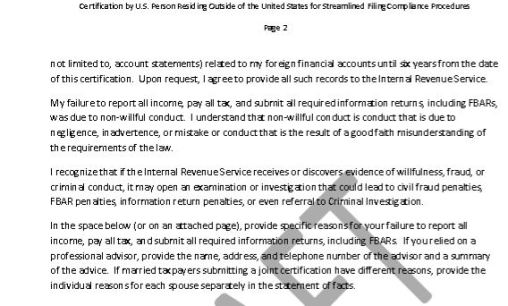
3. Complete and sign a statement on the Certification by U.S. Person Residing Outside of the U.S. certifying (1) that you are eligible for the Streamlined Foreign Offshore Procedures; (2) that all required FBARs have now been filed (see instruction 8 below); and (3) that the failure to file tax returns, report all income, pay all tax, and submit all required information returns, including FBARs, resulted from non-willful conduct.
It’s the last item that carries with it a host of legal responsibilities when certifying under penalty of perjury that ” . . . failure to file tax returns, report all income, pay all tax, and submit all required information returns, including FBARs, resulted from non-willful conduct. . . “
What is “non-willful conduct”? It is the term “willful” that is defined by the Courts, “not – non-willful”; to use the double negative. For a thoughtful discussion on what is willful, I suggest reading a precise overview by Jack Townsend. The New Streamlined Processes’ Requirement of Certifying Non-Willfulness (6/19/14)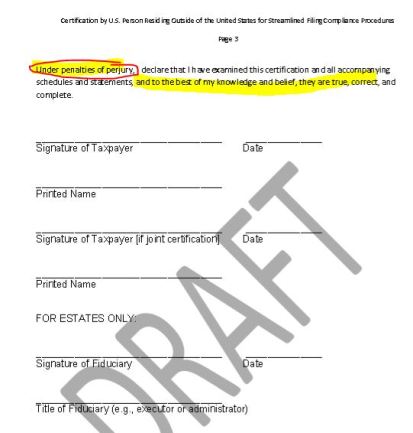
He summarizes it – As courts have noted, the word “willful” is a “chameleon” which changes in tone and color according to the Code section involved and the circumstance. See e.g., former Justice Souter’s opinion in United States v. Marshall, 2014 U.S. App. LEXIS 10415 (1st Cir. 2014), discussed in More On Willfulness (Federal Tax Crimes Blog 6/13/14), here. But, I think it is clear that, in both the income tax context and the FBAR context, willful means “voluntary intentional violation of a known legal duty.” Readers will recognize this as the Cheek standard.
Unfortunately, this Cheek standard, is not the one asserted by the government in FBAR willfulness cases. As I noted in a post just a few days ago regarding the Zwerner case (See, FBAR Penalties for USCs and LPRs Residing Overseas – Can the Taxpayer have no knowledge of the law and still be liable for the willfulness penalty? See government memorandum.)
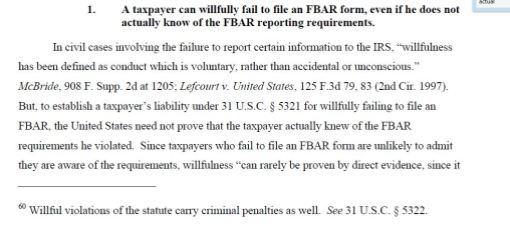
Finally, maybe the most troubling for USCs and LPRs who live outside the U.S., is the government’s assertion that an individual can be liable for the willfulness penalty, for “willfully failing to file a FBAR” – ” . . . even if the person does not actually know of the FBAR reporting requirements.” See, page 4 of the government’s motion for Summary Judgment in the Zwerner case. This is a position they have argued consistently in at least three different cases.
Why will the government not argue in those cases it selectively chooses to prosecute the following argument:
- Worldwide press about UBS, Credit-Suisse and other foreign accounts held by U.S. persons has made virtually all individuals generally aware of U.S. tax and reporting requirements.
- Any individual with a most basic level of sophistication must have known of these requirements, if they ever read a paper or the Internet (or should have known).
- FATCA news throughout the world since its passing into law in 2010, has been impossible to ignore.
- Ergo – Unless you have been living on a remote island or the rain forest, without access to the Internet, you can be liable for willful FBAR penalties, for the USC or LPR living overseas for their “willful blindness” – ” . . . even if the person does not actually know of the FBAR reporting requirements.”
Should such an argument prevail? Most private practitioners would say “no”; but the Zwerner case was illustrative of the strategies and approach taken by the government in a 150% FBAR penalty it obtained at a jury trial.
“IRS Makes Changes to Offshore Programs; Revisions Ease Burden and Help More Taxpayers Come into Compliance” – How Will These Changes Affect USCs and LPRs Living Outside the U.S.?
A few hours ago, the IRS made a significant announcement, which was expected after IRS Commissioner Koskinen’s remarks earlier in the month. See, IRS Commissioner’s Comments – Is He Listening to USCs and LPRs Living Around the World!?
The complete announcement can be read here – IR -2014-73, June 18, 2014 –
IRS Makes Changes to Offshore Programs; Revisions Ease Burden and Help More Taxpayers Come into Compliance
I will take time to reflect upon these policy changes at the IRS. More posts will follow. They appear to be significant. The consequences to taxpayers, including USCs and LPRs residing overseas, will be significant.
One of the more important parts of the announcement to USCs and LPRs living outside the U.S. is set out below:
“Through our enforcement efforts and implementation of FATCA, taxpayers are more aware of their obligations, and we believe want to come into compliance,” Koskinen said. “In this rapidly changing environment, we listened to feedback from the tax community as well as the National Taxpayer Advocate about our voluntary programs. We have made important adjustments to provide opportunities for all U.S. taxpayers to come in, including those who are not willfully hiding assets.”
Streamlined Procedures Expanded
The changes announced today make key expansions in the streamlined procedures to accommodate a wider group of U.S. taxpayers who have unreported foreign financial accounts.
The original streamlined procedures announced in 2012 were available only to non-resident, non-filers. Taxpayer submissions were subject to different degrees of review based on the amount of the tax due and the taxpayer’s response to a “risk” questionnaire.
The expanded streamlined procedures are available to a wider population of U.S. taxpayers living outside the country and, for the first time, to certain U.S. taxpayers residing in the United States. The changes include:
- Eliminating a requirement that the taxpayer have $1,500 or less of unpaid tax per year;
- Eliminating the required risk questionnaire;
- Requiring the taxpayer to certify that previous failures to comply were due to non-willful conduct.
For eligible U.S. taxpayers residing outside the United States, all penalties will be waived. For eligible U.S. taxpayers residing in the United States, the only penalty will be a miscellaneous offshore penalty equal to 5 percent of the foreign financial assets that gave rise to the tax compliance issue.
For some comments on the “streamlined” approach, see earlier post –Why the so-called “Streamlined” Process is “Much Ado About Nothing” – Legally Speaking, Posted on May 2, 2014
More posts to follow on this IRS announcement.

 foreign bank account report. An explanation of how it works is set out here, in an earlier post, *Nuances of FBAR – Foreign Bank Account Report Filings – for USCs and LPRs living outside the U.S.
 individual’s account, account number (possibly with multiple banks and multiple accounts throughout the world), their address, their identifying numbers, etc.