Part II: C’est la vie Ms. Lucienne D’Hotelle! Tax Timing Problems for Former U.S. Citizens is Nothing New – the IRS and the Courts Have Decided Similar Issues in the Past (Pre IRC Section 877A(g)(4))
This is Part II, a follow-on discussion of older U.S. case law and IRS rulings that address how and when individuals are subject to U.S. taxation before and after they assert they are no longer U.S. citizens.
I might point out that I am of the belief that we humans always like to hear the news we want to hear; and/or interpret it in the way we find most beneficial to us. Who doesn’t like good news versus bad news? Whether we (laypeople and tax lawyers alike) interpret Section 877A(g)(4) in any particular way; it is of no real consequence when it is the IRS that will enforce the law and ultimately the Department of Justice, Tax Division who will handle any such case interpreting this provision before a U.S. District Court or the Court of Federal Claims. For those who have not litigated before these Courts and seen how aggressive are the government lawyers in advocating for the government, the following discussion will hopefully be illustrative.
See, Part I: Tax Timing Problems for Former U.S. Citizens is Nothing New – the IRS and the Courts Have Decided Similar Issues in the Past (Pre IRC Section 877A(g)(4)), dated October 16, 2015.
The question is what is the correct date of “relinquishment of citizenship” as defined in the statute; IRC Section 877A(g)(4)? Many argue the law cannot be applied retroactively?
However, the specific case discussed here, did just that; applied the law retroactively to determine U.S. citizenship status of an individual and corresponding tax obligations. This was also in a time of a much simpler tax code with (i) no international information reporting requirements (e.g., IRS Forms 8938, 8858, 5471, 8865, 3520, 3520-A, 926, 8621, etc.), (ii) no Title 31 “FBAR” reporting requirements and (iii) no constant drumbeat by the IRS of international taxpayers and enforcement. See, recent announcement by IRS on Oct. 16, 2015 (one day after tax returns were required to be filed by many) Offshore Compliance Programs Generate $8 Billion; IRS Urges People to Take Advantage of Voluntary Disclosure Programs. However, for cautionary posts on the IRS OVDP and the deceptive numbers published (e.g., “$8 Billion”), see How is the offshore voluntary disclosure program really working? Not well for USCs and LPRs living overseas posted May 10, 2014 and The 2013 GAO Report of the IRS Offshore Voluntary Disclosure Program, International Tax Journal, CCH Wolters Kluwer, January-February 2014. PDF version here.
Of course, the answer to this question helps determine if and when will the individual be subject to the federal tax laws of the U.S. on their worldwide income and global assets. In the case of Ms. Lucienne D’Hotelle (an interesting 1977 appellate opinion from the firs circuit) she had spent little time in the U.S. and had sent a letter in her native language French to the U.S. Department of State, which stated “I have never considered myself to be a citizen of the United States.” This is not unlike many individuals around the world today; at least as of late – in the era of FATCA, who assert they are not a U.S. citizen because they “relinquish[ed] it by the performance of certain expatriating acts with the required “intent” to give up the US citizenship” and did not notify the U.S. federal government.
The Court nevertheless found Ms. Lucienne D’Hotelle retroactively subject to U.S. income taxation on her non-U.S. source income (up until she received a certificate of loss of nationality from the Department of State); for specific years even when the immigration law provisions of the day said she was no longer a U.S. citizen during that same retroactive period.
There have been many contemporary commentators who argue an individual does not need to (i) have, (ii) do, or (iii) receive any of the following, and yet still should be able to successfully argue they have shed themselves of U.S. citizenship and hence the obligations of U.S. taxation and reporting on their worldwide income and global assets –
(i) receive a U.S. federal government issued document (e.g., a certificate of loss of nationality “CLN” per 877A(g)(4)(C)),
(ii) receive a cancelation of a naturalized citizen’s certificate of naturalization by a U.S. court (per 877A(g)(4)(D)),
(iii) provide a signed statement of voluntary relinquishment from the individual to the U.S. Department of State (per 877A(g)(4)(B)), or
(iv) provide proof of an in person renunciation before a diplomatic or consular officer of the U.S. (per paragraph (5) of section 349(a) of the Immigration and Nationality Act (8 U.S.C. 1481(a)(5)), in accordance with 877A(g)(4)(C)).
Some older tax cases that interpreted similar concepts are worthy of consideration. They will certainly be in any brief of the attorneys for the U.S. Department of Justice, Tax Division and/or Chief Counsel lawyers for the IRS in any case where the individual challenges that none of the above items are required in their particular case to avoid U.S. taxation and reporting requirements.
The D’Hotelle case is illustrative of the efforts taken by the Department of Justice, Tax Division in collecting U.S. income tax on a naturalized citizen. You will notice they did not take a sympathetic approach to her case. Ms. Lucienne D’Hotelle was born in France in 1909 and died in 1968 in France, yet the U.S. government continued to pursue collection of U.S. income taxation on her foreign source income from the Dominican Republic, France and apparently Puerto Rico even after her death during a period of time when she used a U.S. passport. Lucienne D’Hotelle de Benitez Rexach, 558 F.2d 37 (1st Cir.1977). She, not unlike many individuals today, claimed she was not a U.S. citizen – or at least stated “I have never considered myself to be a citizen of the United States.”
Some of the particularly interesting facts relevant to Ms. D’Hotelle, a naturalized citizen, which are relevant to the question of U.S. taxation of citizens, were set forth in the appellate court’s decision as follows:
Lucienne D’Hotelle was born in France in 1909. She became Lucienne D’Hotelle de Benitez Rexach upon her marriage to Felix in San Juan, Puerto Rico in 1928. She was naturalized as a United States citizen on December 7, 1942. The couple spent some time in the Dominican Republic, where Felix engaged in harbor construction projects. Lucienne established a residence in her native France on November 10, 1946 and remained a resident until May 20, 1952. During that time s 404(b) of the Nationality Act of 1940 provided that naturalized citizens who returned to their country of birth and resided there for three years lost their American citizenship. On November 10, 1947, after Lucienne had been in France for one year, the American Embassy in Paris issued her a United States passport valid through November 9, 1949. Soon after its expiration Lucienne applied in Puerto Rico for a renewal. By this time she had resided in France for three years.
* * *
On May 20, 1952, the Vice-Consul there signed a Certificate of Loss of Nationality, citing Lucienne’s continuous residence in France as having automatically divested her of citizenship under s 404(b). Her passport . . . was confiscated, cancelled and never returned to her. The State Department approved the certificate on December 23, 1952. Lucienne made no attempt to regain her American citizenship; neither did she affirmatively renounce it.
* * *
Predictably, the United States eventually sought to tax Lucienne for her half of that income. Whether by accident or design, the government’s efforts began in earnest shortly after the Supreme Court invalidated *40 the successor statute to s 404(b). In in Schneider v. Rusk, 377 U.S. 163 (1964), the Court held that the distinction drawn by the statute between naturalized and native-born Americans was so discriminatory as to violate due process. In January 1965, about two months after this suit was filed, the State Department notified Lucienne by letter that her expatriation was void under Schneider and that the State Department considered her a citizen. Lucienne replied that she had accepted her denaturalization without protest and had thereafter considered herself not to be an American citizen.
There are other facts that make clear the government was not fond of her husband, the income that he earned and how he managed his and his wife’s assets during and after her death. The Court also discusses at length the fact that she had used a U.S. passport during the years when she alleges she was not a U.S. citizen. The Court goes on to analyze her U.S. citizenship, and the following discussions are illustrative of the ultimate tax consequences.
LUCIENNE’S CITIZENSHIP
The government contends that Lucienne was still an American citizen from her third anniversary as a French resident until the day the Certificate of Loss of Nationality was issued in Nice. This case presents a curious situation, since usually it is the individual who claims citizenship and the government which denies it. But pocketbook considerations occasionally reverse the roles. United States v. Matheson, 532 F.2d 809 (2nd Cir.), cert. denied 429 U.S. 823, 97 S.Ct. 75, 50 L.Ed.2d 85 (1976). The government’s position is that under either Schneider v. Rusk, supra, or Afroyim v. Rusk, 387 U.S. 253, 87 S.Ct. 1660, 18 L.Ed.2d 757 (1967), the statute by which Lucienne was denaturalized is unconstitutional and its prior effects should be wiped out. Afroyim held that Congress lacks the power to strip persons of citizenship merely *41 because they have voted in a foreign election. The cornerstone of the decision is the proposition that intent to relinquish citizenship is a prerequisite to expatriation.
12 Section 404(b) would have been declared unconstitutional under either Schneider or Afroyim. The statute is practically identical to its successor, which Schneider condemned as discriminatory. Section 404(b) would have been invalid under Afroyim as a congressional attempt to expatriate regardless of intent. Likewise it is clear that the determination of the Vice-Consul and the State Department in 1952 would have been upheld under then prevailing case law, even though Lucienne had manifested no intent to renounce her citizenship. Mackenzie v. Hare, 239 U.S. 299, 36 S.Ct. 106, 60 L.Ed. 297 (1915). Accord, Savorgnan v. United States, 338 U.S. 491, 70 S.Ct. 292, 94 L.Ed. 287 (1950). See also Perez v. Brownell, 356 U.S. 44, 78 S.Ct. 568, 2 L.Ed.2d 603 (1958), overruled, Afroyim v. Rusk, supra.
411 F.Supp. at 1293. However, the district court went too far in viewing the equities as between Lucienne and the government in strict isolation from broad policy considerations which argue for a generally retrospective application of Afroyim and Schneider to the entire class of persons invalidly expatriated. Cf. Linkletter v. Walker, supra. The rights stemming from American citizenship are so important that, absent special circumstances, they must be recognized even for years past. Unless held to have been citizens without interruption, persons wrongfully expatriated as well as their offspring might be permanently and unreasonably barred from important benefits. Application of Afroyim or Schneider is generally appropriate.* * *
During the interval from late 1949 to mid-1952, Lucienne was unaware that she had been automatically denaturalized.
* * *
Fairness dictates that the United States recover income taxes for the period November 10, 1949 to May 20, 1952. Lucienne was privileged to travel on a United States passport; she received the protection of its government.
_
It’s quite interesting that the Court uses and focuses on fairness as to the U.S. government, more than a discussion of “fairness” to the individual. The use of the passport seems to be an integral fact. Here, the Court determined she was retroactively a U.S. citizen and hence subject to taxation on her worldwide income during those crucial periods (1949 through 1952) even though (1) the U.S. Department of State said she was not a U.S. citizen during that time, and (2) she stated “I have never considered myself to be a citizen of the United States.”
_
101112 Although the government has not appealed the decision with respect to taxes from mid-1952 through 1958, the district court was presented with the issue. We wish to explain why the government should be allowed to collect taxes for the two and one-half year interval but not for the subsequent period. The letter from Lucienne to the Department of State official in 1965, which appears in English translation in the record, states that after the Certificate of Loss of Nationality, “I have never considered myself to be a citizen of the United States.” We think that in this case this letter can be construed as an acceptance and voluntary relinquishment of citizenship. We also find that in this particular case estoppel would have been proper against the United States. Although estoppel is rarely a proper defense against the government, there are instances where it would be unconscionable to allow the government to reverse an earlier position. Schuster v. Commissioner of Internal Revenue, 312 F.2d 311, 317 (9th Cir. 1962). This is one of those instances. Lucienne cannot be dunned for taxes to support the United States government during the years in which she was denied its protection. In Peignand v. Immigration and Naturalization Service, 440 F.2d 757 (1st Cir. 1971), this court refused to decide whether estoppel could apply against the government. A decision on the question was unnecessary, since the petitioner had not been led to take a course of action he would not otherwise have taken. Id. at 761. Here, Lucienne severed her ties to this country at the direction of the State Department. The right hand will not be permitted to demand payment for something which the left hand has taken away. However, until her citizenship was snatched from her, Lucienne should have expected to honor her 1952 declaration that she was a taxpayer.
_
Of particular note, the Court highlighted that the Department of State (one hand) cannot take away citizenship, the individual’s passport and issue a certificate of loss of nationality (“CLN”), and the IRS (on the other hand) impose taxation for the time period after the CNL was issued.
–
One point of emphasis by the Court was how U.S. citizenship rights are a highly protected right; as articulated by the U.S. Supreme Court. That high protection granted, serves to aid those individuals who defend against a government arguing they somehow ceased to be a U.S. citizen. Of course, for those trying to escape U.S. taxation, the result is not a desired one “. . . a curious situation, since usually it is the individual who claims citizenship and the government which denies it. . . “
–
C’est la vie Ms. Lucienne D’Hotelle!
U.S. District Court Flatly Denies Claims of Injury under FATCA and Title 31-FBAR Reporting Requirements: Upholds FATCA, IGAs and the FBAR Requirements to Encourage Tax Compliance and “Combat Tax Evasion”
There has been a case floating around since a complaint was filed this summer by Senator Rand Paul (current Presidential candidate) and various other current and former U.S. citizens including a Mr. Kisch who is resident in Toronto, Canada and a Mr. Crawford who lives in Albania; along with other individuals. Crawford v. United States Dep’t of the Treasury, 2015 U.S. Dist. The complaint asked for declaratory and injunctive relief.
The District Court granted neither and dismissed the case in favor of the government in a bold fashion upholding FATCA and FBAR/Title 31 reporting and information requirements. Importantly, the Court concluded by saying ” . . . The FATCA statute, the IGAs, and the FBAR requirements encourage compliance with tax laws, combat tax evasion, and deter the use of foreign accounts to engage in criminal activity. A preliminary injunction would harm these efforts and intrude upon the province of Congress and the President to determine how best to achieve these policy goals.”
See a prior post regarding how FATCA affects United States citizens (USCs) and lawful permanent residents (LPRs) residing outside the U.S.; as was the case of many of the complainants in the case, Part 1- Unintended Consequences of FATCA – for USCs and LPRs Living Outside the U.S., posted August 13, 2014.
Also, the tax publication/resource, Tax Analysts summarized the original complaint (which can be read in its entirety here) as follows:
The FATCA suit makes the following claims:
- the IGAs are unconstitutional sole executive agreements because they exceed the scope of the president’s independent constitutional powers, and because they override FATCA;
- the heightened reporting requirements for foreign financial accounts deny U.S. citizens living abroad the equal protection of the laws;
- the FATCA FFI penalty, passthrough penalty, and willfulness penalty are all unconstitutional under the excessive fines clause;
- FATCA’s information reporting requirements are unconstitutional under the Fourth Amendment; and
- the IGAs’ information reporting requirements are also unconstitutional under the Fourth Amendment.
See, complete Tax Note’s article of July 15, 2015: Sen. Paul Files Lawsuit Challenging FATCA, by William R. Davis and Andrew Velarde.
Not unsurprisingly, the District Court ruled in favor of the government and dismissed the majority of the claims by a finding that the parties lacked standing to bring the suit and that ” . . . The FATCA statute, the IGAs, and the FBAR requirements encourage compliance with tax laws . . .”
Some highlights of the Court’s opinion [with my emphasis added] are set out below:
* * *
- Background
A. FATCA Statute and Regulations
Congress passed the Foreign Accounts Tax Compliance Act (FATCA) in 2010 to improve compliance with tax laws by U.S. taxpayers holding foreign accounts. FATCA accomplishes this through two forms of reporting: (1) by foreign financial institutions (FFIs) about financial accounts held by U.S. taxpayers or foreign entities in which U.S. taxpayers hold a substantial ownership interest, 26 U.S.C. § 1471; and, (2) by U.S. taxpayers about their interests in certain foreign financial accounts and offshore assets. 26 U.S.C. § 6038D.
- FATCA
President Obama signed FATCA into law on March 18, 2010. Senator Carl Levin, a co-sponsor of the FATCA legislation, declared that “offshore tax abuses [targeted by FATCA] cost the federal treasury an estimated $100 billion in lost tax revenues annually” 156 Cong. Rec. 5 S1745-01 (2010). FATCA became law as the IRS began its Offshore Voluntary Disclosure Program (OVDP), which since 2009 has allowed U.S. taxpayers with undisclosed overseas assets to disclose them and pay reduced penalties. By 2014, the OVDP collected $6.5 billion through voluntary disclosures from 45,000 participants. “IRS Makes Changes to Offshore Programs; Revisions Ease Burden and Help More Taxpayers Come into Compliance,” http://www.irs.gov/uac/Newsroom/IRS-Makes-Changes-to-Offshore-Programs;-Revisions-Ease-Burden-and-Help-More-Taxpayers-Come-into-Compliance (last visited Sept. 15, 2015). The success of the voluntary program has likely been enhanced by the existence of FATCA.
* * *
C. Report of Foreign Bank and Financial Account
The third body of law at issue in this case pertains to the Report of Foreign Bank and Financial Account (FBAR) requirements. U.S. persons who hold a financial account in a foreign country that exceeds $10,000 in aggregate value must file an FBAR with the Treasury Department reporting the account. See 31 U.S.C. § 5314; 31 C.F.R. § 1010.350; 31 C.F.R. § 1010.306(c). The current FBAR form is FinCEN Form 114. The form has been due by June 30 of each year regarding accounts held during the previous calendar year. § 1010.306(c). Beginning with the 2016 tax year, the due date of the form will be April 15. Pub. L. No. 114-41, § 2006(b)(11). A person who fails to file a required FBAR may be assessed a civil monetary penalty. 31 U.S.C. § 5321(a)(5)(A). The amount of the penalty is capped at $10,000 unless the failure was willful. See 5321(a)(5)(B)(i), (C). A willful failure to file increases the maximum penalty to $100,000 or half the value in the account at the time of the violation, whichever is greater. § 5321(a)(5)(C). In either case, whether to impose the penalty and the amount of the penalty are committed to the Secretary’s discretion. See § 5321(a)(5)(A) (“The Secretary of the Treasury may impose a civil money penalty[.]”) & § 5321(a)(5)(B) (“[T]he amount of any civil penalty . . . shall not exceed” the statutory ceiling). Plaintiffs seek to enjoin enforcement of the willful FBAR penalty under § 5321(a)(5). Prayer for Relief, part Q. They also ask for an injunction against “the FBAR account-balance reporting requirement” of FinCen Form 114. Prayer for Relief, part W.
The Government asserts that the information in the FBAR assists law enforcement and the IRS in identifying unreported taxable income of U.S. taxpayers that is held in foreign accounts as well as investigating money laundering and terrorism.
* * *
Mark Crawford decries his bank’s policy against taking U.S. citizens as clients and claims the denial of his application for a brokerage account may have “impacted Mark financially,” ¶ 21, any such harm is not fairly traceable to an action by Defendants, which are not responsible for decisions that foreign banks make about whom to accept as clients. Crawford cannot establish standing indirectly when third parties are the causes of his alleged injuries. See Shearson, 725 F.3d at 592. Moreover, his discomfort with complying with the disclosures required by FATCA, see ¶23, does not establish the concrete, particularized harm that confers standing to sue. See, e.g., Lujan, 504 U.S. at 561 (requiring “concrete and particularized” and “actual or imminent” injury). Even if Crawford fears “unconstitutionally excessive fines imposed by 31 U.S.C. § 5321 if he willfully fails to file an FBAR,” ¶ 24, there is no allegation that he failed to file any FBAR that may have been required, much less that the Government has assessed an “excessive” FBAR penalty against him. Any harm that may come his way from imagined future events is speculative and cannot form the foundation for his lawsuit.
* * *
None of the allegations states that Kuettel is presently being harmed by FATCA or the Swiss IGA, and neither FATCA nor the IGA apply to him as a non-U.S. citizen. See ¶¶ 51-58. His assertion of past harm because he was “mostly unsuccessful” in refinancing his mortgage due to FATCA does not convey standing. If that was a harm, it was due to actions of third-party foreign banks not those of Defendants. Regardless, having now renounced his American citizenship and obtained refinancing on terms he found acceptable, any past harm is not redressable here. See Adarand Constructors, Inc. v. Pena, 515 U.S. 200, 210-11 (1995) (“[T]he fact of past injury . . . does nothing to establish a real and immediate threat that he would again suffer similar injury in the future.” (quotation omitted)). This leaves Kuettel’s claims concerning the FBAR requirement, in Counts 3 and 6, for which the Government concedes Kuettel has standing. Response, ECF 16, at 15, PAGEID 216.
* * *
Donna-Lane Nelson is a citizen of Switzerland who has also renounced her U.S. citizenship. ¶ 59. She alleges that her Swiss bank “notified her that she would not be able to open a new account if she ever closed her existing one because she was an American. Fearing that she would eventually not be able to bank in the country where she lived, she decided to relinquish her U.S. citizenship.” ¶ 65. After she renounced, a Swiss bank “offered investment opportunities that were not available to her as an American.” Id. She “resents having to provide” “explanations” to Swiss banks that have requested information on her past U.S. citizenship and payments to her daughter, who lives in the United States, and she sees “threats implied by these requests which appear to be prompted by FATCA.” ¶ 68. Like other Plaintiffs, Nelson does not want to disclose financial information to the Government, and she fears willful FBAR penalties, even though no such penalty has been imposed or threatened against her. ¶¶ 69, 70. Unlike the preceding Plaintiffs, however, she adds that she fears the 30% withholding tax may be imposed against her “if her business partner,” who is now her husband, and with whom she has joint accounts, “opts to become a recalcitrant account holder.” ¶
* * *
L. Marc Zell states that he is a practicing attorney and a citizen of both the United States and Israel who lives in Israel. He alleges that: (1) he and his firm have been required by Israeli banking institutions to complete IRS withholding forms for individuals whose funds his firm holds in trust, regardless of whether the forms are legally required, causing certain clients to leave his firm, ¶¶ 79 & 81; (2) Israeli banks have required his firm to close accounts, refused to open others, and requested conduct contrary to banking regulations, ¶¶ 79-80; and, (3) the compelled disclosure of his fiduciary relationship with clients impinges on the attorney-client relationship, ¶ 82. On request of clients, who claim their rights are violated by FATCA, Zell “has decided not to comply with the FATCA disclosure requirements whenever that alternative exists.” ¶ 83. He fears that the FATCA 30% withholding tax on pass-through payments to recalcitrant account holders could be imposed due to his refusal to provide identifying information about a client to an Israeli bank. ¶ He also has refused to provide information to his own bank and “fears that he will be classified as a recalcitrant account holder,” ¶ 85. Like the other Plaintiffs, he does not want his financial information disclosed, ¶ 86, and fears an FBAR penalty if the IRS determines that he willfully failed to file an FBAR, ¶ 87.
The majority of Zell’s allegations concern conduct of Israeli banks and his belief that the actions have been unfair to him or his clients. But conduct of third parties (even if related to the banks’ compliance with FATCA) does not confer standing to bring suit against Defendants. See, e.g., Ammex Inc. v. United States, 367 F.3d 530, 533 (6th Cir. 2004). Nor may Zell seek redress on behalf of third parties who have allegedly suffered harm, including unidentified clients. See Warth v. Seldin, 422 U.S. 490, 499 (1975). The third parties who have allegedly suffered harm are not plaintiffs, thus, alleged harm to them does not provide a basis for Zell to maintain this suit. The contention that disclosure of the identity of clients for whom Zell holds funds in trust violates the attorney-client privilege is also without merit. He gives no example of harm that has occurred or how he was harmed by disclosure of clients’ identities. He cannot raise the attorney-client privilege on his clients’ behalf, nor is the fact of representation privileged. See In re Special Sept. 1978 Grand Jury (II), 640 F.2d 49, 62 (7th Cir. 1980) (“[A]ttorney-client privilege belongs to the client alone[.]”); United States v. Robinson, 121 F.3d 971, 976 (5th Cir. 1997) (“The fact of representation . . . is generally not within the privilege.”). It is the fiduciary relationship, not the attorney-client relationship, that is the basis for the reporting requirement.
* * *
“We begin, of course, with the presumption that the challenged statute”—FATCA—“is valid. Its wisdom is not the concern of the courts; if a challenged action does not violate the Constitution, it must be sustained[.]” INS v. Chadha, 426 U.S. 919, 944 (1983); see also National Federation of Independent Business v. Sebelius 132 S. Ct. 2566, 2594 (2012) (“‘[E]very reasonable construction must be resorted to, in order to save a statute from unconstitutionality.’” (quoting Hooper v. California, 155 U.S. 648, 657 (1895))).
* * *
Plaintiffs decry that U.S. citizens living in foreign countries are in this manner treated differently than U.S. citizens living in the United States. According to Plaintiffs, the federal government has no legitimate interest in knowing the amount of any income, gain, loss, deduction, or credit recognized on a foreign account, whether a foreign account was opened or closed during the year, or the balance of a foreign account.
Plaintiffs contend that the “heightened reporting requirements” imposed by FATCA, the FBAR information-reporting requirements, and the Canadian, Swiss, Czech, and Israeli IGAs, violate the Fifth Amendment rights of “U.S. citizens living in a foreign country” and should be enjoined. See Complaint ¶¶ 124-130
* * *
Plaintiffs’ equal protection claims fail because the statutes, regulations, and executive agreements that they challenge simply do not make the classification they assert. None of the challenged provisions single out U.S. citizens living abroad. Instead, all Americans with specified foreign bank accounts or assets are subject to reporting requirements, no matter where they happen to live. The provisions Plaintiffs contend discriminate against “U.S. citizens living abroad” actually apply to all U.S. taxpayers, no matter their residence.
* * *
The distinction that the regulations do make is rationally related to a legitimate government interest. The U.S. tax system is based in large part on voluntary compliance: taxpayers are expected to disclose their sources of income annually on their federal tax returns. The information reporting required by FATCA is intended to address the use of offshore accounts to facilitate tax evasion, and to strengthen the integrity of the voluntary compliance system by placing U.S. taxpayers that have access to offshore investment opportunities in an equal position with U.S. taxpayers that invest within the United States. Third party information reporting is an important tool used by the IRS to close the tax gap between taxes due and taxes paid. The knowledge that financial institutions will also be disclosing information about an account encourages individuals to properly disclose their income on their tax returns. See Leandra Lederman, Statutory Speed Bumps: The Roles Third Parties Play in Tax Compliance, 60 STAN. L. REV. 695, 711 (2007).
Unlike most countries, U.S. taxpayers are subject to tax on their worldwide income, and their investments have become increasingly global in scope. Absent the FATCA reporting by FFIs, some U.S. taxpayers may attempt to evade U.S. tax by hiding money in offshore accounts where, prior to FATCA, they were not subject to automatic reporting to the IRS by FFIs. The information required to be reported, including payments made or credited to the account and the balance or value of the account is to assist the IRS in determining previously unreported income and the value of such information is based on experience from the DOJ prosecution of offshore tax evasion. See Senate Permanent Subcommittee on Investigations bipartisan report on “Offshore Tax Evasion: The Effort to Collect Unpaid Taxes on Billions in Hidden Offshore Accounts,” February 26, 2014; see also Cal. Bankers Ass’n v. Shultz, 416 U.S. 21, 29 (1974) (“when law enforcement personnel are confronted with the secret foreign bank account or the secret foreign financial institution they are placed in an impossible situation…they must subject themselves to time consuming and often times fruitless foreign legal process.”).
The FBAR reporting requirements, likewise, have a rational basis. As the Supreme Court noted in California Bankers, when Congress enacted the Bank Secrecy Act (which provides the statutory basis for the FBAR), it “recognized that the use of financial institutions, both domestic and foreign, in furtherance of activities designed to evade the regulatory mechanism of the United States, had markedly increased.” Id. at 38. The Government has a legitimate interest in collecting information about foreign accounts, including account balances held by U.S. citizens, for the same reason that it requires reporting of information on U.S.-based accounts. The information assists law enforcement and the IRS, among other things, in identifying unreported taxable income of U.S. taxpayers that is held in foreign accounts. Without FBAR reporting, the Government’s efforts to track financial crime and tax evasion would be hampered.
* * *
In Count Six, Plaintiffs contend that the FBAR “Willfullness Penalty” is unconstitutional under the Excessive Fines Clause. Plaintiffs decry that 26 U.S.C. § 5321 imposes a penalty of up to $100,000 or 50% of the balance of the account at the time of the violation, whichever is greater, for failures to file an FBAR as required by 26 U.S.C. § 5314 (the FBAR “Willfulness Penalty”). 31 U.S.C. § 5321(b)(5)(C)(i). 31
Plaintiffs allege the Willfulness Penalty is designed to punish and is therefore subject to the Excessive Fines Clause. Plaintiffs further allege the Willfulness Penalty is grossly disproportionate to the gravity of the offense.
Plaintiffs’ Eighth Amendment claims, however, are not ripe for adjudication because no withholding or FBAR penalty has been imposed against any Plaintiff . . .
* * *
IV. Conclusion
Plaintiffs have failed to establish that they are entitled to a preliminary injunction . . . The FATCA statute, the IGAs, and the FBAR requirements encourage compliance with tax laws, combat tax evasion,37 and deter the use of foreign accounts to engage in criminal activity. A preliminary injunction would harm these efforts and intrude upon the province of Congress and the President to determine how best to achieve these policy goals. Thus, Plaintiffs’ Motion for Preliminary Injunction, ECF 8, is DENIED.
DONE and ORDERED in Dayton, Ohio, this Tuesday, September 29, 2015.
* * *
Crawford v. U.S. Department of Treasury, 15-cv-00250, U.S. District Court, Southern District of Ohio (Dayton).
For those U.S. citizens and lawful permanent residents residing outside the U.S. who expected the Courts to be sympathetic to their legal arguments somehow invalidating Chapter 4/FATCA and the FBAR filing requirements under Title 31, they will surely be disappointed by the result.
Taxpayer’s Burden of Proving the Impossible (?) – Chapter 3 and Chapter 4 (FATCA) Withholding Taxes Paid by Third Parties
The IRS has issued a Notice (Notice 2015-10) this year announcing its intention to modify the Treasury Regulations regarding tax refunds. This new series of rules, Guidance on Refunds and Credits Under Chapter 3, Chapter 4, and Related Withholding Provisions will complicate the lives of taxpayers significantly. 
Indeed, I have already seen and handled cases where the IRS asserts the taxpayer is not entitled to a tax refund, unless and until they can prove the third party who withheld and paid over the tax (issuing IRS Forms 1042 to all parties, including the IRS and the taxpayer) actually issued and deposited those payments.
These cases are like “proving a negative” since the withholding agent (typically a bank) who made and paid over the deposit, almost never makes single identifying payments for each amount of tax withheld. Typically, there are multiple taxpayers where the withholding tax was made and a single deposit made to the IRS. Those are indeed the specific rules set forth by the IRS. See, IRS Publication 515, withholding of tax on nonresidents
It gets even worse in Qualified Intermediary (“QI”) cases, where a large pool of withholding taxes are made. Typically, I have found the financial institution keeps detailed records of the payments and deposits (along with IRS Forms 1042s), but never has a payment specific to a particular taxpayer, as the deposit payments correspond to multiple taxpayers at once. Indeed, the IRS has acknowledged this treatment in this notice when it states:
Under the existing information reporting, withholding, and deposit procedures, a withholding agent does not indicate to which beneficial owner the deposit of tax relates, and such information is not reported on Form 1042 or 1042-S. Under the existing procedures, therefore, an amount deducted by the withholding agent with respect to a payment to the beneficial owner cannot be matched with an amount of tax deposited in the withholding agent’s Form 1042 account.
See page 5 of (Notice 2015-10).
There is a huge incentive for withholding agents to timely pay and deposit the taxes. There are harsh penalties levied against the withholding agent if they do not timely deposit and pay over the taxes, as follows:
Penalty rate. If the deposit is:
- 1 to 5 days late, the penalty is 2% of the underpayment,
- 6 to 15 days late, the penalty is 5%, or
- 16 or more days late, the penalty is 10%.
However, if the deposit is not made within 10 days after the IRS issues the first notice demanding payment, the penalty is 15%.
In short, the proposal in the form of modifying the regulations puts the burden on the nonresident taxpayer to prove the tax was withheld, before he or she will be entitled to a refund.
This is a new development in a series of developments where the IRS and Treasury simply issue regulations in areas of the law they do not seem to like. Further, it puts an unrealistic burden on nonresident taxpayers who are relying upon the third party withholding agent who makes the payment of taxes.
The long term affect of this rule, will be to force more taxpayers to file suits for refund in the Court of Federal Claims or U.S. District Court, which is necessarily complicated and costly.
More posts to come on this Notice 2015-10 and amendments to the Chapter 3 and Chapter 4 (FATCA) withholding tax regulations.
Letter from Your Non-U.S. Bank Regarding Chapter 4 of Subtitle A of the U.S. Internal Revenue Code – aka – “FATCA”
Prefer a Q&A format instead? Read this.
Financial institutions, outside the U.S. have been taking numerous steps to advise their U.S. born clients and U.S. resident clients about the reporting of their account information to the U.S. Internal Revenue Service.
These letters take various forms, depending upon the institution. In short, they normally say that as a result of the “Foreign Account Tax Compliance Act” (aka – FATCA, which comes from the newly created Chapter 4 of Subtitle A of the Internal Revenue Code, Title 26) they will be providing various account information to the U.S. Internal Revenue Service.
Some institutions are accelerating the information provided to include the account number, account holders/owners, balances and income from all sources. FATCA does not require all of this information until it is fully phased in over the next couple of years.
Many U.S. born individuals who have resided virtually all of their lives outside the U.S., often find out for the first time they are U.S. income tax residents by virtue of their birth and the 14th amendment of the U.S. Constitution. See, Co-author. “Tax Simplification: The Need for Consistent Tax Treatment of All Individuals (Citizens, Lawful Permanent Residents and Non-Citizens Regardless of Immigration Status) Residing Overseas, Including the Repeal of U.S. Citizenship Based Taxation,” by Patrick W. Martin and Professor Reuven Avi-Yonah, September 2013.
In many cases, I have seen and advised individuals who are first learning of these obligations when they open new accounts and the financial institution outside the U.S. requests an IRS Form W-9 with a U.S. taxpayer identification number, i.e., the social security number for U.S. citizens. See an older post (23 July 2014) – Why do I have to get a Social Security Number to file a U.S. income tax return (USCs)?
The financial institution will have them certify under penalty of perjury their status as a U.S. person or not. If the individual was born in the U.S., they will necessarily be a U.S. person unless (i) they were born to diplomatic parents who were on diplomatic assignment in the U.S., or (ii) they renounced their U.S. citizenship and obtained a Certificate of Loss of Nationality from the U.S. Department of State. See, The Importance of a Certificate of Loss of Nationality (“CLN”) and FATCA – Foreign Account Tax Compliance Act
These FATCA letters are no longer just for U.S. taxpayers with non-U.S. accounts. Countries throughout the world are using the exchange of information agreements between the U.S. Treasury and other countries, the Intergovernmental Agreements to notify their taxpayers that soon information about their U.S. accounts will be made available to their tax authorities. See, recent Mexican articles released including August 26, 2015, in the El Siglo de Torreón, titled Preparan SAT y EU auditorías: ”
“El Servicio de Administración Tributaria (SAT) realizará el primer intercambio de información con Estados Unidos en septiembre para las primeras auditorías de personas con cuentas bancarias en Estados Unidos a partir del próximo año, aseguró Aristóteles Núñez, jefe del fisco.
“Vamos a poder conocer quiénes tienen cuentas en Estados Unidos y con ello empezar a revisar quién ha pagado sus impuestos y si no lo ha hecho habrá auditorías.”
FATCA Driven (Even More . . . ) – New IRS Forms W-8BEN versus W-8BEN-E versus W-9 (etc. etc.) for USCs and LPRs Overseas – It’s All About Information and More Information (Part III)
Information and more information is the mantra of revised IRS Forms as a result of FATCA. See, FATCA Driven – New IRS Forms W-8BEN versus W-8BEN-E versus W-9 (etc. etc.) for USCs and LPRs Overseas – It’s All About Information and More Information
U.S. citizens residing outside the U.S. along with lawful permanent residents (“LPRs”) are not the only persons who need to understand the IRS forms referenced above. Indeed, all entities and institutions, whether they are small privately held companies or large and traditional financial institutions are required to complete and have signed a range of IRS forms.
The forms can be either the actual IRS form, or a satisfactory substitute form. Many individuals are of the erroneous view that if they are not financial institutions, they do not need to concern themselves with these classifications.
Unfortunately, that is not the case. Also, these classification rules apply to the surprise of many, if there are (or are not) U.S. persons involved.
In addition to a basic understanding of U.S. laws, it is also crucial that the parties see if their country has entered into an IGA. For instance, if we examine the tiny little country of Liechtenstein which has a relatively large financial sector, it is necessary to first classify the type of entity.
All of this is necessary in order to properly determine which IRS form is to be required to be completed (e.g., IRS Form W-8BEN-E o W-8BEN o W-9 or W-8IMY or W-8EXP, etc.). In addition, each of these classifications will help determine how to complete such forms.
For instance, if it is a Liechtenstein Stiftung, it will probably (but not necessary) be a trust and not a corporation. See the IRS Memorandum from 2009 that provides that a Liechtenstein Stiftung will be classified as a trust, if its primary purpose is to protect or conserve the property transferred to the Stiftung for the Stiftung’s beneficiaries and is usually not established primarily for actively carrying on business activities.[1]
[1] See Memorandum Number: AM2009-012, dated October 16, 2009, issued by the Office of Chief Counsel, Internal Revenue Service.
Next, in this example, with a Liechtenstein Stiftung, the country of Liechtenstein has entered into an Intergovernmental Agreement (“IGA”).
Hence, the terms of the IGA are most important. Under the IGA, as is the case generally for FATCA, the entity has to be either an Foreign Financial Institution (“FFI” or “FI”) or a Non-Financial Foreign Entity (“NFFE”).
1) Definition of Financial Institution (“FI”)
A financial institution is any entity that:
- Accepts deposits in the ordinary course of a banking or similar business (“Depository Institution”);[1]
- Holds, as a substantial portion of its business financial assets for the benefit of one or more other persons (“Custodial Institution”);[2]
- Is an investment entity; or
- Is an specified insurance company or holding company that is a member of an expanded group;[3]
[1] See Article 1(i), IGA.
[2] See Article 1(h), IGA.
[3] See Article 1(k), IGA.
Generally a private Liechtenstein Stiftung would not satisfy any of these requirements (although it could conceivably be the case that one could be an “investment entity”). Hence, it would generally be an NFFE and not an FI.
NFFEs can be passive or active. The kind of compliance obligations varies depending on the type of NFFE (passive or active).
- Passive NFFEs
A passive NFFE is an NFFE which is not an active NFFE or a withholding foreign partnership or withholding foreign trust.[1]
There are several criteria under which a NFFE can be classified as an active NFFE. The following explain the most relevant criteria.
- Active NFFEs
Among the criteria that the IGA establishes, under which a NFFE can be considered as an Active NFFE, are the following:
1) If less than 50% of the NFFE’s gross income is passive income and less than 50% of the assets held by the NFFE are assets that produce or are held for the production of passive income during the preceding calendar year. A
2) Substantially all of the activities of the NFFE consist of holding (in whole or in part) the outstanding stock of, or providing financing and businesses other than the business of a Financial Institution.
Sometimes trusts or Stiftungs will also participate in or hold interests in companies, some of which may engage in active trades or businesses or simply hold passive investments. On the contrary, the companies/subsidiaries only hold other assets from which they derived passive income (e.g., dividends, interests, rents, royalties, etc.).[2]
This will determine if a Stiftung will be classified as a Passive NFFE or not under FATCA regulations and the IGA.
[1] It also can make a difference if the trust (or Stiftung in this example) is a so-called “withholding” foreign trust; which generally requires an agreement with the IRS.
[2] Treas. Reg. § 1.1472-1.
Not surprisingly, the above analysis is complex, because the rules are complex. Accordingly, it has been the author’s experience, that many institutions around the world which request one or more of the above IRS Forms have great difficulty in even implementing these rules. Most of their employees seem to have little understanding of what is a very complex area of law, even when their resident country has issued extensive regulations or guidance about how the terms of the IGA are to be implemented.
Part II: U.S. Department of State has Allowed (Starting in at least 2013) USCs to Keep their U.S. Passports After Oath and Prior to Receiving CLN
See the first post on this topic: U.S. Department of State has Allowed (Starting in at least 2013) USCs to Keep their U.S. Passports After Oath and Prior to Receiving CLN, Posted on March 17, 2015
A U.S. citizen is required to have a U.S. passport to enter the U.S., according to the immigration law regulations 22 CFR § 53.1 require that a U.S. citizen have a U.S. passport to enter or depart the United States.  The relevant part of the regulations is § 53.1(a) which provides as follows:
Passport requirement; definitions.
(a) It is unlawful for a citizen of the United States, unless excepted under 22 CFR 53.2, to enter or depart, or attempt to enter or depart, the United States, without a valid U.S. passport.
***
These regulations were first published in 2006, and rely in part on a Presidential Executive Order made by President Bush (Jr.). See a prior post,
USCs without a . . . Passport . . . Cannot Travel to the U.S., Posted on May 17, 2015. In that post and a later post, I explained how a social security number is currently not an indispensable requirement for U.S. citizens who wish to travel to the U.S. and need to apply for a passport.
*
*
This background is relevant for U.S. citizens who take the oath of renunciation. Previously, many U.S. embassies and U.S. Consulates around the world would physically take the U.S. passport of the individual upon taking the oath of renunciation and completing U.S. Department of State
Form DS-4080. See, a prior post,
Documents to Request the Consular Officer When Renouncing U.S. Citizenship, Posted on May 28, 2014, which provides as follows:
*
The U.S. Department of State does not always provide any specific document, e.g., a certified copy of any of the following documents, after you take the oath of renunciation:
The Intersection of U.S. Federal Tax Law with Collection of International Information – Including other Federal Agencies
For decades, the IRS largely worked in a vacuum, relative to other government agencies.
Changes started in earnest in 2003 after September 11, 2001, when Congress past various anti-terrorism laws. For details of the history and how and when the IRS became responsible for these functions, the IRS Internal Revenue Manual has a detailed explanation – Part 4, Chapter 26, Section 5. Bank Secrecy Act History and Law
In April 2003, the IRS became in charge of civil enforcement of foreign account information under Title 31. See IRM, Part 4, Chapter 26, Section 16. Report of Foreign Bank and Financial Accounts (FBAR).
The world has changed dramatically in these past few years and the IRS no longer works in such a vacuum. For a history of foreign bank and Congressional influences, see, How Congressional Hearings (Particularly In the Senate) Drive IRS and Justice Department Behavior
Today there are a host of governmental inter-agency activities along with foreign government exchanges of information; e.g., DHS, Department of State, ICE, USCIS, foreign government exchanges of information under FATCA IGAs, a plethora of federal “intelligence agencies” for “terrorism related requests” as identified in IRM pursuant to IRC Section 6103(i), foreign governments under tax treaty exchanges, among many others.
The law is not even clear as to which agencies qualify as “intelligence agencies” as they are not identified in the statute and many are presumably classified organizations.
- Who is an “intelligence agency” for purposes of the statute?
The following is a list of some of the intelligence agencies that are presumably included in the federal tax statute Section 6103(i)(7):
A less secret organization is the Social Security Administration which now increasingly intersect with the work of
the IRS. Also, the Department of State now provides warnings on its Passport applications about tax consequences and requirements of social security numbers (“SSN”s).
See also how in an Application for a U.S. Passport there are now specifically references IRC Section 6039E.
Finally, see also how on the last page (page 28) of currently issued U.S. Passport (“Book“) and paragraph D that explains generally the taxation obligations of citizenship.
–
USCs without a Social Security Number (and a Passport) Cannot Travel to the U.S.
Recent posts have focused on the dilemma facing U.S. citizens (USCs) who have no social security number (“SSN”). See an older post (23 July 2014) – Why do I have to get a Social Security Number to file a U.S. income tax return (USCs)?
These problems are quickly coming to the surface, now that financial institutions (“FFIs”) around the world and private companies and trusts (e.g., non-financial foreign entities -NFFEs) must have their owners and clients certify they are not U.S. citizens; OR report the accounts of such U.S. citizens to the IRS under FATCA and the intergovernmental agreements (“IGAs”).
See, U.S. Citizens Overseas who Wish to Renounce without a Social Security Number will Necessarily be a “Covered Expatriate”
The intricacies of this problem are highlighted in a technical paper I recently drafted and presented to the U.S. Treasury Department and the Joint Committee of Taxation, among other federal government groups. Some key excerpts of that paper titled URGENT NEED FOR U.S. CITIZENS RESIDING OUTSIDE THE U.S. TO BE ABLE TO OBTAIN A TAXPAYER IDENTIFICATION NUMBER (“TIN”) OTHER THAN A SOCIAL SECURITY NUMBER are set out below in this section:
The U.S. tax law imposing taxation on the worldwide income of USCs[1] residing overseas has created a dilemma that prejudices these USCs without a SSN. This strict SSN/TIN regulatory rule undermines the basic tax administration system and discourages tax compliance for those USCs who never obtained a SSN. This dilemma affects numerous USCs throughout the world, which is now compounded by the certification and reporting requirements of USCs and third parties, such as FFIs and NFFEs[ under the Foreign Account Tax Compliance Act (“FATCA”).
In short, USCs without a SSN, necessarily cannot be in compliance with U.S. federal tax law. As I point out in my paper, such –
“A law that cannot be complied with is surely a bad law, the same as a “ . . .law that cannot be enforced is a bad law.”[a]
[a] See, The Case Against Taxing Citizens, Reuven S. Avi-Yonah (March 31, 2010), University of Michigan School of Law, Law & Economics Working Papers.
The paper referenced above explains how difficult it is for USCs residing overseas to ever obtain a SSN. Specifically, it explains how difficult it is to have an in-person interview at only 18 different locations around the world with a U.S. Department of State employee. See, 12 Year Old (and Older) U.S. Citizens Residing Outside the U.S. Must Have An “In-Person” Interview in a U.S. Embassy or Consulate for SSN Application in 1 of Just 17 Posts Worldwide
As a USC residing somewhere around the world, you might decide to simply spend the time, money and resources to travel internationally to arrive in the U.S. to apply for a SSN directly with the Social Security Administration within the U.S. Unfortunately, any USC is now legally prohibited from traveling in or out of the U.S. without a U.S. passport. There are few exceptions to this general rule, none of which contemplate U.S. federal tax compliance. See, the relevant excerpts from the white paper:
C. Travel to the U.S. is Also Not An Option for a USC without a SSN, Due to 22 CFR § 53.1 Requiring a U.S. Passport
A possible solution to this TIN/SSN dilemma may appear to be a trip to the U.S. by the USC to apply for a SSN in the U.S. Unfortunately, this simply creates another dilemma, since the USC must have a U.S. passport to travel to the U.S. The immigration law regulations 22 CFR § 53.1 require that a U.S. citizen have a U.S. passport to enter or depart the United States. The relevant part of the regulations is § 53.1(a) which provides as follows:
Passport requirement; definitions.
(a) It is unlawful for a citizen of the United States, unless excepted under 22 CFR 53.2,[2] to enter or depart, or attempt to enter or depart, the United States, without a valid U.S. passport.
These regulations were first published in 2006 and unfortunately, simply create another dilemma for the USC residing overseas without a SSN. This additional dilemma is that an application[3] for a U.S. passport requires the individual have a SSN; a vicious circle back to the inability to obtain a SSN.
At the end of the day, the restrictions imposed on USCs make it legally impossible for a USC without a passport to travel to the U.S. (even if they wish they could) to obtain a SSN.
[1] See, IRC § 61 and Treas. Reg. §§ 1.1?1(b) and 1.1?1(a)(1)..
[2] The exceptions set forth in this regulation would not generally be applicable in the case of USCs residing overseas without a SSN.
[3] Application for a U.S. Passport – http://www.state.gov/documents/organization/212239.pdf.
12 Year Old (and Older) U.S. Citizens Residing Outside the U.S. Must Have An “In-Person” Interview in a U.S. Embassy or Consulate for SSN Application in 1 of Just 17 Posts Worldwide
As previous posts have mentioned, U.S. citizens (USCs) residing overseas can only comply with U.S. tax law and FATCA certifications if they have a social security number (SSN). See, U.S. Citizens Overseas who Wish to Renounce without a Social Security Number will Necessarily be a “Covered Expatriate”
See key excerpts of the paper titled URGENT NEED FOR U.S. CITIZENS RESIDING OUTSIDE THE U.S. TO BE ABLE TO OBTAIN A TAXPAYER IDENTIFICATION NUMBER (“TIN”) OTHER THAN A SOCIAL SECURITY NUMBER that explains this dilemma:
This dilemma affects numerous USCs throughout the world, which is now compounded by the certification and reporting requirements of USCs and third parties, such as FFIs and NFFEs[2] under the Foreign Account Tax Compliance Act (“FATCA”).
* * *
The regulations provide the specific rule that all USCs must have a SSN[1] as their TIN. There are no general exceptions in the regulations to the requirement that a USC must have a SSN as their TIN.
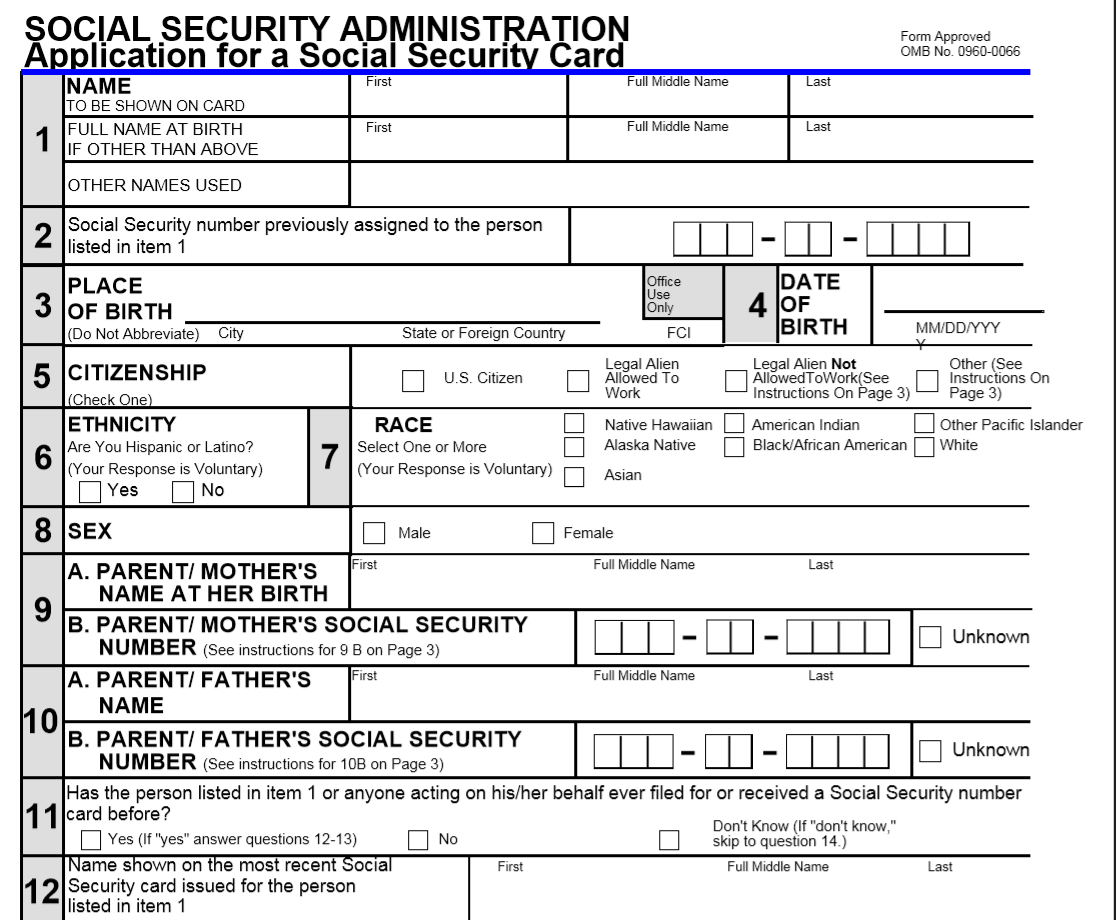
This regulatory requirement specifically directs the USC to the forms that must be completed and filed with the SSA, in order to obtain a SSN, as follows:[2]
(1) Social security number. Any individual required to furnish a social security number pursuant to paragraph (b) of this section shall apply for one, if he has not done so previously, on Form SS-5, which may be obtained from any Social Security Administration or Internal Revenue Service office. He shall make such application far enough in advance of the first required use of such number to permit issuance of the number in time for compliance with such requirement. The form, together with any supplementary statement, shall be prepared and filed in accordance with the form, instructions, and regulations applicable thereto, and shall set forth fully and clearly the data therein called for. Individuals who are ineligible for or do not wish to participate in the benefits of the social security program shall nevertheless obtain a social security number if they are required to furnish such a number pursuant to paragraph (b) of this section. [emphasis added]
These Title 26 regulations discuss individuals requesting forms from “any Social Security Administration or Internal Revenue Service office” which clearly implies that the SSA and the IRS have offices overseas.
Unfortunately, this is not the case, as the IRS recently announced it is closing its full-time walk-in offices in London, Frankfurt and Paris, as the office in Beijing, China was closed in 2014.[3] Similarly, the SSA has no overseas offices, but does have limited field office operations in Canada, the British Virgin Islands and Samoa.[4]
Therefore, it is clear that the above regulations are speaking to individuals who reside and live in the U.S., and not USCs residing overseas when it requires USCs to “ . . . make such application far enough in advance of the first required use of such number to permit issuance of the number in time for compliance with such requirement. [5]
These Title 26 regulations require the application be made well in advance of any tax filing requirements are not realistic for USCs residing overseas as is explained herein. This author has seen the issuance of SSNs take more than 6 months, even when the USC could have an interview in their country of residence.
More importantly, there are very few countries (only 17) where in-person interviews can even be held. See, discussion below.
USCs who have lived most, if not all of their lives outside the U.S., commonly do not have a SSN. The procedural requirements imposed by the SSA to obtain a SSN in these cases are complicated and unrealistic for USCs living overseas.[6] This author has seen cases where USCs residing overseas have even spent the money and resources and time to travel to the U.S. to apply for a SSN, yet were turned away by the SSA, due to various procedural requirements which were not satisfied.
Often times obtaining a SSN overseas is nearly impossible, depending upon which country and where within that country the USC resides.
A. Obtaining a SSN Outside the US by a USC – Much More than Just Filing SSA Form SS-5
The SSA does not have offices outside the U.S. although they have a so-called “Office of International Operations.”[7] The focus of OIO is the administration of social security benefits, not obtaining SSNs for USCs residing overseas. Since the SSA is assisted by the U.S. Department of State (who are not SSN experts), USCs have to rely upon various U.S. embassies and consulate offices around the world, as they try to obtain a SSN.
B. Tax Return Filing Requirements – Minimum Gross Income
Any USC individual is obligated under the U.S. federal tax law to file a federal income tax return IRS Form 1040 if they meet minimum thresholds of income. For the tax year 2015, the thresholds are low, and are reached once the gross income is at least the sum of (i) the “exemption” amount (currently $4,000) and (ii) the “standard deduction” amount (currently $6,300 for single and married filing jointly and $12,600 for married couples filing jointly).[8]
This is true, even if all of the income is earned income and eligible for the foreign earned income exclusion, which is $100,800 for the tax year 2015. [9]
Additionally, USCs living overseas necessarily have a U.S. tax return filing requirement, when they meet these low thresholds of gross income. In these cases, tax returns that are not filed by the 15th of June are not considered timely filed.[10]
II. The Social Security Administration Rules Make it Nearly Impossible for Many USCs Overseas to Reasonably Obtain a SSN
The policy and procedures of the SSA regarding issuing SSNs have changed significantly over the years.[11] The Social Security Administration (SSA) provides a detailed chronology of the major changes in policy and procedures regarding filing for and obtaining a SSN.[12] One of the most significant revisions in the last decade came from The Intelligence Reform and Terrorism Prevention Act of 2004 (P.L. 108-458), which imposes various standards for the verification of documents or records submitted by an individual.
A. Only a Few Countries Around the World have Personnel at U.S. Embassies or Consulate Offices that Can Process SSN Applications – SSA Form SS-5-FS
Applying for SSNs overseas is severely restricted compared to an application in the U.S.
According to the U.S. Department of State, Foreign Affairs Manual (“FAM”), only certain “Claims-Taking Posts” in specific countries “may” include “processing applications for Social Security Numbers.” [13]
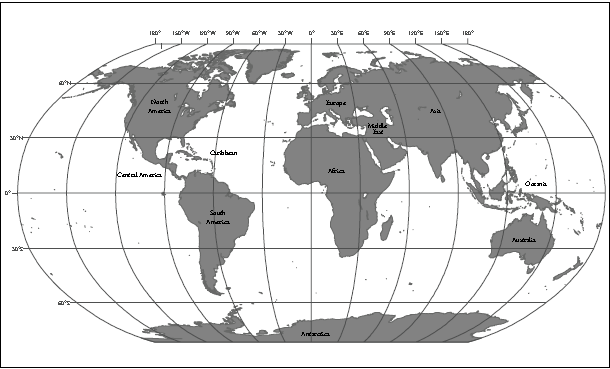
These 17 countries (and a city in the case of Jerusalem) with Claims-Taking Posts include:
“Austria, Argentina, Costa Rica, Dominican Republic, France, Germany, Greece, Ireland, Italy, Japan, Jerusalem, Mexico, Norway, Philippines, Poland, Portugal, Spain, and the United Kingdom.”
Noticeably absent are many Western European countries, virtually all of Latin America, virtually all of Asia, virtually all of Eastern Europe, all of the Middle East (except Jerusalem), all of the African continent, all of the Australian continent and surrounding island countries and Russia, among many other significant countries, including OECD member countries.[14]
Nothing in the FAM requires any of these “Claims-Taking Posts” to actually process applications for a SSN. Plus, there are of course hundreds of other countries throughout the world, not listed above, which do not have such a U.S. Department of State Post. For these reasons, USCs in countries such as China must travel to a U.S. Department of State Post (e.g., the Philippines) which is able to process applications for SSNs.
B. In Person Interview Required for Individuals Older than 11 Years Old
Individuals who are older than 11 years old must personally go to the U.S. Embassy or Consulate with a Claims-Taking Post. See 7 FAM 530, pages 7, 12, 13 and 7 FAM EXHIBIT 530(D) Mandatory In-Person Interview Worksheet SSN Applicant Age 12 or Older – Original SSN * * *
All of these rules makes you wonder whether foreign born individuals, such as actress Kim Cattrall from Sex & the City fame would have ever obtained a social security number overseas while she lived in Canada or the UK.
[1] See, Treas. Reg. § 301.6109-1(a)(1)(ii)(A).
[2] See, Treas. Reg. § 301.6109-1(d)(1).
[3] See, Bloomberg article, 14 January 2015 by Kocieniewski, IRS Will Shut Last Overseas Taxpayer-Assistance Centers: “After budget reductions over the last four consecutive years, the IRS is forced to make tough choices during this period of fiscal austerity and these closures have relatively little impact on taxpayers and treaty partners,” said Julianne Breitbeil, an IRS spokeswoman. Also, see IRS website that still reflects the London and Paris offices as open http://www.irs.gov/uac/Contact-My-Local-Office-Internationally.
[4] See, SSA website, Service Around the World, http://www.ssa.gov/foreign/
[5] See, Treas. Reg. § 301.6109-1(d)(1).
[6] See discussion below, regarding requirements to obtain a SSN. I.II, I.I,The Social Security Administration Rules Make it Nearly Impossible for Many USCs Overseas to Reasonably Obtain a SSN
[7] See SSA website, “Office of International Operations” – http://www.ssa.gov/foreign/ “Service Around the World – Welcome to SSA’s Office of International Operations (OIO) home page. The purpose of this site is to assist Social Security customers who are outside the U.S. or planning to leave the U.S. OIO is responsible for administering the Social Security program outside the U.S. and for the implementation of the benefit provisions of international agreements. Since SSA has no offices outside the U.S., OIO is assisted by the Department of State’s embassies and consulates throughout the world.”
[8] See, IR-2014-104, Oct. 30, 2014 and IRS Publication 501.
[9] See, IRC § 911 and IRS Publication 54.
[10] See, Treas. Reg. § 1.6081-5.
[11] See, SSA website, The Story of the Social Security Number, by Carolyn Puckett, Social Security Bulletin, Vol. 69 NO. 2, 2009 (http://ssa.gov/policy/docs/ssb/v69n2/v69n2p55.html.
[12] See, SSA website, Significant Milestones in Social Security Number Policy. A detailed chronology of the major changes in policy and procedures. http://www.ssa.gov/history/ssn/ssnchron.html.
[13] See 7 FAM 530, page 2 of 64.
[14] In contrast to these 17 countries (and one city – Jerusalem) where a USC residing overseas must travel to apply for a SSN, the Treasury Department has announced it has around 100 countries that have signed, or “have reached agreements in substance” a FATCA IGA. USCs throughout the world are required by the Foreign Account Tax Compliance Act (“FACTA”) to provide their U.S. TIN to financial institutions throughout the world (on IRS Form W-9, or its equivalent), which under current law necessarily must be a SSN. Of course, if they have no SSN, they cannot sign IRS Form W-9 which provides in Part II: “Under penalties of perjury, I certify that: 1. The number shown on this form is my correct taxpayer identification number . . .”
[15] See, 7 FAM 534.3 e.
U.S. Citizens Overseas who Wish to Renounce without a Social Security Number will Necessarily be a “Covered Expatriate”
U.S. Citizens Overseas who Wish to Renounce without a Social Security Number (“SSN”) will Necessarily be a “Covered Expatriate”
- The Dilemma of SSNs, TINs and USCs Residing Overseas
The prior post discussed some of the complications of United States Citizens (“USCs”) who reside outside the U.S. and do not have a social security number (“SSN”) . This dilemma exists, even though USCs are not generally required to file for or  obtain a SSN (e.g., at birth – See, SSA Publication – “Social Security Numbers For Children” page 2, It is not obligatory to file for a SSN at birth. “Must my child have a Social Security number? No. Getting a Social Security number for your newborn is voluntary. But, it is a good idea to get a number when your child is born. . . . ).
Indeed, it is the U.S. federal tax law that requires the USC must have a SSN for their taxpayer identification number (“TIN”). I will reference various excerpts from a recent paper I drafted and presented titled URGENT NEED FOR U.S. CITIZENS RESIDING OUTSIDE THE U.S. TO BE ABLE TO OBTAIN A TAXPAYER IDENTIFICATION NUMBER (“TIN”) OTHER THAN A SOCIAL SECURITY NUMBER , including the following:
. . . the IRS’ increased focus on international tax compliance has made clear that USCs residing overseas have U.S. tax return filing obligations, even if they have no assets, no income, or no real personal connections in or with the U.S. See IRS notice from 2011 which addresses numerous aspects of tax compliance for USCs overseas, including various penalties under the law[1]:
. . . U.S. Citizens or Dual Citizens Residing Outside the U.S. . . .
The IRS is aware that some taxpayers who are dual citizens of the United States and a foreign country may have failed to timely file United States federal income tax returns or Reports of Foreign Bank and Financial Accounts (FBARs), despite being required to do so. . . . 2. Penalties imposed for failure to file income tax returns or to pay tax . . . 3. Possible additional penalties that may apply in particular cases . . . 6. Possible penalties for failure to file FBAR . . . 7. New reporting requirement for foreign financial assets . . . [emphases added]
USCs residing overseas are subject to the range of tax penalties that apply to all individual taxpayers (e.g., negligence penalties, failure to file penalties, late payment or failure to pay penalties, etc.).[2] Additionally, USCs residing overseas are subject to other, typically much harsher penalties for not timely filing U.S. federal information returns regarding assets located outside the U.S.[3]; alluded to above in the IRS 2011 notice.[4]
These civil penalties typically are a minimum of US$10,000 per statutory violation. USCs who live outside the U.S. necessarily have assets, such as financial accounts in their country of residence. These Title 26 information reporting requirements[5] are referred to herein as “International Information Returns.”
The IRS will not process federal tax returns and International Information Returns without a valid TIN.[6] Plus, the law does not provide for an exception for USCs overseas who do not file returns, if they do not have a SSN. Late filed, or incomplete International Information Returns and tax returns (e.g., lacking a SSN) will typically subject USCs to these penalties even in those cases when the taxpayer has no federal income tax liability.[7]
[1] See, IRS FS-2011-13, December 2011, updated February, 2014.
[2] See, IRS FS-2011-13 and as a sample of some of the many statutory penalties that could typically apply, IRC §§ 6048, 6652(f), 6677, 6654, 6655, 6698, 6699, 6166, 6653, 6675, 6715, 6715A, 6717, 6718, 6719, 6720A, 6725, et. seq.
[3] See, IRC §§ 6038, 6038B, 6038D, 6039F, 6039G, 6046, 6046A, 6048, et. seq.
[4] See, IRS FS-2011-13, December 2011, updated February, 2014.
[5] See, IRC §§ 6038, 6038B, 6038D, 6039F, 6039G, 6046, 6046A, 6048, et. seq.
[6] See, IRS website, “General ITIN Information” – http://www.irs.gov/Individuals/General-ITIN-Information – “IRS no longer accepts, and will not process, forms showing “SSA”, 205c”, “applied for”, “NRA”,& blanks, etc.”
[7] See, IRC §§ 911 (foreign earned income exclusion) and 901 (foreign tax credit), et. seq. A USC residing overseas may have no actual federal income tax liability (for various reasons), typically due to the foreign earned income exclusion and/or foreign tax credit calculation.
The above explains fairly clearly the dilemma facing USCs residing overseas.
The complexity of getting a SSN and the requirements are covered in more detail in the paper. Some key points are:
I. The Social Security Administration Rules Make it Nearly Impossible for Many USCs Overseas to Reasonably Obtain a SSN
The policy and procedures of the SSA regarding issuing SSNs have changed significantly over the years.[1] The Social Security Administration (SSA) provides a detailed chronology of the major changes in policy and procedures  regarding filing for and obtaining a SSN.[2] One of the most significant revisions in the last decade came from The Intelligence Reform and Terrorism Prevention Act of 2004 (P.L. 108-458), which imposes various standards for the verification of documents or records submitted by an individual.
A. Only a Few Countries Around the World have Personnel at U.S. Embassies or Consulate Offices that Can Process SSN Applications – SSA Form SS-5-FS
Applying for SSNs overseas is severely restricted compared to an application in the U.S.
According to the U.S. Department of State, Foreign Affairs Manual (“FAM”), only certain “Claims-Taking Posts” in specific countries “may” include “processing applications for Social Security Numbers.” [3]
These 17 countries (and a city in the case of Jerusalem) with Claims-Taking Posts include:
“Austria, Argentina, Costa Rica, Dominican Republic, France, Germany, Greece, Ireland, Italy, Japan, Jerusalem, Mexico, Norway, Philippines, Poland, Portugal, Spain, and the United Kingdom.”
Noticeably absent are many Western European countries, virtually all of Latin America, virtually all of Asia, virtually all of Eastern Europe, all of the Middle East (except Jerusalem), all of the African continent, all of the Australian continent and surrounding island countries and Russia, among many other significant countries, including OECD member countries.[4]
Nothing in the FAM requires any of these “Claims-Taking Posts” to actually process applications for a SSN. Plus, there are of course hundreds of other countries throughout the world, not listed above, which do not have such a U.S. Department of State Post. For these reasons, USCs in countries such as China must travel to a U.S. Department of State Post (e.g., the Philippines) which is able to process applications for SSNs.
[1] See, SSA website, The Story of the Social Security Number, by Carolyn Puckett, Social Security Bulletin, Vol. 69 NO. 2, 2009 (http://ssa.gov/policy/docs/ssb/v69n2/v69n2p55.html.
[2] See, SSA website, Significant Milestones in Social Security Number Policy. A detailed chronology of the major changes in policy and procedures. http://www.ssa.gov/history/ssn/ssnchron.html.
[3] See 7 FAM 530, page 2 of 64.
[4] In contrast to these 17 countries (and one city – Jerusalem) where a USC residing overseas must travel to apply for a SSN, the Treasury Department has announced it has around 100 countries that have signed, or “have reached agreements in substance” a FATCA IGA. USCs throughout the world are required by the Foreign Account Tax Compliance Act (“FACTA”) to provide their U.S. TIN to financial institutions throughout the world (on IRS Form W-9, or its equivalent), which under current law necessarily must be a SSN. Of course, if they have no SSN, they cannot sign IRS Form W-9 which provides in Part II: “Under penalties of perjury, I certify that: 1. The number shown on this form is my correct taxpayer identification number . . .”
- The Necessary “Covered Expatriate Status” of a USC without a SSN
The core point of this post, with the above SSN background, is to explain how a USC without a SSN will necessarily be a “covered expatriate” since they will not be able to truthfully certify they have complied with the federal tax laws (title 26). See, Certification Requirement of Section 877(a)(2)(C) – (5 Years of Tax Compliance) and Important Timing Considerations per the Statute
As other posts have explained, “covered expatriate” status matters:
See, Why “covered expat” (“covered expatriate”) status matters, even if you have no assets! The “Forever Taint”! (20 May 2014) and The “Hidden Tax” of Expatriation – Section 2801 and its “Forever Taint.” (10 April 2014) and “Covered Expatriate” Status is a “Scarlet Letter” (10 Nov 2014).
If a USC has no SSN, they by definition will never be able to comply with the Certification Requirement of Section 877(a)(2)(C) since they will not be able to comply with IRC § 6109(a) and Treas. Reg. § 301.6109-1. As the SSN/TIN paper explains:
All United States citizens (“USCs”) must have a social security number (“SSN”) under current law as their TIN to file a federal income tax return.[1]
[1] See, IRC § 6109(a) and Treas. Reg. § 301.6109-1.
The IRS will not process federal tax returns and “International Information Returns”, as defined below, without a valid TIN[1]; which currently must be a SSN for a USC.
[1] See, IRS website, – http://www.irs.gov/Individuals/General-ITIN-Information – “IRS no longer accepts, and will not process, forms showing “SSA”, 205c”, “applied for”, “NRA”,& blanks, etc.”