The Importance of Planning – PRIOR to Renouncing, Relinquishing or Abandoning
International tax law experts who specialize in a particular area of the law, have a fairly good understanding of the importance of tax planning. The reason is simple. The law is complex and without planning,  laypeople can often cause very adverse tax consequences to themselves and their friends and family members (in the case of tax expatriation) without understanding the full implications of the law.
“Tax expatriation” in the U.S. is particular complex for several reasons:
1. The general rule is that there is an immediate income tax payable from the “mark to market” taxation rules on unrealized gains. See, Part I: Common Myths about the U.S. Tax and Legal Consequences Surrounding “Expatriation”
2. If a tax is recognized under the U.S. tax law, the only way to discharge the liability with the U.S. federal government is to pay the tax owing. The IRS generally can collect an income tax owing against a taxpayer who lives outside the U.S. indefinitely, as the 10 year collection statute does not apply when the individual outside the United States for a continuous period of at least six months. See, IRC Section 6503(c). More on this topic in another post. In other words, the IRS can “forever” pursue the collection of the “expatriation tax” against USCs and LPRs living outside the U.S.
3. It is easy to fall into the general rule of expatriation, even if the taxpayer would not otherwise be subject to income taxation. See, Why “covered expat” (“covered expatriate”) status matters, even if you have no assets! The “Forever Taint”!
4. The friends and family of the “covered expatriate” – i.e., the former U.S. citizen and long-term lawful permanent resident can be subject to U.S. taxation during their lifetimes, even if they also live outside the U.S. See also, some of the consequences of being a “covered expatriate” – The “Hidden Tax” of Expatriation – Section 2801 and its “Forever Taint.”
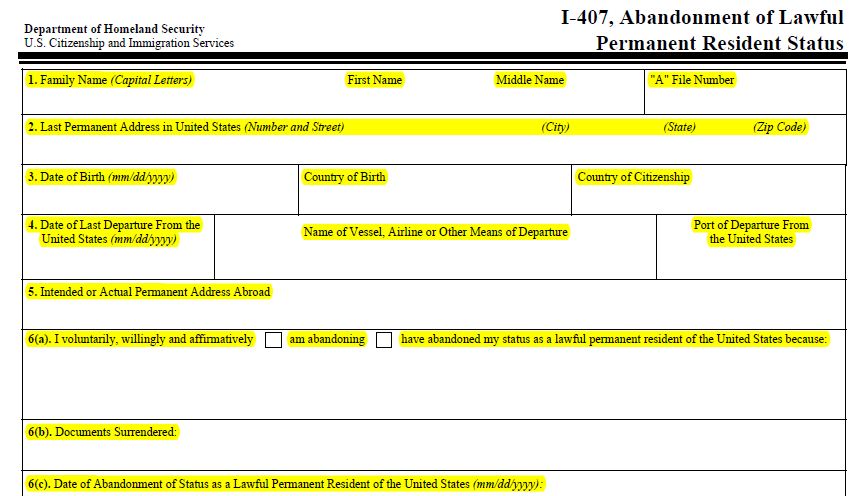
Each of these points help demonstrate the need for planning prior to running to the U.S. Department of State and completing and filing the following forms when you take the oath of renunciation:
Form DS-4081, Statement of Understanding Concerning the Consequences and Ramifications of Relinquishment or Renunciation of U.S. Citizenship.
See, Documents to Request the Consular Officer When Renouncing U.S. Citizenship
At the end of the day, if the individual lives outside the U.S. and does not travel to and from the U.S., it may be very difficult (at least practically speaking) for the IRS to collect on the tax judgment owing, if the individual has no assets in the U.S. There are legal means and steps the IRS can take in an attempt to try to collect U.S. taxes on overseas assets.
For a further discussion on collection of taxes overseas:
See, U.S. Enforcement/Collection of Taxes Overseas against USCs and LPRs – Legal Limitations, and
Part II: U.S. Enforcement/Collection of Taxes Overseas against USCs and LPRs – Pasquantino – Wire Fraud and Mail Fraud
Ideally, a former U.S. citizen or long-term lawful permanent resident will wish to avoid all of the potential tax and collection issues, by engaging in thoughtful and strategic planning prior to their renunciation of U.S. citizenship or abandonment of lawful permanent residency.
Why a Naturalized Citizen cannot avoid “Covered Expatriate” status under IRC Section 877A(g)(1)(B)
A previous post explained why lawful permanent residents (LPRs) can never satisfy this exception in the law to avoid “covered expatriate status.” See, Why a “long-term” LPR can NEVER avoid “Covered Expatriate” status under IRC Section 877A(g)(1)(B) if Asset or Tax Liability Test is Satisfied!
For the same reasons, a naturalized citizen cannot satisfy the statutory requirement since they will never be able to meet the IRC Section 877A(g)(1)(B)(i)(I) requirement of becoming ” . . . at birth a citizen of the United States . . . ”
See the relevant provisions of the statute as follows:
(B) Exceptions
An individual shall not be treated as meeting the requirements of subparagraph (A) or (B) of section 877 (a)(2) if—
(I) became at birth a citizen of the United States and a citizen of another country and, as of the expatriation date, continues to be a citizen of, and is taxed as a resident of, such other country, and
(II) has been a resident of the United States (as defined in section 7701 (b)(1)(A)(ii)) for not more than 10 taxable years during the 15-taxable year period ending with the taxable year during which the expatriation date occurs, . . .
Of course a naturalized United States citizen by definition was not a citizen at birth and only became one upon completing the lengthy legal requirements of naturalization. See, USCIS website – Citizenship Through Naturalization
Why a “long-term” LPR can NEVER avoid “Covered Expatriate” status under IRC Section 877A(g)(1)(B) if Asset or Tax Liability Test is Satisfied!
There have been multiple posts explaining the importance of the certification requirement of Section 877(a)(2)(C).
See for instance, Certification Requirement of Section 877(a)(2)(C) – (5 Years of Tax Compliance) and Important Timing Considerations per the Statute, also see Can the Certification Requirement of Section 877(a)(2)(C) be Satisfied “After the Fact”?
This specific act of “certifying” is a requirement under the law, that requires all individuals (whether U.S. citizens or LPRs) to satisfy the elements of the certification, in order to avoid “covered expatriate” status.
Also, there is an important exception to “covered expatriate” status set forth in IRC Section 877A(g)(1)(B). Only certain individuals may be able to satisfy this important requirement, which provides as follows:
(B) Exceptions
An individual shall not be treated as meeting the requirements of subparagraph (A) or (B) of section 877 (a)(2) if—
(i) the individual—
(I) became at birth a citizen of the United States and a citizen of another country and, as of the expatriation date, continues to be a citizen of, and is taxed as a resident of, such other country, and
(II) has been a resident of the United States (as defined in section 7701 (b)(1)(A)(ii)) for not more than 10 taxable years during the 15-taxable year period ending with the taxable year during which the expatriation date occurs, or . . .
***
Importantly, the elements of the statute apply only to persons who “became at birth a citizen of the United States”; and in the case of lawful permanent residents (LPRs), they be definition will not have become at birth a citizen of the United States.
***
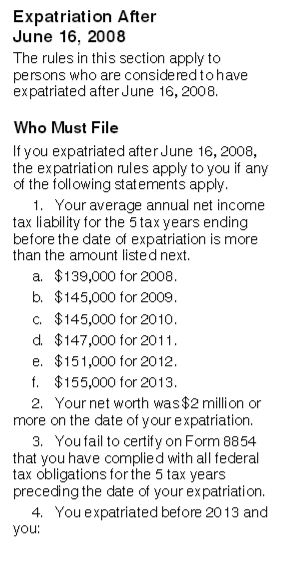
Accordingly, a “long term” LPR who meets either the US$2M asset test, or average income tax liability test (currently

US$157,000 for the year 2014), will necessarily become a “covered expatriate” even if they can satisfy the
Certification Requirement of Section 877(a)(2)(C).
**
**
**
Accordingly, it is important for each “long-term” LPR to understand clearly the current and future U.S. tax consequences to (i) them – the “mark-to market” tax, and (2) tax on “covered gifts” and “covered bequests” to U.S. persons. Importantly, understanding these consequences should be long before the LPR ceases to be a LPR for tax purposes; irrespective of the immigration law consequences.
Who is a “long-term” lawful permanent resident (“LPR”) and why does it matter?
The answer to the above question will only matter, for purposes of “tax expatriation” if the LPR plans on living and moving outside the U.S. The law defines a “’long-term resident’ as any individual (other than a citizen of the United States) who is a lawful permanent resident of the United States in at least 8 taxable years during the period of 15 taxable years.” See, IRC Section 877 (e)(2.
Importantly, there are key concepts of who satisfies these requirements, which is not as simple as it seems on its face. See, for instance Section 7701(b)(6) with specific rules for individuals who live in a country with a U.S. income tax treaty. Importantly, the definition of a lawful permanent resident for tax purposes (as defined in Section 7701(b) ) is not identical to the definition for immigration law purposes.
The importance of LPR status for tax purposes in the expatriation context is crucial. Its the saying “black or white” or “night or day” when thinking about the U.S. “expatriation” tax consequences to LPRs. In short, a LPR who never becomes a “long-term resident” as that technical term is defined in IRC Section 877 (e)(2) can avoid the various taxes that arise from otherwise being a “covered expatriate”. The future heirs and beneficiaries who receive assets from this LPR (who never was a “long-term resident?) can also avoid a major tax; currently 40% of the value of the gift or bequest. See, Revisiting the consequences of becoming a “covered expatriate” for failing to comply with Section 877(a)(2)(C).
The reason it is so important, is that if a LPR never becomes a “long-term resident”, he or she can never cause themselves to “expatriate” as that term is defined in IRC Section 877A(g)(2).
If a LPR never can “expatriate” under the tax law, he or she can never become subject to a range of adverse (some would say draconian) tax consequences that apply. See the following post for a further explanation of the various adverse tax consequences: Why “covered expat” (“covered expatriate”) status matters, even if you have no assets! The “Forever Taint”!
If there is no way in these circumstances for the LPR to “expatriate” there can be no “mark to market” tax and no future tax on covered gifts or covered bequests. See, Oops…Did I “Expatriate” and Never Know It: Lawful Permanent Residents Beware! International Tax Journal, CCH Wolters Kluwer, Jan.-Feb. 2014, Vol. 40 Issue 1, p9
Obviously, this is a very good result for a LPR to never become a “long-term resident”. Planning for it is another task; particularly given the personal living arrangements of each particular individual.
The determination of if or when one becomes a “long-term resident” is highly complex, due to different cross-provisions in the tax law. Specifically, Section 7701(b)(6) has a provision that can have unintended consequences for the unwary LPR. See, for instance, LPR status can be abandoned for tax purposes (since 2008 tax law changes) by merely leaving and moving outside the U.S. in some cases?
529 College Plans – Funded by Former USCs and LPRs (“Long-Term” LPRs)
There is a basic tax planning opportunity for U.S. taxpayers who wish to fund the costs of higher education for family or friends. These are referred to as “529 Plans” with reference to the tax code section – IRC Section 529. In short, a 529 trust is established and funded with contributions for the benefit of named beneficiaries.
The principle benefit of a 529 plan, is that the income earned from the investments inside the 529 trust fund are exempt from U.S. income taxation.
There are multiple plans that are operated by various institutions, principally in conjunction with various States in the United States. Qualifying higher education expenses also apply to about 350 non-U.S. institutions that currently qualify for distributions out of a 529 Plan; e.g., University of Cambridge, University of Dublin Trinity College, University of Edinburgh, University of Oslo, The University of York, University of Wollongong, etc.
Unfortunately, non-U.S. citizens who are not resident in the U.S. generally are not eligible to establish and form a new 529 plan.
These “529 Plans” fall expressly into the category of a “specified tax deferred account” under the law. See, IRC Section 877A(e)(2).
In short, the law causes the entire amount in the 529 Plan to be treated as distributed to the “covered expatriate” the day before the expatriation date, although no early distribution tax will apply. If a 529 Plan has $500,000, that will represent taxable income to the “covered expatriate” to the extent of the tax-free growth in the plan. For instance, if the individual funded $200,000 into this plan, in this example, and he or she is subject to the 39.6% tax rate upon “expatriation”, this means there will be US$118,800 less to pay for college and universities (i.e., $500,000 less the $200,000 invested; leaving $300,000 X 39.6% = US$118,800 of tax).
This is yet another example, of how and why it is so important to avoid “covered expatriate” status; if permitted by the law in any particular circumstances. See, Certification Requirement of Section 877(a)(2)(C) – (5 Years of Tax Compliance) and Important Timing Considerations per the Statute, also see Can the Certification Requirement of Section 877(a)(2)(C) be Satisfied “After the Fact”?
Careful thought should be taken for the range of considerations and U.S. tax consequences that can befall a former USC or long-term LPR.
Ineligibeility for a SSN after Taking Oath of Renunciation – TINs, ITINs, EINs, etc.
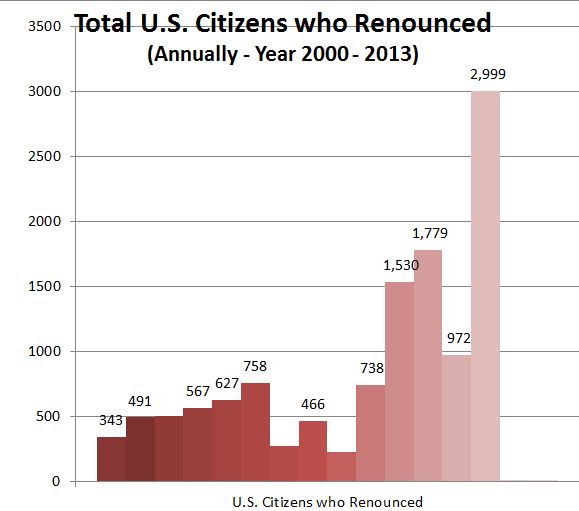
USCs and LPRs residing outside the U.S. have been increasingly renouncing their citizenship and abandoning their lawful permanently residency status, respectively. In some cases, individuals who have lived virtually all (or all) of their lives in a country other than the U.S. are a lmost making a “knee jerk” decision to renounce.
The statistics as to the absolute number and relative increases are astonishing. See, Wow, the number of 2,999 U.S. citizens who renounced in the year 2013 shattered the prior record set in 2011 of 1,782 renunciations. Why so many renunciations?
There is a practical problem for an individual who has renounced his or her U.S. citizenship prior to obtaining a Social Security Number (“SSN”). The individual will NOT be able to obtain a SSN once they have taken the oath of renunciation. See, *Why the Oath of Renunciation is Not the Opposite of the Oath of Allegiance
Of course, as prior posts have explained, an individual must have a “taxpayer identifying number” which must be a SSN for a U.S. citizen. However, the Social Security Administration will not allow an individual who has taken the oath of renunciation to apply for a SSN. See, The Catch 22 of Opening a Bank Account in Your Own Country – for USCs and LPRs
Also, see, Why do I have to get a Social Security Number to file a U.S. income tax return (USCs)?
The only way an individual can avoid becoming a “covered expatriate” is by filing U.S. federal income tax returns and being able to satisfy the certification requirement of Section 877(a)(2)(C). Accordingly, if a SSN is not available, the former citizen will need to file for an ITIN, as explained in previous posts.
IRA Distributions – (Counter-intuitive Results) U.S. Tax Consequences to Former USCs and Long Term Residents (LPRs)
IRA Distributions – (Counter-intuitive Results) U.S. Tax Consequences to Former USCs and Long Term Residents (LPRs)
Those USCs who have renounced citizenship (or who are contemplating renunciation) and those LPRs who (were/are/will) fall into the category of “long-term residents” who have qualified retirement accounts, known as “Individual Retirement Arrangement” (“IRAs”) have special considerations to consider under IRC Sections 877, et. seq. For more details on how IRAs work and the deduction limits, see the IRS website explanation.
In short, if an individual is a “covered expatriate” upon renunciation (or LPR abandonment), they will generally be subject to U.S. income taxation on the entire amount of the IRA (along with all other assets with unrealized gains), reduced by the exemption amount (currently US$680,000 for the year 2014).
Unfortunately, it is fairly easy to become a “covered expatriate” even if the asset or tax liability tests are not satisfied, simply if the individual fails to satisfy the certification requirement under Section 877(a)(2)(C). There are multiple posts that address this important certification requirement of Section 877(a)(2)(C), irrespective of how poor or how few of assets might be held by the individual. See, Certification Requirement of Section 877(a)(2)(C) – (5 Years of Tax Compliance) and Important Timing Considerations per the Statute, also see Can the Certification Requirement of Section 877(a)(2)(C) be Satisfied “After the Fact”?
Plus, the topic is covered yet further in More on “PFICs” and their Complications for USCs and LPRs Living Outside the U.S. -(What if there are No Records?)
Generally “covered expatriate” status is to be avoided, give the various adverse tax consequences. See, for instance, Why “covered expat” (“covered expatriate”) status matters, even if you have no assets! The “Forever Taint”!
However, since the U.S. tax law is complex and oftentimes full of unintended consequences, there may be times when “covered expatriate” status is desirable in any particular circumstance. I have seen and advised on several; including scenarios, where some planning steps can help get a much better U.S. tax result in various cases.
Assume a former USC does not meet the certification requirement (e.g., since they neglected to properly file a complete and accurate IRS Form 8854, or they otherwise did not comply with Title 26 for one or more of the five years preceding the renunciation/abandonment). Further, let us assume, she has an IRA with a total value of US$1.4M and all of her other assets have no unrealized gain (e.g., Euros in a bank in Europe and an apartment she purchased in her country of residence in Europe that continues to have depressed real estate prices). These other assets, the apartment and Euros are US$500,000 in value; hence, less than the US$2M net worth threshold. However, we will assume she did not timely comply with the certification requirements under the law.
In such an “unfortunate” case, she would have to accelerate all of the income (gain) from her IRA in the year she has her “date of expatriation”. This would cause a U.S. federal income tax liability of about US$260,000 that would become immediately due and payable. This amount is calculated as follows: US$1.4M total IRA, less the $680,000 exclusion amount, for a total taxable income of about $720,000 (which will generate an approximate US$260,000 income tax for someone who is not married filing jointly. This represents an effective tax rate of approximately 36% on the taxable income portion (US$260,000/US$720,000). Remember, however, $680,000 escapes taxation under the exclusion amount. Hence, the effective tax rate on the entire IRA portion is actually only about 18.6% in this case. This amount is calculated as total IRA income of US$1.4M against tax of US$260,000 (i.e., $260,000/$1.4M= 18.6%).
An 18.6% tax rate is generally a very “attractive” U.S. individual income tax rate for those who have high amounts of income, as is this case with US$1.4M.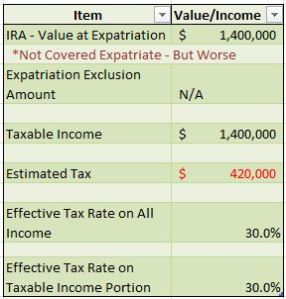
If instead, she is not a “covered expatriate” at the time she renounces her citizenship in 2014 (as she did comply with the certification requirements and otherwise would not meet the $2M net worth and her average annual net income tax liability for the preceding 5 years did not exceed $157,000) she would have a very different tax result. In short, she would not have to accelerate the entire tax liability. That sounds like good news, until one considers the U.S. tax rate on future IRA distributions to her after she ceases to be a U.S. citizen. Absent, an income tax treaty, she would have a 30% tax withheld at source (i.e., by the U.S. payer – trustee of the IRA) on each distribution made. If all US$1.4M is distributed out in one lump sum, there will be a tax of US$420,00 (US$1.4M X 30%); much more than the $260,000 for the “covered expatriate” scenario above. See calculations in this table:
Also, if she prefers to defer the IRA distributions (e.g., to make 14 annual distributions of US$100,000), she will have the same 30% tax withheld on each payment; hence, a total tax of US$420,00.
Obviously, a 30% tax is much worse than an 18.6% tax. Accordingly, this is a scenario where an individual may prefer to be a “covered expatriate” as opposed to avoiding such status. A bunch of factual analysis and strategic considerations would need to be considered in her case (e..g, where are her future heirs, what other income might she receive, will she receive any future gifts of inheritances herself, etc. etc.?).
Indeed, in this particular case, I can imagine a scenario (if accompanied by some focused tax planning), she could pay no more than a total effective tax rate of 12.2% on her income. Of course, 12.2% is better than 18.6% and 30%.
Finally, there is one more important wrinkle that can modify these results yet further; a particular income tax treaty with the U.S. that has a specific tax result that is better than the statutory 30% rate on distributions from an IRA to a non-resident alien. The U.S. has numerous income tax treaties with numerous countries, almost all of which have different terms and conditions. See, Countries with U.S. Income Tax Treaties & Lawful Permanent Residents (“Oops – Did I Expatriate”?)
Li Lianjie – Famous Former U.S. Citizens – Born in Beijing, China (“Jet Li”)
The Chinese actor Li Lianjie, who is better known by his stage name Jet Li, was born in Beijing. He was born in 1963 and his father died when he was just 2 years old and he “. . . was from a very poor family and . . . didn’t have enough money for a good school, so sports-school was good . . . ”
He is a huge star in China and throughout Asia and became famous in Hollywood.
As a teenager he became a master at Wushu, the full-contact sport from Chinese martial arts. His martial arts fame led to acting, first in China and also in the United States. His film debut Shaolin Temple (1982), helped make him a star.
He apparently became a naturalized citizen of the United States while working in Hollywood.
He apparently has also become a naturalized citizen of Singapore.
He is often highlighted by government officials of China as a model citizen and success story. 
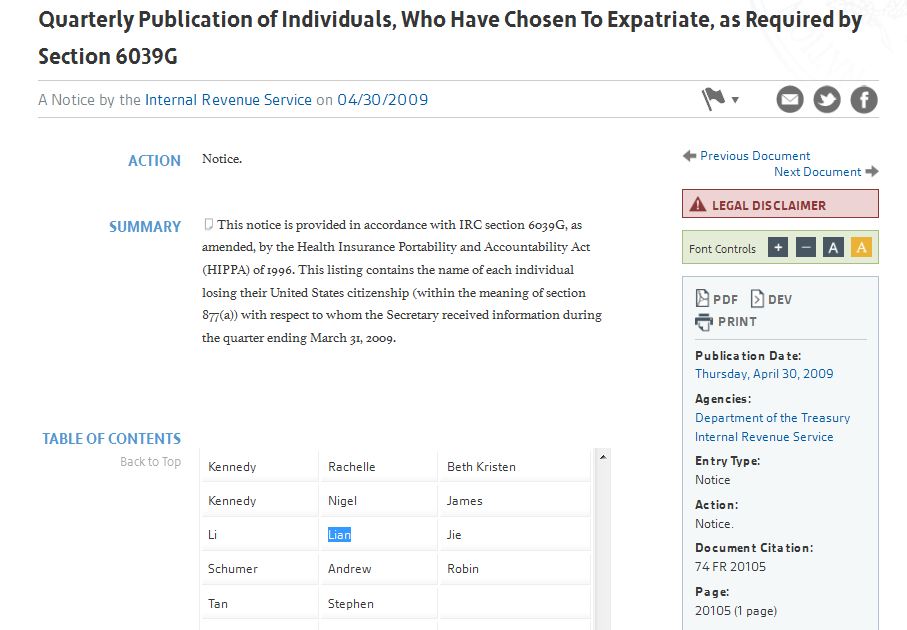
By the year 2009 he renounced his U.S. citizenship as listed in the U.S. federal government’s “Quarterly Publications of Individuals, Who Have Chosen to Expatriate, as Required by Section 6039G“
See here the list for the first quarter of 2009, where Li Lianjie is in the 2009 first quarter list of expatriates.
Presumably, Jet Li solicited timely and filed for a Certificate of Loss of Nationality (“CLN”) timely so he was not subject to the rules of 7701(a)(50) that went into effect in 2008 – See, Why Section 7701(a)(50) is so important for those who “relinquished” citizenship years ago (without a CLN). . .
Finally, the certification requirement that is available to those individuals who are born with dual national citizenship to avoid “covered expatriate” status, was presumably not available for Li Lianjie, since he was not born a U.S. citizen. Presumably, he could not satisfy each of the requirements of IRC Section 877A(g)(1)(B).
IRS Sting Operation and Criminal Tax Indictments of Canadian Citizens – Investigations Overseas – Enabling U.S. Taxpayers with Offshore Accounts
The U.S. Department of Justice reported that two Canadian citizens along with a U.S. citizen were indicted for enabling tax evasion with offshore accounts. The press release from three months ago, 24 March 2014, can be reviewed here. Some highlights of the press release are below:
- According to the indictment, . . . Poulin, an attorney at a law firm based in Turks and Caicos, worked and resided in Canada and in the Turks and Caicos. His clientele also included numerous U.S. citizens.
- According to the indictment, Vandyk, St-Cyr and Poulin solicited U.S. citizens to use their services to hide assets from the U.S. government. Vandyk and St-Cyr directed the undercover agents posing as U.S. clients to create offshore foundations with the assistance of Poulin and others because they and the investment firm did not want to appear to deal with U.S. clients. Vandyk and St-Cyr used the offshore entities to move money into the Cayman Islands and used foreign attorneys as intermediaries for such transactions.
- According to the indictment, Poulin established an offshore foundation for the undercover agents posing as U.S. clients and served as a nominal board member in lieu of the clients.
The facts of this case will be interesting to cover, to see how and to what extent the IRS and Justice Department will be focusing on U.S. citizens residing overseas and their reporting (or failure to report) their “foreign” accounts; i.e., their financial accounts in their home countries of residence.
Since the withholding tax provisions under the Foreign Account Tax Compliance Act (“FATCA”) come into effect in a matter of days, it will be interesting to see if the government has more indictments along these lines planned for the summer of 2014.
U.S. citizens who are in the process of renouncing citizenship should be aware of each of the steps required as part of the process; both under U.S. federal tax law and immigration law.
See, The Importance of a Certificate of Loss of Nationality (“CLN”) and FATCA – Foreign Account Tax Compliance Act.
Also, see Revisiting the consequences of becoming a “covered expatriate” for failing to comply with Section 877(a)(2)(C).
IRS Commissioner’s Comments – Is He Listening to USCs and LPRs Living Around the World!?
The IRS Commissioner’s comments earlier this week may signal an important change in policy and approach to USCs and LPRs residing overseas? See, his full remarks set out in the paper presented at the OECD international tax conference:
– OECD – INTERNATIONAL TAX CONFERENCE WASHINGTON, D.C., JUNE 3, 2014
***
This tax-expatriation.com website is largely dedicated to USCs and LPRs who reside outside the U.S. Those who are not living in the U.S.
In some of the more extreme cases, these USCs and LPRs are (i) renouncing (or proving prior relinquishment) of their U.S. citizenship, or (ii) formally abandoning their LPR or terminating the status by application of the tax law, respectively. See, The List is Out – and Its 1,001 Former U.S. Citizens for the 1st Quarter 2014
For further reading on USCs see, Why “covered expat” (“covered expatriate”) status matters, even if you have no assets! The “Forever Taint”!
For further reading on LPRs, see, Countries with U.S. Income Tax Treaties & Lawful Permanent Residents (“Oops – Did I Expatriate”?)
There are a multitude of reasons for taking this step, but a common theme for many individuals (especially with limited financial resources) arises from (1) the costs in time and resources – e.g., time required to collect financial information from banks in their country of residence, which cannot easily be converted for U.S. tax law purposes – professional fees to U.S. tax advisers for filing annual tax returns and information returns such as FBARs, and (2) the very high penalties assessed under the law for not filing such forms and information. See, USCs and LPRs Living Outside the U.S. – Key Tax and BSA Forms.
See, for instance, Nuances of FBAR – Foreign Bank Account Report Filings – for USCs and LPRs living outside the U.S.. See, When does the Statute of Limitations Run Against the U.S. Government Regarding FBAR Filings?
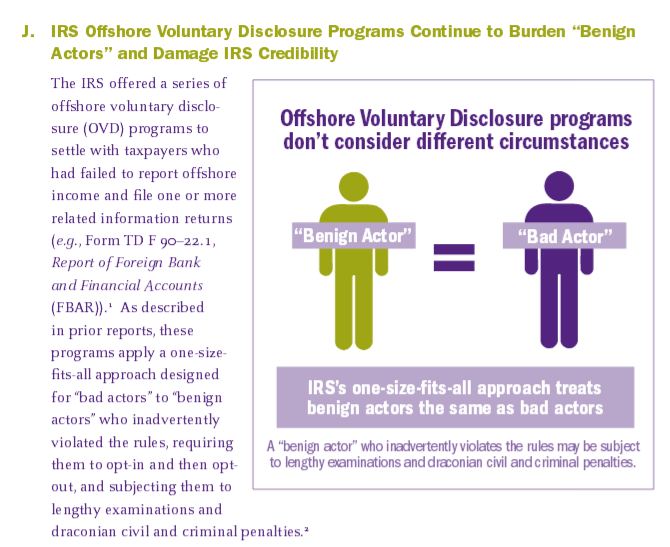
Also, see, “PFICs” – What is a PFIC – and their Complications for USCs and LPRs Living Outside the U.S. Plus, USCs and LPRs residing outside the U.S. – and IRS Form 8938. In addition, see, Taxpayer Advocate Report on Burdens of Benign Taxpayers who Make Mistakes 
All of these complications for USCs and LPRs living outside the U.S., is a most compelling reason for the IRS Commissioner to provide a more sensible approach to how the government focuses their attention on USCs and LPRs residing overseas. How will they be treated?
How will the long-arm of the U.S. law that extends around the world be administered by IRS revenue agents?
Will the new policy announcements, which are apparently forthcoming, provide a genuine balance of allowing the IRS to enforce the law in a balanced and fair-minded approach with USCs and LPRs residing overseas? Will there be a clear distinction between those who are in good faith attempting to comply with the law (even if they have made numerous “technical foot faults” in how the law applies) versus those USCs and LPRs who have taken steps to hide assets and evade U.S. taxes?
Or will the IRS continue to “beat the drums” of non-compliance of these individuals and emphasize the penalties the government can assess under the law? See my earlier post, IRS Beats the Drums – Re: Foreign Assets, Just Days Before April 15,
It seems that only a fair-minded approach by the IRS and the Justice Department, will lead to better U.S. tax and FBAR compliance worldwide of USCs and LPRs residing overseas. This should be true, even in light of the vast treasure trove of FATCA foreign financial data which the IRS will begin collecting throughout the world for this calendar year 2014. See, The Importance of a Certificate of Loss of Nationality (“CLN”) and FATCA – Foreign Account Tax Compliance Act.

 laypeople can often cause very adverse tax consequences to themselves and their friends and family members (in the case of tax expatriation) without understanding the full implications of the law.