Below is a fairly detailed summary of the type of tax crimes that are commonly investigated by IRS Criminal Investigation (“CI”) agents.
As has already been noted, TaxAnalysts reporter Jaime Arora reported in the 3 March 2014, Worldwide Tax Daily certain comments made by Mr. Jeffrey Cooper, who is the deputy director of the IRS Criminal Investigation division’s international operations. It was reported that IRS CI is looking into why people are making the choice to shed their U.S. citizenship; whether it is related to any particular laws. Cooper was quoted at the Federal Bar Association’s Section on Taxation’s 38th Annual Tax Law Conference held on February 28, 2014.
TaxAnalysts journalist Arora quoted Cooper as identifying why people are making the choice and “If we find something, we do; if not, we just move on,” he said.
It is common policy for the IRS CI not to provide information on how they commence taxpayer investigations, including how they obtain U.S. citizenship renunciation referrals or documents. There could be a number of ways these investigations are commenced. It may be as simple as taking the list from the Quarterly Publication of Individuals, Who Have Chosen to Expatriate – Quarterly Publication of Individuals, Who Have Chosen To Expatriate, as Required by Section 6039G and start reviewing their tax return files (IRS Forms 1040, 8854, etc.) along with FBAR filings.
IRS CI tax investigations generally focus on false documents or false statements, evasion of taxation, aiding and abetting of the above along with other related tax and Bank secrecy (Title 31) crimes.
The tax reporting process for expatriates is extensive, including the basic requirement of signing IRS Form 8854 under penalty of perjury, which provides as follows on the last page of the form:
There are a host of reporting requirements and factual information that must be provided under Sections 877 and 877A, for all persons (including those with little to no assets), specifically including filing IRS Form 8854 which asks for a “boat load” of asset, income, liability and tax information. A former U.S. citizen or LPR always needs to be careful that the information provided is true, accurate and complete. See Part V of the form.
A summary of these crimes is set out below:
1. Criminal Offenses under Title 26 (Federal Tax Law)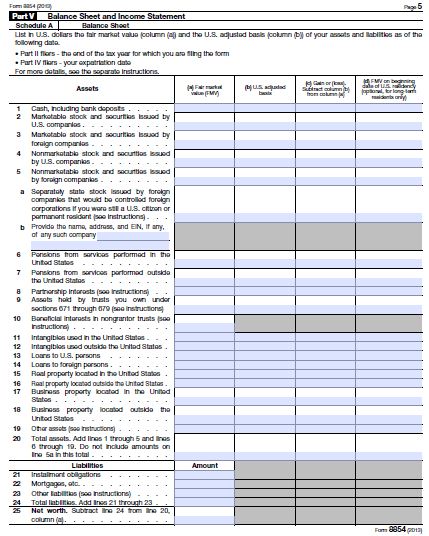
a. Tax Evasion (IRC Section 7201)
b. Filing a False Return or Other Document – Perjury (IRC Section 7206(1) )
(i) Aiding or assisting in the perpetration of a false or fraudulent document (26 U.S.C. § 7206(2))
(ii) Removal or concealment with intent to defraud, commonly related to untaxed liquor (26 U.S.C. § 7206(4))
(iii) Compromises and closing agreements involving fraud or concealment (26 U.S.C. § 7206(5))
c. Failure to File Return, Supply Information, or Pay Tax – (IRC § 7203 – Misdemeanor – up to 12 months imprisonment)
d. Fraudulent Returns, Statements, or Other Documents (IRC § 7207)
e. “Structuring” Transactions to Evade Cash Reporting (IRC § 6050I)
In addition to these tax specific crimes, other key crimes commonly used by IRS CI agents in tax cases, particularly international cases, include: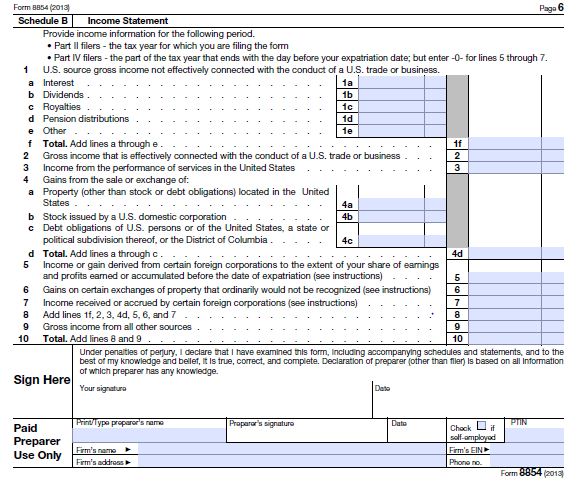
2. Tax Related Criminal Offenses under Titles 18 and 31 (Not Tax Law Specific)
a. Conspiracy (Section 371 of Title 18)
(i) Elements of the Offense
(ii) Penalties and Statute of Limitations
b. False Statements (Title 18 U.S.C. § 1001)
(i) Penalties and Statute of Limitations
c. Perjury
d. Mail fraud
e. Principals and those Who Aid and Abet (Title 18)
f. Accessory After the Fact
Finally, it is worth noting that the government regularly collects information from internet resources, such as blogs and e-mails as they build a case for criminal prosecution. A former head of the Tax Division at the U.S. Department of Justice once told me that “e-mails and internet communications was God’s gift to prosecutors”.
???????????????? ?Please click here to view the above in Chinese.?